With a market cap of $103 billion, Canadian Pacific Kansas City (TSX: CP) is one of Canada’s largest blue-chip stocks. It has a 144-year history operating in North America. Its business has certainly stood the test of time.
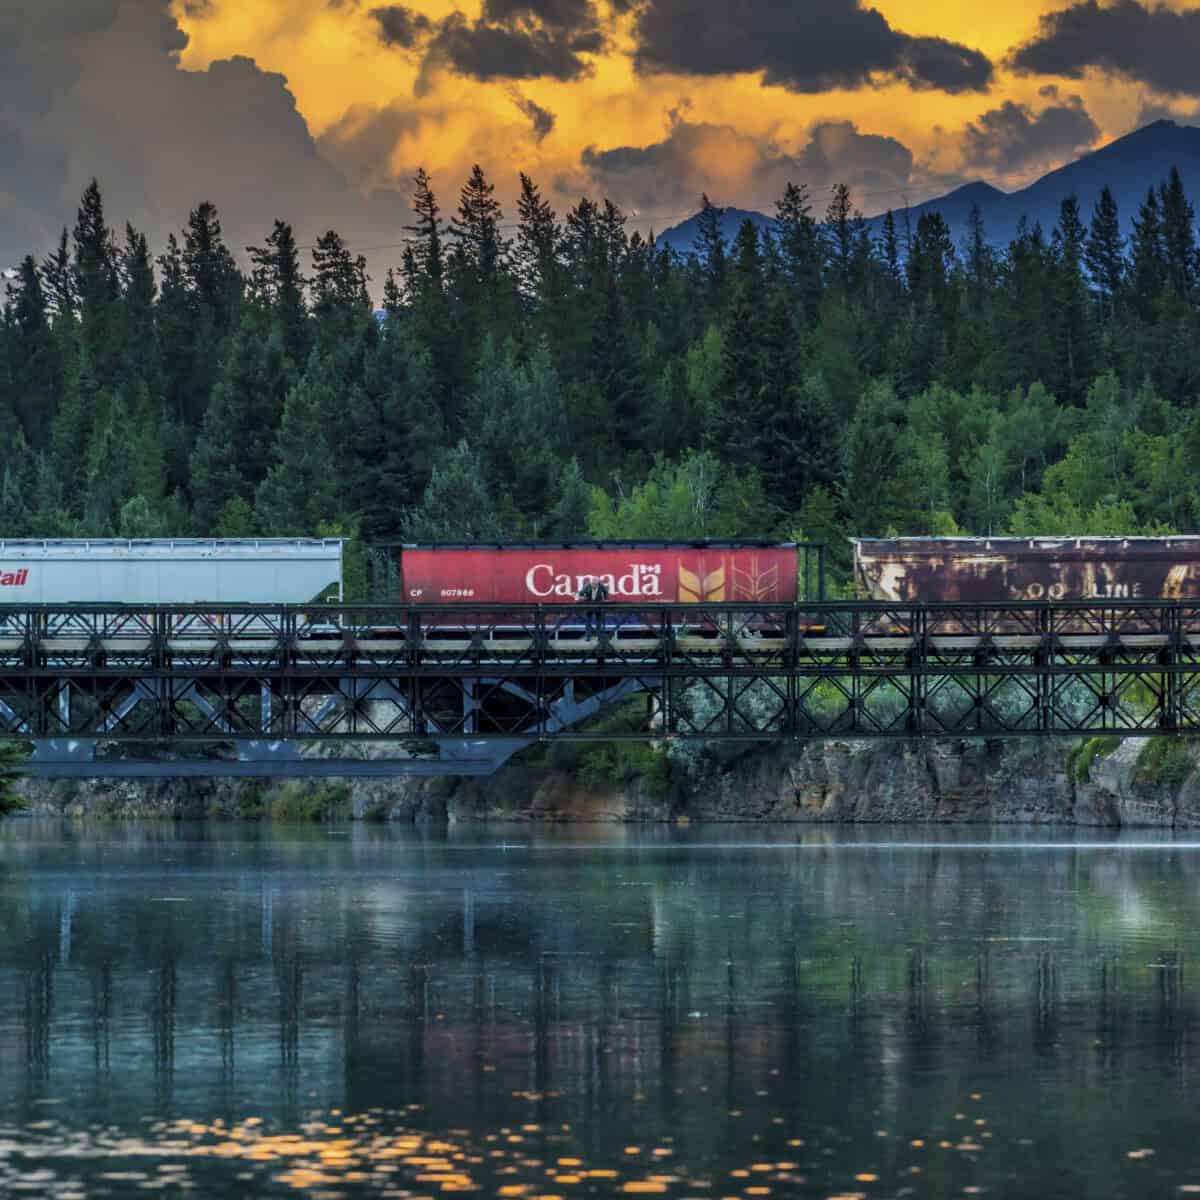
Source: Getty Images
This 144-year company just became substantially larger
Until a few years ago, CP’s network was largely based in Canada. That all changed when it was approved to acquire Kansas City Southern (KCS) in late 2021. With that, it acquired a network that expanded its rail line across Canada, the U.S., and Mexico. It was considered a transformational deal. Today, CP is the only railway with a network that extends across North America.
The new network provides CP with considerable advantages and opportunities. CP now reaches multiple ports in the Pacific and Atlantic oceans. It gives shippers a variety of options on where to send their goods to international markets. In many instances, this optionality can create considerable time and money savings.
Likewise, CP’s network can help reduce backlogs at borders. This network makes the transportation of goods and bulk commodities that much faster across the continent. The new network is beneficial to CP’s customers, and that should be beneficial to its earnings growth.
The synergies from CP’s amalgamation are better than expected
Just from the amalgamation, CP is expected to extract US$1 billion in synergies. However, many analysts believe it could extract $1.5 billion or better. Despite facing a freight recession since 2022, CP has consistently outperformed its railroad peers. Since 2022, earnings per share is up 9% to about $4.12 for the past 12 months.
While that is below the double-digit growth rate that management has promoted, it is better than most peers. Likewise, CP delivered growth even through a very challenging operational, trade, and economic environment.
A fast-improving balance sheet
Despite challenges, CP continues to be a strong cash generator. Since the acquisition of KCS, it has generated $6.6 billion of cash. It took on significant debt to acquire KCS, so it has been quick to pay that down. Net debt-to-earnings before interest, tax, depreciation, and amortization (EBITDA) has decreased from 4.2 times to 3.1 times today.
Its balance sheet is quickly improving. In its most recent quarter, management was confident enough to boost its dividend by 20% and announced a 4% share buyback.
This is likely a sign of more good things to come. Not only is CP unlocking strong synergies, but it is also gaining unexpected growth opportunities. CP’s management has targeted double-digit earnings-per-share growth for the next four to five years.
If CP can hit its growth targets, there is still ample return upside
Given that this management team has one of the best operational and financial track records in the industry, there is good reason to believe them. Its balance sheet continues to improve. Likewise, the economic flexibility in its network provides both stability and growth for investors.
Chances are good that further strong free cash generation will allow CP to reduce debt and continue increasing its dividends and buying back shares.
CP may be a blue-chip stock. However, it has a very exciting growth trajectory. Its stock is one of the most expensive railroads. The market recognizes its growth potential.
However, if the stock pulls back on any broader market correction, it could be a great opportunity to add CP stock for a long-term hold. If it can hit its ambitious target, this stock could see 50-100% upside from today’s price.