


After a volatile start to the year, Canadian equity markets have staged a strong recovery from their March lows, with the S&P/TSX Composite Index gaining 11.7% since then and climbing 9.7% year to date. However, concerns surrounding higher energy prices, persistent inflationary pressures, and ongoing geopolitical tensions continue to cloud the broader economic outlook.
Given this uncertainty, investors should focus on strengthening their portfolios with quality companies that possess resilient business models, reliable dividend payouts, and solid long-term growth potential. Against this backdrop, let’s examine Enbridge (TSX: ENB) by evaluating its business model, dividend history, and future growth prospects to determine whether the stock remains an attractive investment over the next three years.
First, let’s take a closer look at Enbridge’s business outlook.
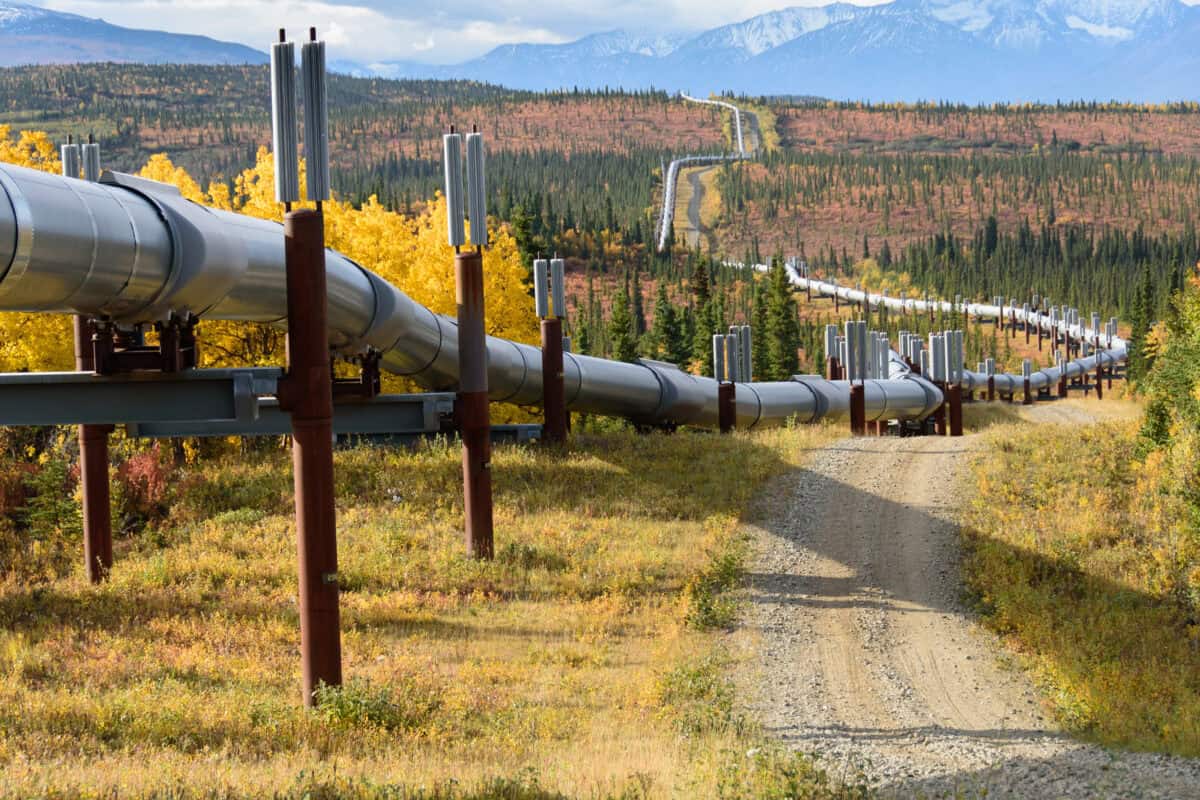
Source: Getty Images
Enbridge’s business outlook
Enbridge operates one of North America’s largest energy infrastructure networks, transporting crude oil and natural gas through a vast pipeline system supported by a tolling framework and long-term take-or-pay contracts. In addition, the company owns three low-risk natural gas utility businesses in the United States and a growing portfolio of renewable energy assets backed by long-term power-purchase agreements (PPAs). Overall, nearly 98% of Enbridge’s earnings are generated from regulated assets or long-term contractual arrangements, and approximately 80% are indexed to inflation.
This highly predictable business model limits the company’s exposure to commodity price swings, economic slowdowns, and broader market volatility, enabling it to generate stable, dependable cash flows across market cycles. Backed by these resilient financials, Enbridge has delivered an average annual total shareholders’ return of 12.9% over the last two decades. The company has also built an impressive dividend track record, having paid dividends for 70 consecutive years and increased its payouts annually for 31 straight years. Its quarterly dividend of $0.97 per share currently yields around 5%.
With a strong and defensive business foundation in place, let’s now examine Enbridge’s long-term growth prospects.
Enbridge’s growth prospects
Growing oil and natural gas production across North America continues to drive demand for Enbridge’s infrastructure and related services. Supported by this favourable backdrop, the company has identified nearly $50 billion in potential growth opportunities over the next five years. It plans to invest approximately $10 billion to $11 billion annually to advance these projects. Enbridge is also making steady progress on its secured $40 billion capital program, with several major projects expected to come online over the next few years.
Driven by these expansion opportunities, Enbridge’s management expects adjusted earnings per share (EPS) and distributable cash flow (DCF) per share to increase at an annualized rate of around 5% for the remainder of the decade. The company also maintains a solid financial position, ending the first quarter with $12.7 billion in available liquidity and a manageable payout ratio, both of which support the sustainability and future growth of its dividend distributions.
Given its visible cash flow growth and strong balance sheet, Enbridge expects to return between $40 billion and $45 billion to shareholders over the next five years through dividends and other shareholder-friendly initiatives, reinforcing the reliability of its future payouts.
Investors’ takeaway
Over the last three years, Enbridge has delivered impressive returns to its shareholders, generating a total return of 86.9% and an annualized return of 23.2%. Despite this strong performance, the stock continues to trade at a reasonable valuation, with a next-12-month price-to-sales multiple of 2.9.
Currently, Enbridge trades at $77.58 per share. If it maintains a growth trajectory similar to that of the past three years, the company’s stock price could climb to around $145.02. Even under a more conservative scenario based on its average annual return over the last 20 years, Enbridge’s stock price could rise to approximately $111.67 over the next three years, which is reasonable and makes the stock an excellent buy even in this uncertain outlook.







