


Canadian income investors don’t always have to settle for slow quarterly payouts or low-yielding guaranteed investment certificates (GICs). Sienna Senior Living (TSX: SIA) stock, a retirement home provider, offers a compelling passive income stream. It pays a reliable 4.7% dividend yield distributed in 12 monthly installments. Over the past five years, Sienna stock generated a massive 125% peak total return. An 87% total gain remains intact today despite recent market pullbacks, while the dividend remains an unsung hero.
Capital appreciation has accounted for a modest 36% gain, while monthly dividends drove overall returns. Without this payout stream, Sienna’s capital returns would have widely lagged the broader market. But the future is looking more promising.
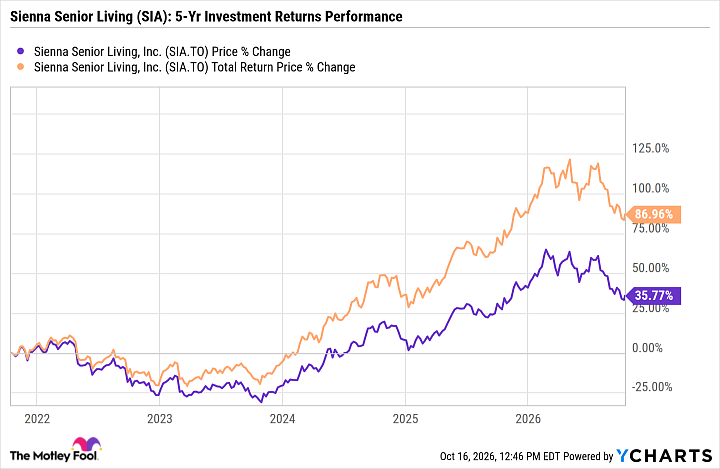
The Sienna stock dividend has been instrumental in lifting total returns on the demographics tailwinds play, and its highly likely that the payout will remain a key returns driver. The monthly dividend stock is likely to restart dividend raises after a long pre-pandemic pause.
Source: Getty Images
Sienna Senior Living’s demographic tailwinds and tax advantages
Sienna operates long-term care beds and private retirement residences across Ontario, British Columbia, Alberta, and Saskatchewan. An undeniable, and potentially accelerating demographic shift drives long-term demand for its retirement home offerings. Canada’s population aged 85 and older could triple over the next two decades. And Sienna Senior Living’s retirement portfolio occupancy rates recently increased by 150 basis points to 94.1%.
The business’s revenue, earnings and cash flow generating capacity are growing as it caters to a growing client base. Second-quarter same property net operating income surged 19.4% higher, year over year. In August, Sienna partnered with Fiera Capital in a $625 million redevelopment projects plan in Ontario that adds bed capacity and modernizes its offerings. Revenue and earnings growth may accelerate faster, supported by acquisitions.
Most noteworthy, investors stashing this growing monthly dividend stock in taxable accounts enjoy some advantages they won’t get if they load up on Sienna’s closest peers.
Unlike pure Canadian Real Estate Investment Trusts (REITs), Sienna is structured as a taxable corporation. Its distributions are thus classified as eligible dividends for tax purposes. Eligible dividends qualify for the Canadian Dividend Tax Credit in non-registered accounts. This tax advantage sets Sienna Senior Living stock apart from close peers like Chartwell Retirement Residences and Extendicare.
SIA’s financial realities and inflation protection concerns
Critically evaluating this monthly dividend stock as a reliable passive income source for the next several years requires weighing its sector tailwinds against financial risks.
As a real estate play, Sienna carries significant debt obligations that require active management in fluctuating rate markets. Operating cost inflation and wage pressures also require disciplined corporate execution as the business captures more opportunities across Canada.
Is this passive income opportunity better than a GIC on a risk-adjusted basis? While fixed GICs lack capital upside, Sienna stock may generate capital gains that provide more than inflation protection, and the dividends could begin to rise again.
Recent operational results demonstrate strong growth momentum. Adjusted funds from operations (AFFO) per share are growing, and a recent drop in AFFO payout rates is reassuring that there’s room for dividend growth now.
Should you invest for passive income
Dividend safety is where Sienna’s financial profile shines brightest lately. The company pays a monthly distribution of $0.08 per share. That equals an annualized payout of $0.94 per share. Its payout ratio recently dropped from 89.5% down to a conservative 72.3%. A low payout ratio provides a solid safety buffer for income investors.
Investors can also enroll in Sienna’s Dividend Reinvestment Plan (DRIP). The DRIP issues new shares at a 3% market discount. This discount accelerates long-term compounding without paying extra transaction fees.
Foolish bottom line
Holding Sienna Senior Living stock in a TFSA or taxable account still adds valuable tax efficiency. You collect regular monthly cash flow backed by an aging population.
A forward price-earnings-to-growth (PEG) ratio of 0.3 implies SIA stock could be undervalued given its future earnings growth potential.
Meanwhile, a 3% DRIP discount should give long-term compounders an extra tactical advantage that makes SIA stock’s 4.7% dividend stream a core holding for steady growth and sustainable monthly income.







