


How much money could you really earn by investing $500 a month?
That’s a pertinent question, because many working-age Canadians are following a policy like the one just outlined, investing a few hundred a month with hopes of eventually having a sum they can retire off of.
It’s a policy that has been proven to work over the long term.
Provided you invest in sensible things, you could end up with quite a bit of money in your account after 30 years of $500 per month of investing.
Here’s how much.
Source: Getty Images
About $1 million
If you invest $500 per month, and each $500 monthly investment earns a 10% compounded annual growth rate (CAGR), you end up with $1.04 million at the end. I figured this out in Excel. The data table is too large to share here, so I’ll just include a little screenshot below showing the ending amount for the column in which I calculated the ending amounts of several monthly contributions.
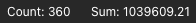
By investing $500 a month at a 10% compounded annual rate of return, you can end up with a handsome sum of money at the end. So clearly, the “dollar-cost averaging” strategy – the strategy of investing a little every month instead of throwing a massive lump sum into the markets all at once – works.
Why dollar cost averaging works
Dollar-cost averaging works for a few reasons.
First, regular people usually don’t have large lump sums to throw into the markets all at once. They can obtain large sums only by borrowing – and with an asset class as volatile as stocks, borrowing your way in usually isn’t the best idea. For these investors, dollar-cost averaging is the only reasonable way to gain access to the compounding benefits of the stock market.
Second, dollar-cost averaging spares you the need to time the market. When investors time the market, they risk getting inferior returns. The reason is, if you buy too high, you may endure inferior returns for years after the buy. While the stock market is known for delivering good returns over the long run, throwing your entire net worth into stocks right before a “lost decade” is a good way to lose a lot of money. DDollar-costaveraging spares you that fate.
What to invest in
Above, I showed that $500 per month invested at a 10% rate of return can easily turn into $1.04 million. That’s a decent sum of money. The question is, what can you invest in that can be reasonably expected to deliver such a return?
Short answer:
Index funds.
Low-fee index funds deliver roughly the same return as the broader markets, and stocks tend to do about 10% per year over the long run.
Take the iShares S&P/TSX 60 Index Fund (TSX: XIU), for example. It’s an index fund made up of the 60 largest Canadian stocks by market cap. It has an ample amount of diversification, a low management fee (0.15%), and a high amount of liquidity. These characteristics all add up to ensure a satisfactory return at low risk. Over the long run, XIU has returned about 10% a year. It stands a decent chance of continuing to do so in the future.







