As a young investor, you can afford to take on a bit more risk to maximize your long-term returns. This means picking the stocks of promising companies with growth prospects, even if the stock may seem “expensive” based on traditional valuation metrics. Unless there is a market-wide correction, great growth stocks rarely ever trade at low multiples, that’s because investors are willing to pay a huge premium for what they believe is the next big thing.
A young investor can more easily recuperate from a major loss, but that doesn’t mean you should jump head first into high-flying speculative stocks with questionable fundamentals. You don’t need to take on a huge amount of risk to get a great growth stock. If you know where to look, you can take just a little bit more risk for a lot more reward, which is a great deal if you have the discipline to stick with a company for a decade or more.
Restaurant Brands International Inc. (TSX: QSR)(NYSE: QSR) is a terrific long-term growth play whose management team is always busy finding ways to drive long-term value for shareholders. You’re probably familiar with 3G Capital, the masterminds behind Restaurant Brands. This management team will do almost anything in their power to improve long-term profitability, even if that means cutting out perks for its executives.
It’s not a mystery why Warren Buffett loves 3G Capital. 3G Capital has similar values to the Oracle of Omaha, and this is why I believe Restaurant Brands should be a core holding for any serious growth investor seeking capital appreciation and long-term dividend growth.
More acquisitions may be ahead
As the name suggests, Restaurant Brands was designed to be an acquisition vehicle in addition to a restaurant operator. 3G Capital acquires promising restaurants which haven’t reached their true potential and then proceeds with operational efficiency initiatives as well as organic and inorganic growth initiatives.
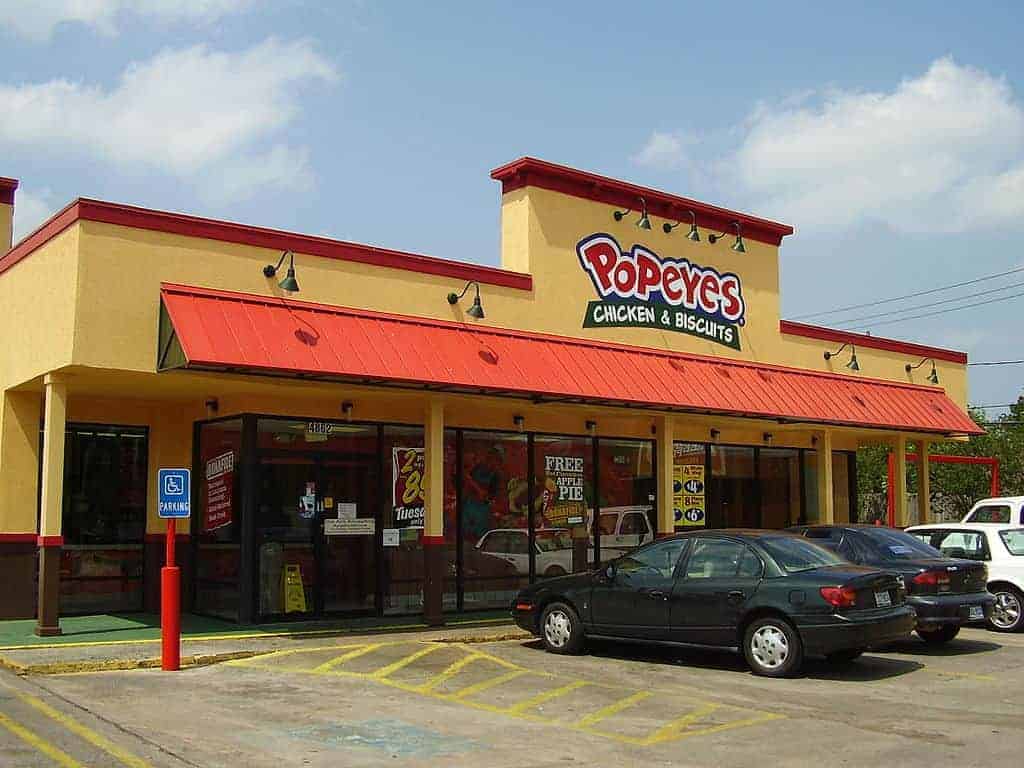
Tim Hortons and Popeyes Louisiana Kitchen are in the early stages of what I believe will be incredible international growth stories, like Burger King was in the past; however, the management team is continuously on the hunt for the next promising restaurant brand.
Sure, the company just acquired Popeyes Louisiana Kitchen, but that doesn’t mean another deal isn’t around the corner. 3G Capital is a value-conscious management team with a long-term view, so you can be assured that the company will not make an acquisition for the sake of boosting the stock in the short term. If an opportunity presents itself, then the company will go for it, even if that means taking on more debt.
Takeaway
3G Capital has the formula it needs to make shareholders huge winners over the long term. I would recommend buying shares of Restaurant Brands on the current dip if you’re looking for sustainable long-term growth.