


Cineplex Inc. (TSX: CGX) continues to violently plunge following what many deemed was an abysmal quarter which saw the company take several steps back compared to the same quarter a year before. Shares are now down a whopping ~30% since my sell recommendation just over a month ago.
Over the past few years, Cineplex has delivered top-notch returns, and because of this, many Canadians became attached to the market darling. Not only did the company offer a fairly high dividend, but it also delivered a fair amount of capital gains to go with frequent dividend hikes. Growth eventually dried up, as I predicted, and going forward, the management team is going to be scrambling to reinvent itself to become great again.
Industry-wide weakness may stick around for the long haul
It’s not just Cineplex that’s suffering. Many U.S.-based movie theatre companies have taken a massive hit on the chin of late. The movie and popcorn business is old, and it’s really difficult to grow in an industry that I believe may be going the way of the drive-in theatre.
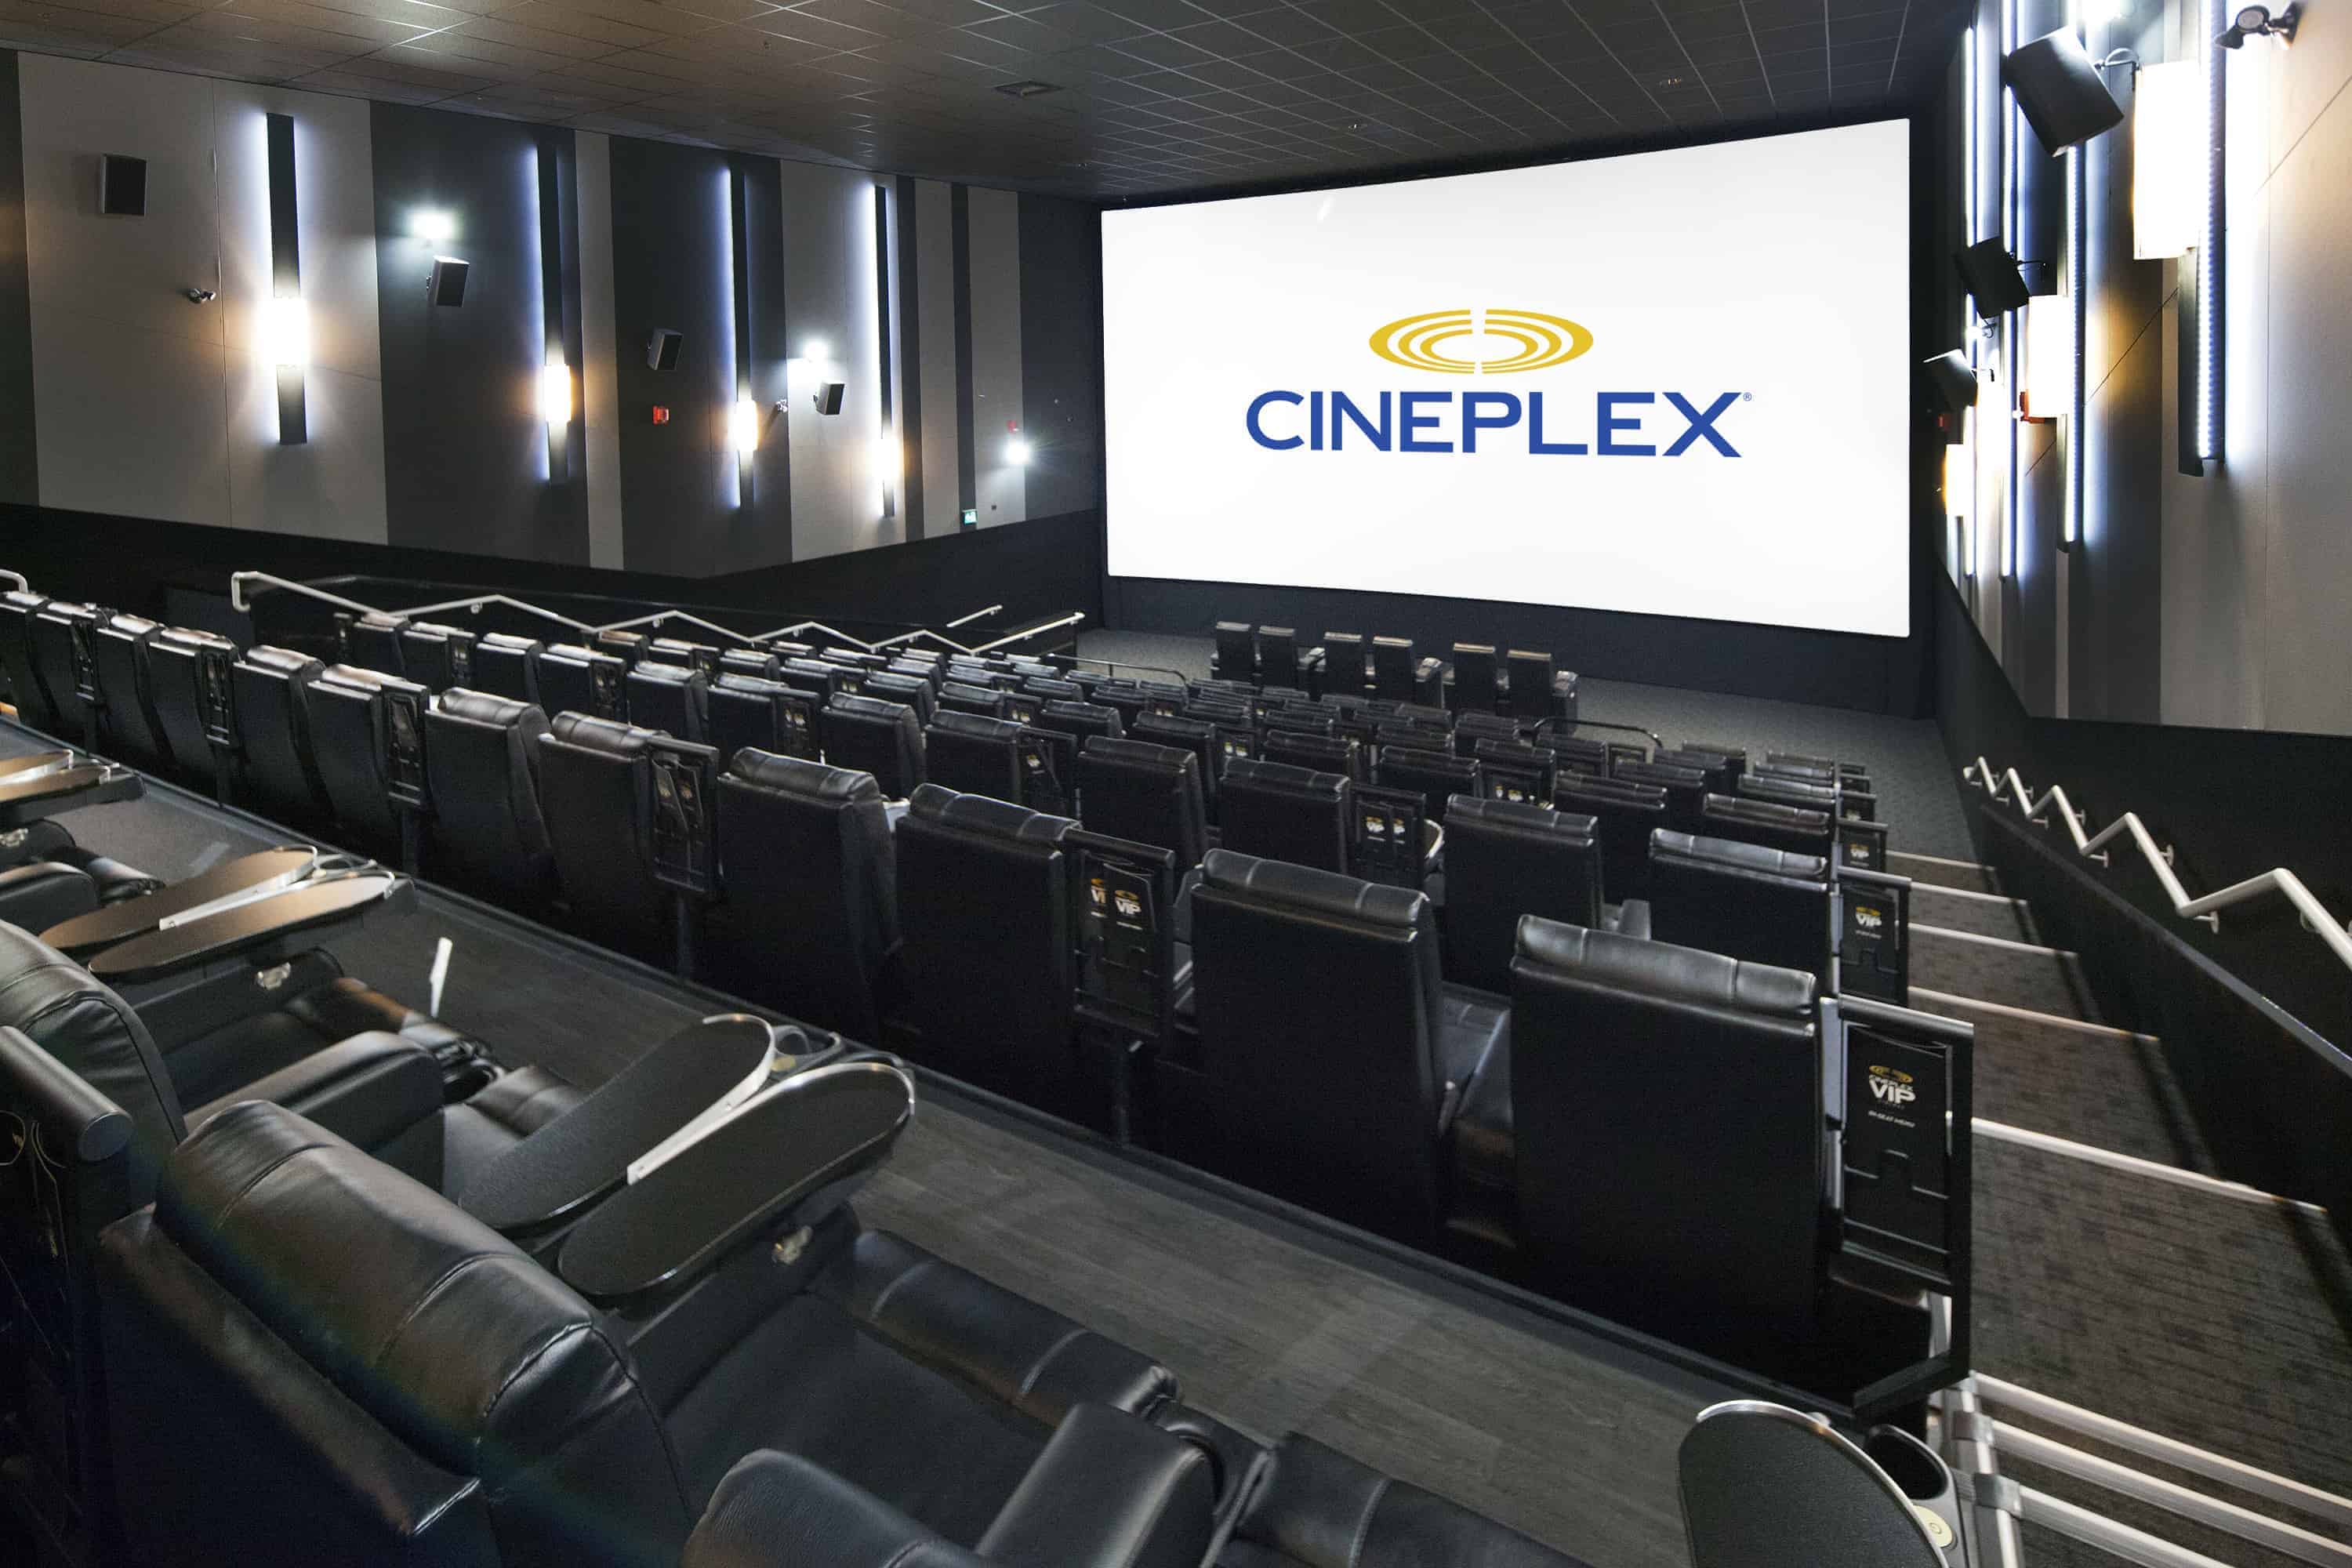
Aside from the rise of the “stay-at-home” economy, another reason why Cineplex may continue to go down is that I’ve found that the customer experience for non-VIP members has gone down significantly over the past few years. I’m an avid movie-goer, I usually go to various Cineplex locations to get a movie fix on a bi-weekly basis, and I’ve found the experience isn’t the same as it used to be — at least for non-VIP theatres.
VIP is a great, but expensive experience for movie-goers, but for everyone else, non-VIP has become quite underwhelming of late.
Go see Annabelle: Creation this weekend in a non-VIP theatre, and you’ll probably know what I’m talking about. You know the quiet part right before the jump scare? You’re supposed to be able to hear a pin drop before a monster pops out and frightens everyone, but instead you hear a symphony of squeaking seats from all directions. The seats are in dire need of oil and the cushions are peeling. I’m not sure if this is the case across a majority of non-VIP locations, but the ones I go to usually are in desperate need of renovations.
Is the management team is cutting costs by not renovating non-VIP theatres while VIP theatres get all the attention? It’s quite possible, especially since renovating over 1,600 ageing locations on a consistent basis isn’t exactly a cheap or growth-driving initiative.
Recent growth initiatives: Too little, too late
Cineplex has done a great job reinventing the movie-going experience, but it’s clear they’re completely out of ideas as box office numbers tumble. Does the average consumer really want to go out to a movie anymore when there’s a tonne of entertainment options from home? Going to a movie can be quite expensive if you splurge at the concession stands (which many of us can’t resist!), so it’s often better to just stay at home and stream your favourite movies or order an on-demand video from your cable provider (if you haven’t cut the cord yet).
What are the growth initiatives now? Rec Rooms, eSports, and Topgolf, just to name a few. I think all of these “initiatives” are good to have, but let’s be realistic. These initiatives aren’t going to offset the major weakness in the movie theatre industry. As it stands right now, Cineplex doesn’t have meaningful growth prospects, which make a 30 price-to-earnings multiple reasonable. That’s right, even after the ~35% crash, Cineplex is still ridiculously expensive!
What will Cineplex do?
That’s not to say that Cineplex doesn’t have any long-term plans though. The company will need to move away from the movie and popcorn business if the stock is going to get out of its funk. Topgolf is just the start of what I think is a move to become an entertainment company. The Cineplex of the future could be a fun house, but that’s obviously going to take a lot of time and investment dollars.
Over the medium term, I expect Cineplex to continue to get hit because investors are starting to realize that it’s ridiculous to be paying north of 30 times earnings for a business in an industry that may be getting killed by the “stay-at-home” economy, which I believe is here to stay for the long term.
I’m not sure if the movie theatre business is dying, but one thing’s for certain: there are major long-term headwinds working against Cineplex, and it’s going to be a tough road ahead for the management team. Bottom fishers may want to wait until that 5% yield arrives before buying shares, because at this pace, you won’t need to wait very long.
Stay smart. Stay hungry. Stay Foolish.







