


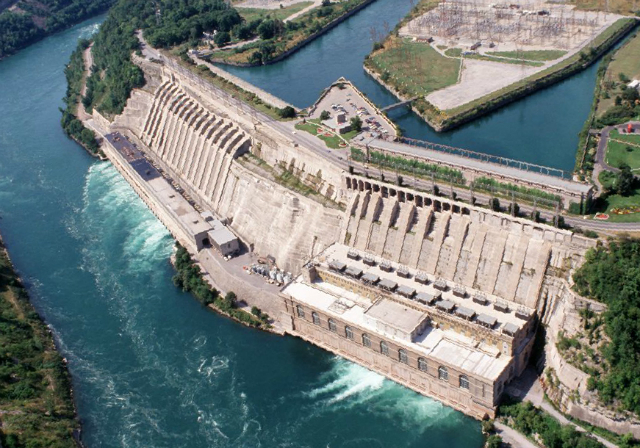
Photo: Ontario Power Generation - Adam Beck Complex. Rotated. Resized. Cropped. Licence: https://creativecommons.org/licenses/by-sa/2.0 Source: https://commons.wikimedia.org/w/index.php?curid=2564777
The energy business can be incredibly lucrative. Whether it’s the vast multitude of electronics, houses that continue to get larger, or electric cars, being in the energy-producing business can mean significant returns and incredibly generous dividends. But energy production tends to come with an environmental footprint, which some investors find bothersome.
Brookfield Renewable Partners LP (TSX: BEP.UN)(NYSE: BEP) provides investors with an incredibly generous ~6% yield, while generating all of its electricity from renewable sources. Said another way, Brookfield Renewable lets you have your cake and eat it too.
Brookfield Renewable is one of a few spin-offs from Brookfield Asset Management Inc. When Brookfield Asset accumulates enough investments in a specific asset class, it spins them out to be focused on that type of investment.
At a high level, Brookfield Renewable is a hydroelectric company with over 80% of its power generation in that water. The reason is pretty clear: there aren’t many sources that can generate as much bulk energy as the natural flow of water. However, that doesn’t mean that the company doesn’t own other types of well-known renewable sources.
For example, Brookfield Renewable acquired the Bord Gais wind farm in an Irish government sale, which added 320 MW of power to the portfolio. In total, the company has over 1,400 MW of wind power, providing power to more than 300,000 homes across North America, South America, and Europe.
But the big news, in my opinion, is its recent expansion into the solar business. You wouldn’t think it, considering how much press solar gets, but up until recently, Brookfield Renewable didn’t have any significant investment in solar power.
Management didn’t see a value investment whereby the company could buy assets for cheap, organically invest in them, boost funds from operations, and then potentially sell them for major returns on investment. Wind and hydro had those opportunities, but solar was still too much of an uncertainty.
That changed with the recent takeover of TerraForm Global and the 51% acquisition of TerraForm Power Inc. Brookfield Renewable invested $230 million into the total $750 million price tag, giving it 31% of the business. This adds 952 MW to its portfolio with long-term contracts stretching out 17 years.
Management expects that the investment will contribute $35 million of annual funds from operations on a run-rate basis. Ultimately, this is what we’re looking for, because Brookfield is, in my eyes, one of the best dividend stocks on the market for those that want exposure to energy production.
Brookfield Renewable currently yields 5.8%, but with any pullback, that’ll jump to over 6% easily. Between natural appreciation and dividend growth, management expects to generate anywhere from 12% to 15% over the long run. With its ability to acquire high-quality assets that kick off cash flow, I see little reason why management won’t be able to achieve this.
My stance on Brookfield Renewable has been consistent since the start. It’s a high-quality business run by exceptional investors. It buys cheap assets, invests in them, boosts cash flow, and then if it becomes overvalued, recycles the money. I believe investors would be wise to own this stock.







