


Canadian oil stocks are under considerable pressure. Key benchmark oil prices, including Brent and West Texas Intermediate (WTI), continue to languish at around US$36 and US$34 per barrel. While many Canadian oil stocks are un-investable in the current harsh operating environment, it has created the opportunity to acquire quality drillers at a once-in-a-generation low.
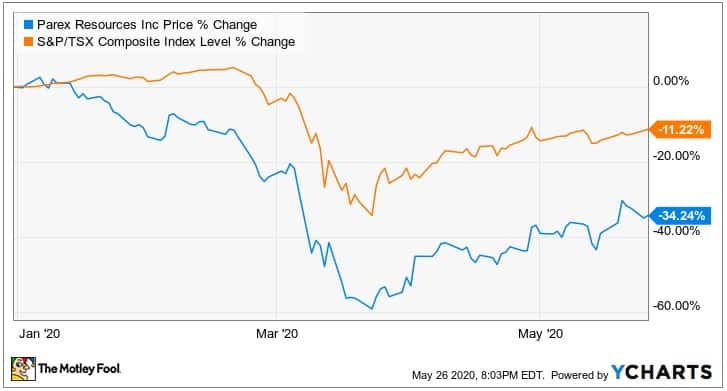
One oil stock that stands out is Parex Resources (TSX: PXT). The driller was my top energy pick for 2019 and returned almost 45% that year. After losing 34% since the start of 2020, I think Parex offers extremely attractive value.
This, combined with a range of factors including quality assets and a debt-free balance sheet, makes now the time to buy.
This oil stock is on sale
Parex is trading at a considerable discount to the net asset value of its proven and probable oil reserves. According to Parex’s 2019 reserves report, its proven and probable oil reserves have an after-tax net present value (NPV) of almost $3.6 billion.
After deducting long-term liabilities, including reclamation costs, leases, and tax obligations plus adding cash, Parex has an after-tax net asset value (NAV) of $3.9 billion.
This gives Parex a NAV of $37.14 which is more than double its current share price. That highlights the considerable capital gains ahead if you buy today.
Parex’s NAV was calculated using an assumed Brent price of US$70 which is roughly double the current spot price. While that indicates there maybe less upside available for investors, especially if oil prices remain weak for a protracted period, the risk/reward equation is clearly in favour of investors.
Favourable outlook
It isn’t difficult to see Parex outperforming the TSX once again in 2020 and delivering sizeable returns. Since the market bottomed in the March 2020 stock market crash, Parex has risen a whopping 61% compared to the S&P/TSX Composite’s 34% increase.
Parex possesses a range of strengths that will see it deliver considerable long-term value. It finished the first quarter 2020 with a rock-solid balance sheet, described as best in class. Parex is free of debt and reported US$397 million in cash at the end of the first quarter. This gives Parex considerable financial flexibility at a crucial time. That notable liquidity is boosted by Parex’s undrawn US$200 million credit facility.
Despite the oil price collapse, Parex generated an impressive average operating netback for the first quarter of US$24.21 per barrel sold. This highlights the considerable profitability and quality of Parex’s oil assets during a difficult time for the petroleum industry. Parex’s focus on reducing costs by shuttering uneconomic production, suspending non-crucial activities, and reducing costs will see expenses fall further.
The Colombian government, under intense pressure from private oil producers, will reduce pipeline tariffs. That will provide some relief to a deeply embattled oil patch by reducing transportation costs. This initative will support Parex’s credible netback and earnings.
Nevertheless, a combination of sharply weaker oil and lower production will cause Parex’s second-quarter 2020 earnings to soften. That shouldn’t deter you from investing.
Foolish takeaway
Parex remains a best in class intermediate upstream oil producers. A rock-solid balance sheet, low operating expenses and ability to access premium Brent pricing makes Parex a compelling investment. When combined with the share trading at a deep discount to its NAV, it is clear that it will deliver considerable value over the long term. For these reasons, now is the time to buy.







