


Canadian oil stocks are under considerable pressure. Oil’s sharp collapse, which saw West Texas Intermediate (WTI) plunge into negative territory for the first time ever, is hitting the energy patch hard. While the immediate outlook remains gloomy, this has created an opportunity to acquire quality drillers at once in a generation prices.
One oil stock that stands out is Frontera Energy (TSX: FEC). The driller, which emerged from the bankruptcy of Pacific Exploration and Production, has lost 64% since the start of 2020. This is significantly greater than the 55% decline of the international Brent benchmark price.
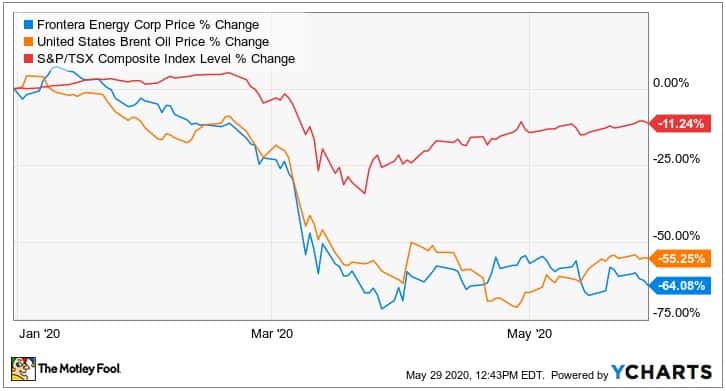
While there are plenty of headwinds ahead, there are signs that Frontera is very attractively valued, making it a speculative buy for contrarian investors betting on higher oil.
Why invest in oil stocks?
A key advantage of investing in oil companies rather than oil is their levered exposure to the price of crude. This means that when oil plunge their price decline, like Frontera’s, typically exceeds that of benchmark oil prices.
Conversely, when oil rallies it means they generally experience far greater gains than oil, meaning they can deliver outsized returns to investors.
Key is identifying those upstream oil producers that possess quality assets and strong fundamentals, allowing them to weather the current crisis.
Quality oil portfolio
Frontera owns a diversified quality portfolio of oil assets across South America, with its main producing acreage located in Colombia. This not only gives Frontera a handy financial advantage by allowing it to access Brent pricing, which trades at a premium to WTI, but benefit from lower operating expenses.
As a result, Frontera reported a credible first-quarter 2020 operating netback of US$16.21 per barrel of oil sold. The driller’s ongoing push to reduce operational costs and shutter non-economic production will keep its operations cash flow positive. That will be aided by Colombian government initiatives to reduce pipeline transportation costs.
Solid fundamentals for an oil stock
One of Frontera’s key strengths is its considerable liquidity and solid balance sheet. It finished the first quarter with US$265 million in cash and another US$30 million of restricted cash. This gives Frontera considerable financial flexibility, positioning it to emerge from the latest crisis relatively unscathed.
Importantly, Frontera has a very manageable US$364 million of long-term debt and lease liabilities. There are no debt repayments due until 2023, giving Frontera considerable breathing space to overcome the current crisis.
What makes Frontera a top oil stock to buy (aside from its solid balance sheet and quality assets) is that its shares are on sale. The driller is trading at a deep discount to the after-tax net asset value of its proven and probably oil reserves.
At the time of writing, Frontera’s price of $3.55 per share is less than a third of its $11 per share after-tax net asset value. This highlights the considerable potential upside available when oil firms and Frontera’s stock rallies.
Foolish takeaway
Frontera has long failed to unlock value from its oil assets. Finally, toward the end of 2019 it had resolved many of its legacy issues and was on track to reward investors, but this was derailed by the latest oil price collapse and coronavirus pandemic.
Nonetheless, Frontera will survive the current crisis. As oil prices rally higher, it will deliver considerable value for shareholders during the second half of 2020.







