


Natural gas stocks are under considerable pressure. The fossil fuel has lost 21% for the year to date, placing significant pressure on natural gas producers, which have been bleeding red ink during the fuel’s protracted price slump.
One Canadian natural gas stock that’s resistant to the poor economic outlook and the fossil fuels protracted slump is Canacol (TSX: CNE). The driller, which is focused on onshore natural gas production in Colombia, is down just over 21% for the year to date.
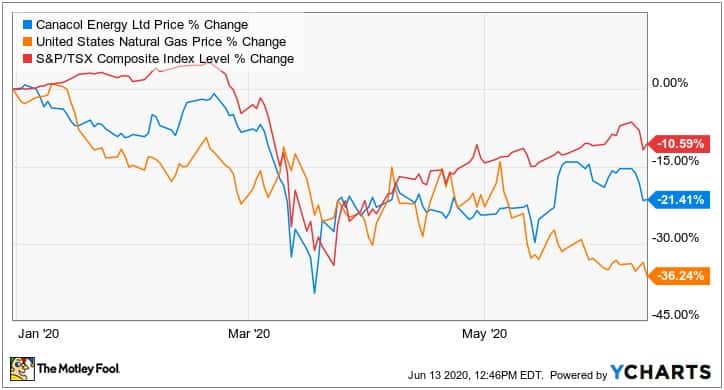
That’s roughly double the S&P/TSX Composite’s 11% decline and indicates that it’s attractively valued. The latest news from Canacol indicates that not only will earnings grow strongly once the economy returns to growth, but sales are returning to normal far earlier than expected.
Natural gas sales recovering
Canacol announced last week that interruptible natural gas sales were returning at a faster rate than expected despite Colombia’s ongoing coronavirus lockdown. For May 2020, sales on average reached 181 million standard cubic feet of natural gas per day (MMSCFD), which was 16% higher than a month earlier. That notable uptick in sales bodes well for Canacol’s earnings.
Impressively, that’s within Canacol’s revised 2020 guidance, when it forecast natural gas sales of 170 to 197 MMSCFD.
Secured higher than benchmark natural gas prices
Notably, because of Colombia’s energy crisis, Canacol has been able to establish take or pay contracts for the natural gas it sells at prices far higher than the North American Henry Hub benchmark. The driller has locked in an average price net of transportation costs of US$4.80 per million cubic feet (MCF) sold for 80% of the natural gas it produces.
That price is almost triple the Henry Hub benchmark.
In fact, for the first quarter, Canacol received an average price net of transport costs of US$4.54 per MCF. That saw it earn an operating netback of US$3.60 per MCF which was significantly higher than North American drillers.
Notably, to date there have been no defaults for Canacol’s contracted natural gas sales, which underscores the considerable profitability created by Colombia’s long-term natural gas supply deficit.
Unique natural gas market
A dearth of major petroleum discoveries, loss of Venezuelan imports and aging high decline rate of offshore natural gas fields means a shortfall for the foreseeable future. Demand for the fossil fuel in Colombia will grow significantly over the long term.
Low water levels have impacted Colombia’s electricity supply, which has led to an increased reliance upon natural gas fired power generation.
When those factors are combined with growing industrial and residential demand over the long term, fuel consumption will continue growing — and magnify the supply shortage.
Rewarding shareholders
The contracted nature of Canacol’s sales coupled with Colombia’s emerging energy crisis make its earnings highly dependable. For that reason, Canacol commenced dividend payments in 2019 as a means of rewarding loyal shareholders.
Despite the coronavirus pandemic, weaker North American natural gas prices and poor economic outlook, Canacol has announced that it has no intention of reducing the payment. The dividend, which is yielding a very juicy 5.7% after Canacol’s latest price decline, appears sustainable.
That will be enhanced by higher earnings over the remainder of 2020 combined with Canacol’s moves to reduce debt to a more manageable 1.3 times EBITDAX by the end of 2020.
Foolish takeaway
Canacol will perform regardless of sharply weaker North American natural gas prices. The unique dynamics of Colombia’s energy market coupled with the highly contracted nature of Canacol’s earnings provide it with considerable financial certainty.
Growing sales in Colombia and improved access to markets will boost earnings over the long term. Given that Canacol is trading at less than half of its after-tax net asset value, now’s the time to invest.







