


Retail investors often try to follow “smart money” when deciding what to do with their investment portfolios. This means, they look to big hedge fund managers and follow in their decision making. Investors that practice this method of investing often name Warren Buffett as one of the fund managers they look to the most.
In his latest 13F filing, it was evident that there were companies Warren Buffett wanted to trim significantly from Berkshire Hathaway’s portfolio. In this article, I will discuss two such companies.
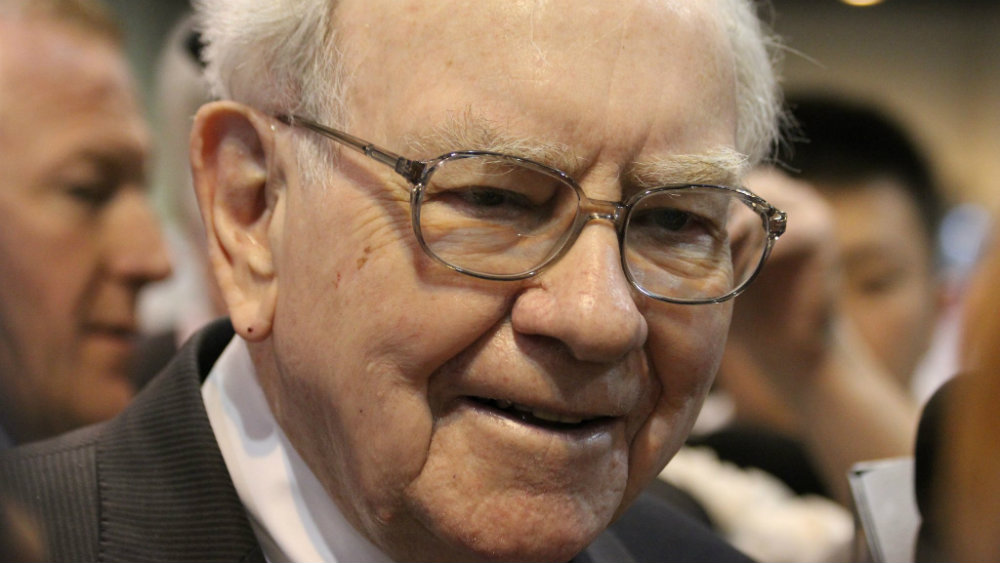
Image source: The Motley Fool
Buffett loves banks, but not this one?
The third-largest cut that Warren Buffett made over the past quarter was a 46.38% reduction in Berkshire’s position in Well Fargo (NYSE: WFC). Although the Oracle of Omaha cut his Wells Fargo position by nearly half its size, the company remains the 10th-largest holding in Berkshire Hathaway’s portfolio. Currently, Buffett holds about $3 billion worth of Wells Fargo stock.
As of June 2020, Wells Fargo is the fourth-largest American bank by assets. In terms of market cap, the bank was the third largest in the United States. Indeed, it is evident that Wells Fargo is a giant within the American financial sector. However, the company has had a rocky past. In 2016, news broke of Wells Fargo’s account fraud scandal. The company has since been trying to repair its public image, and a strong position in Warren Buffett’s portfolio was a good indication of investor sentiment.
This year, Wells Fargo stock has struggled significantly. As of this writing, the company is trading more than 45% lower than it did at the start of the year. Unlike its peers, which have seen slow recoveries since March, Wells Fargo hit its lowest point in late October this year. It is unclear whether the company will see its fortunes improve before the end of 2020, but what is clear is that Warren Buffett felt very strongly about reducing his exposure to the company.
Of course, Wells Fargo is not a Canadian bank. However, this cut is still noteworthy. Warren Buffett also made cuts to his JP Morgan position, another well-known American banking company. Investors holding Canadian banking stocks should take a look at their portfolios and assess whether their positions are exposed to more downside.
No time for gold in a bull market
During times of uncertainty, investors often flock to commodities such as gold. One reason for this is that gold does not lose its value. Therefore, investors will use it as a hedge against threats such as inflation. However, during bull markets, it could be better to hold your capital in different asset classes. Personally, I am not a big proponent of gold and other commodities. However, among the different gold mining companies, I believe Barrick Gold (TSX: ABX)(NYSE: GOLD) stands atop its peers.
Over the past quarter, Barrick Gold represented Warren Buffett’s fourth-biggest reduction. In Berkshire Hathaway’s Q3 13F filing, it was reported that the company’s stake in Barrick Gold was cut by 42.64%. Currently, Barrick Gold represents 0.15% of Warren Buffett’s portfolio, with a position size of about $337 million.
Year to date, Barrick Gold stock has been quite volatile. The company saw its value peak in April and May amid coronavirus uncertainty but has since fallen nearly 25% from those levels. With the economy seemingly back on its feet, gold mining companies may have a difficult time attracting investors. A component of the S&P/TSX 60, Barrick Gold remains one of the top companies in Canada.
Foolish takeaway
Warren Buffett is a fund manager that retail investors often look to, when making decisions on their own portfolios. Over the past quarter, Buffett made significant cuts to his Wells Fargo and Barrick Gold positions. As the economy recovers, it may be argued that better opportunities may arise elsewhere. Canadians that like to follow “smart money” should definitely take note of these big changes to Berkshire Hathaway’s portfolio.







