


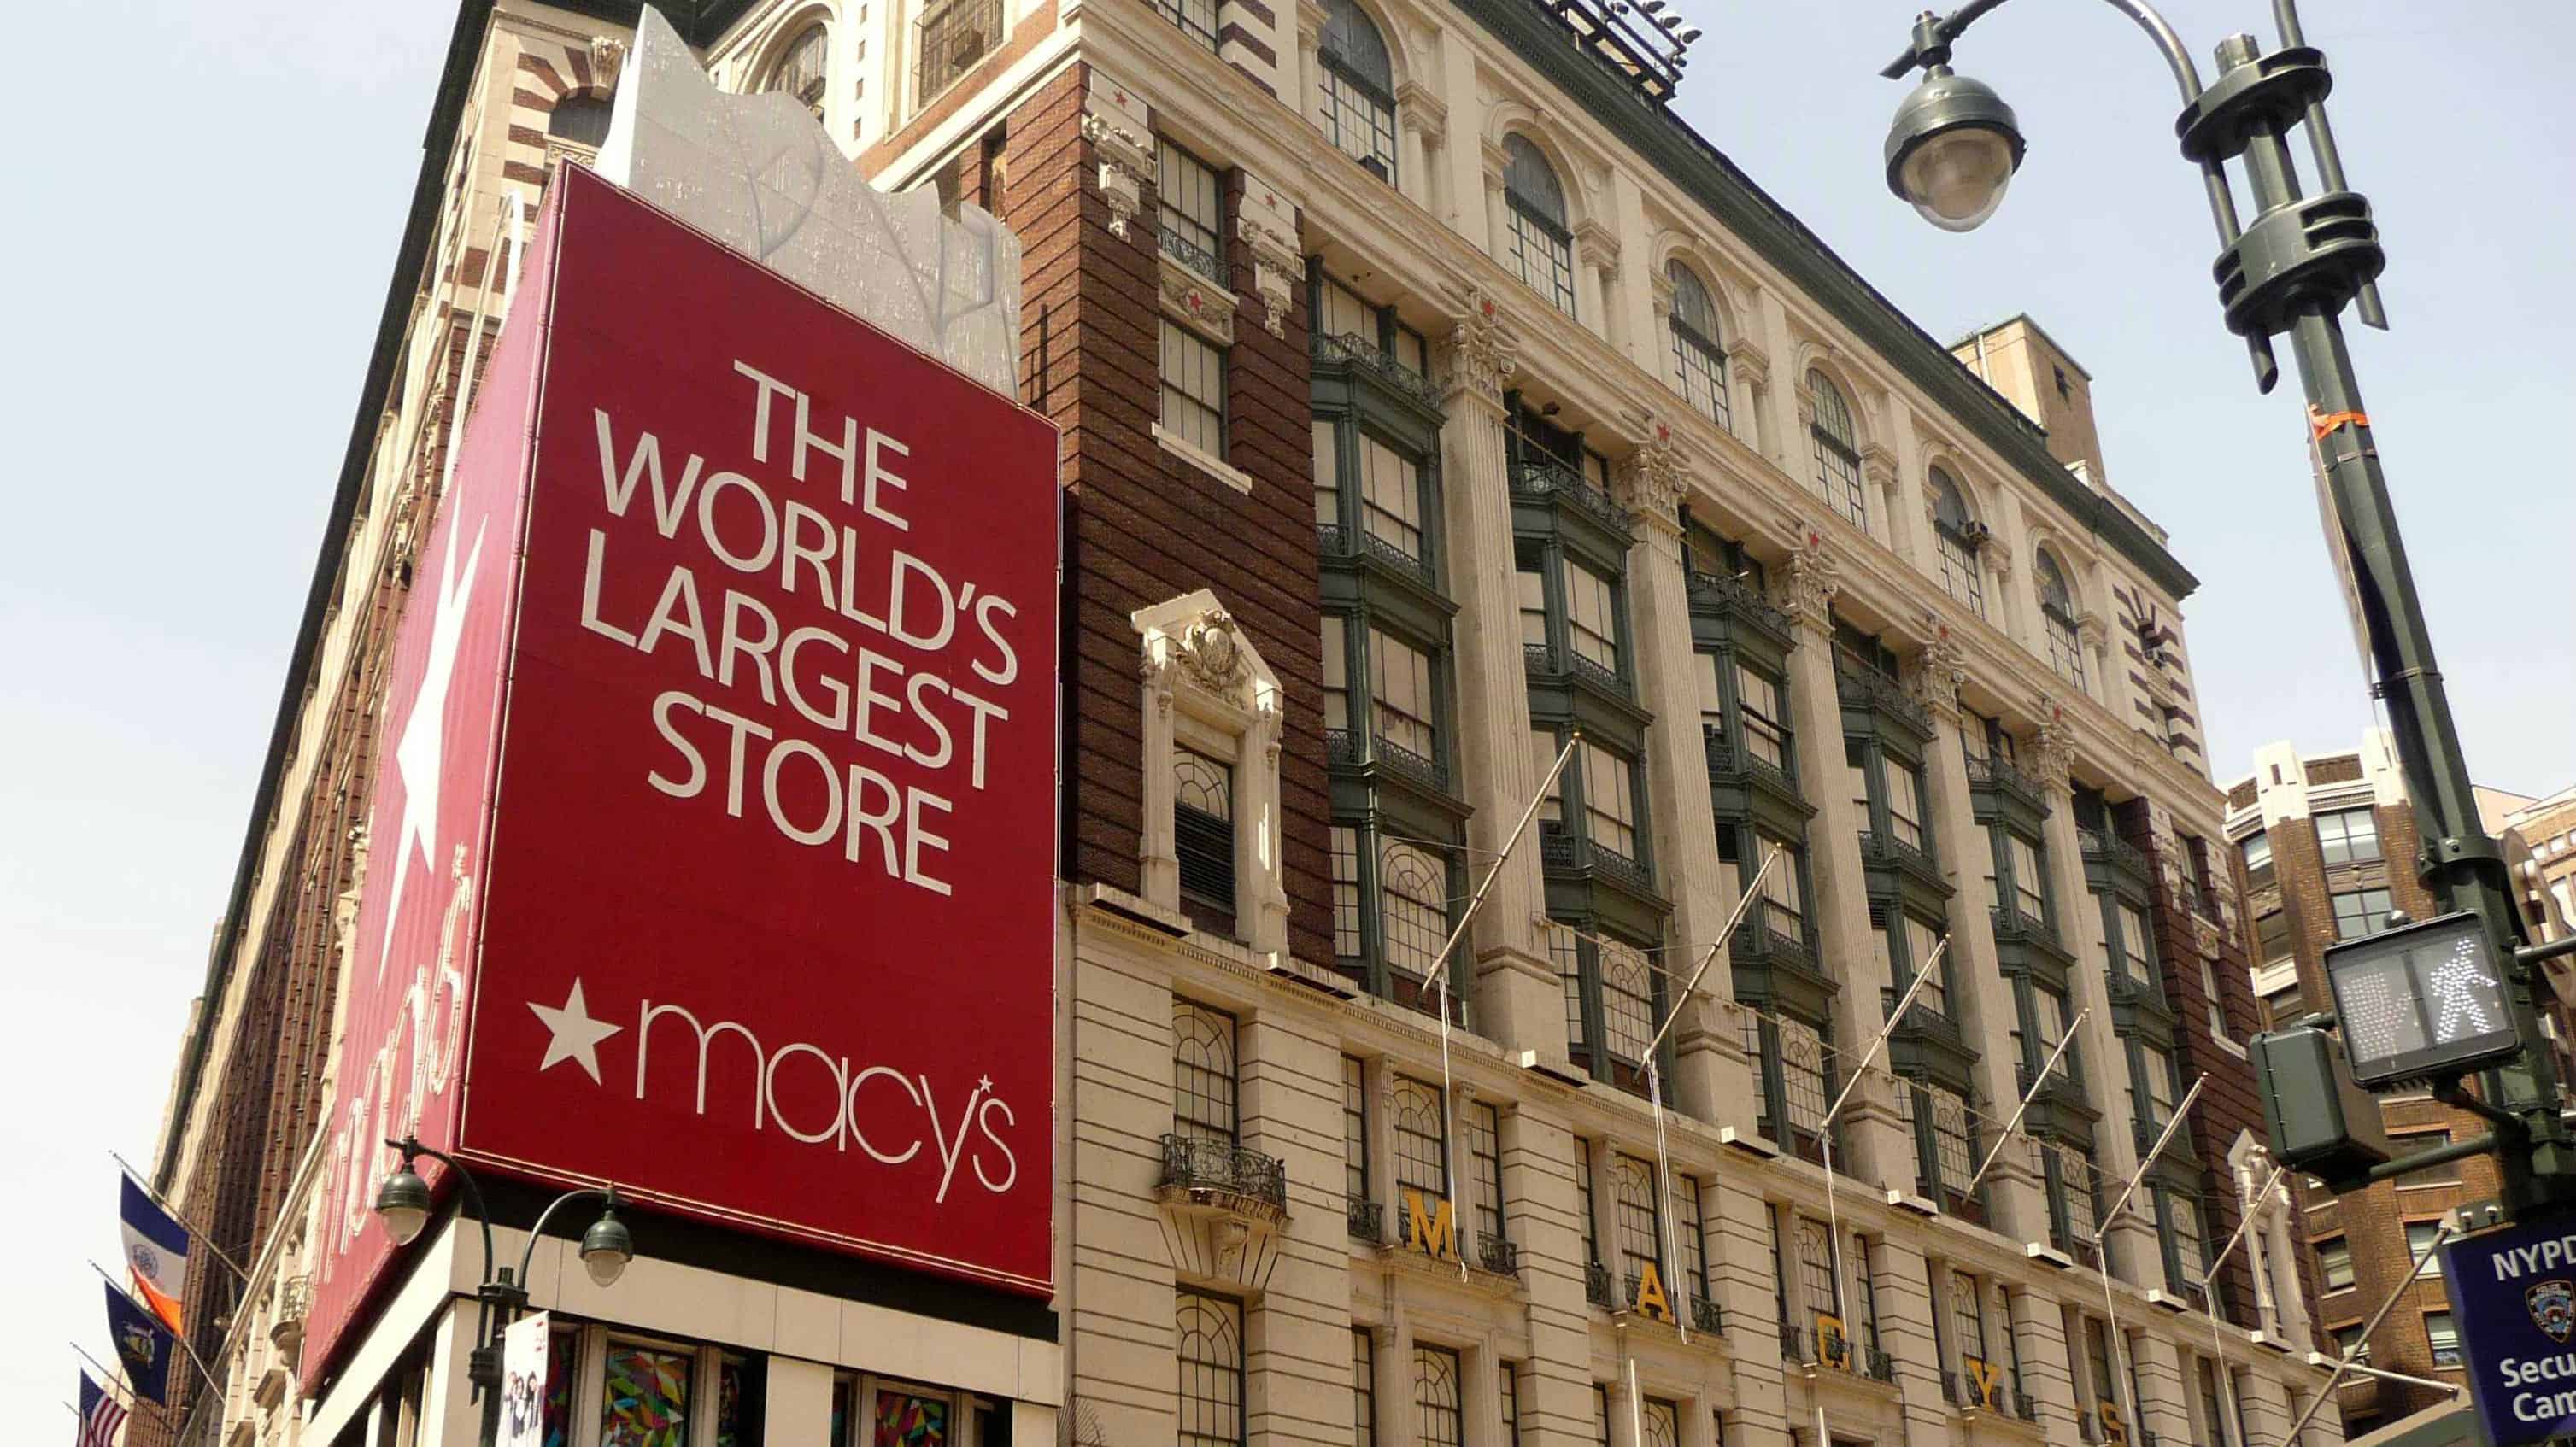
Last month, we revealed that Hudson’s Bay Co. (TSX:HBC) was considering acquiring Macy’s Inc. (NYSE: M), a company more than five times its size. We realized this deal wasn’t so much about expanding its retail operations, but rather it was a play at acquiring Macy’s lucrative portfolio of real estate.
According to Starboard Value, an activist investor, the real value for Macy’s is in the projected US$21 billion in real estate it holds. This doesn’t take into consideration the enterprise value, which, at the time Starboard Value made its proposal, was US$35 per share. And if we look at how Hudson’s Bay has operated previously, it’s clear that this was the real goal.
It all starts with the company that acquired HBC back in July 2008: NRDC Equity Partners. This is a retail and real estate investment firm which had already owned the Lord & Taylor brand. Through this acquisition, it became a serious retail powerhouse. But then things got even more intense when NRDC Equity Partners paid US$2.9 billion, through Hudson’s Bay, to acquire Saks, Inc. in 2013, the holding corporation of the Saks Fifth Avenue flagship store, plus the OFF 5th brands.
Originally, investors thought the company had paid far too much for it, but in November 2014, Hudson’s Bay proved them all wrong by taking out a mortgage against the flagship store. The mortgage valued the single location at US$3.7 billion. In the span of about 18 months, the company increased the value of its acquisition by US$800 million. And that wasn’t even taking into consideration the OFF 5th brands.
But here’s the problem that Hudson’s Bay is running into now…
The company is having trouble pulling together the financing to actually make an acquisition. Remember, Hudson’s Bay only has a market cap of $2.17 billion, but it’s trying to buy a company that is far larger than it. This puts it in a difficult position because it doesn’t have that much wiggle room. And Macy’s obviously understands the value of its assets, so it’s likely asking for far more than its current market cap of US$10 billion.
I like the idea of this acquisition, but it seems highly unlikely that it’ll actually go through. Therefore, investors need to determine if they should own this stock. And unfortunately, I remain unconvinced that Hudson’s Bay is a smart buy at this time because its sales continue to decline. In September, the company suggested it would have $15.9 billion in sales. Two months later, that had dropped by a billion. And by the end of 2016, Hudson’s Bay was anticipating $14.4 billion in sales.
We won’t know until next month what the true sales are for the full year, but when a company continues to cut its guidance every couple of months, it doesn’t seem like it’s going to have a particularly strong quarter. So, at this point, I would be sitting on the sidelines. As a real estate play, it is very interesting; however, there are far more lucrative, pure-play real estate stocks to own. I would focus on those.







