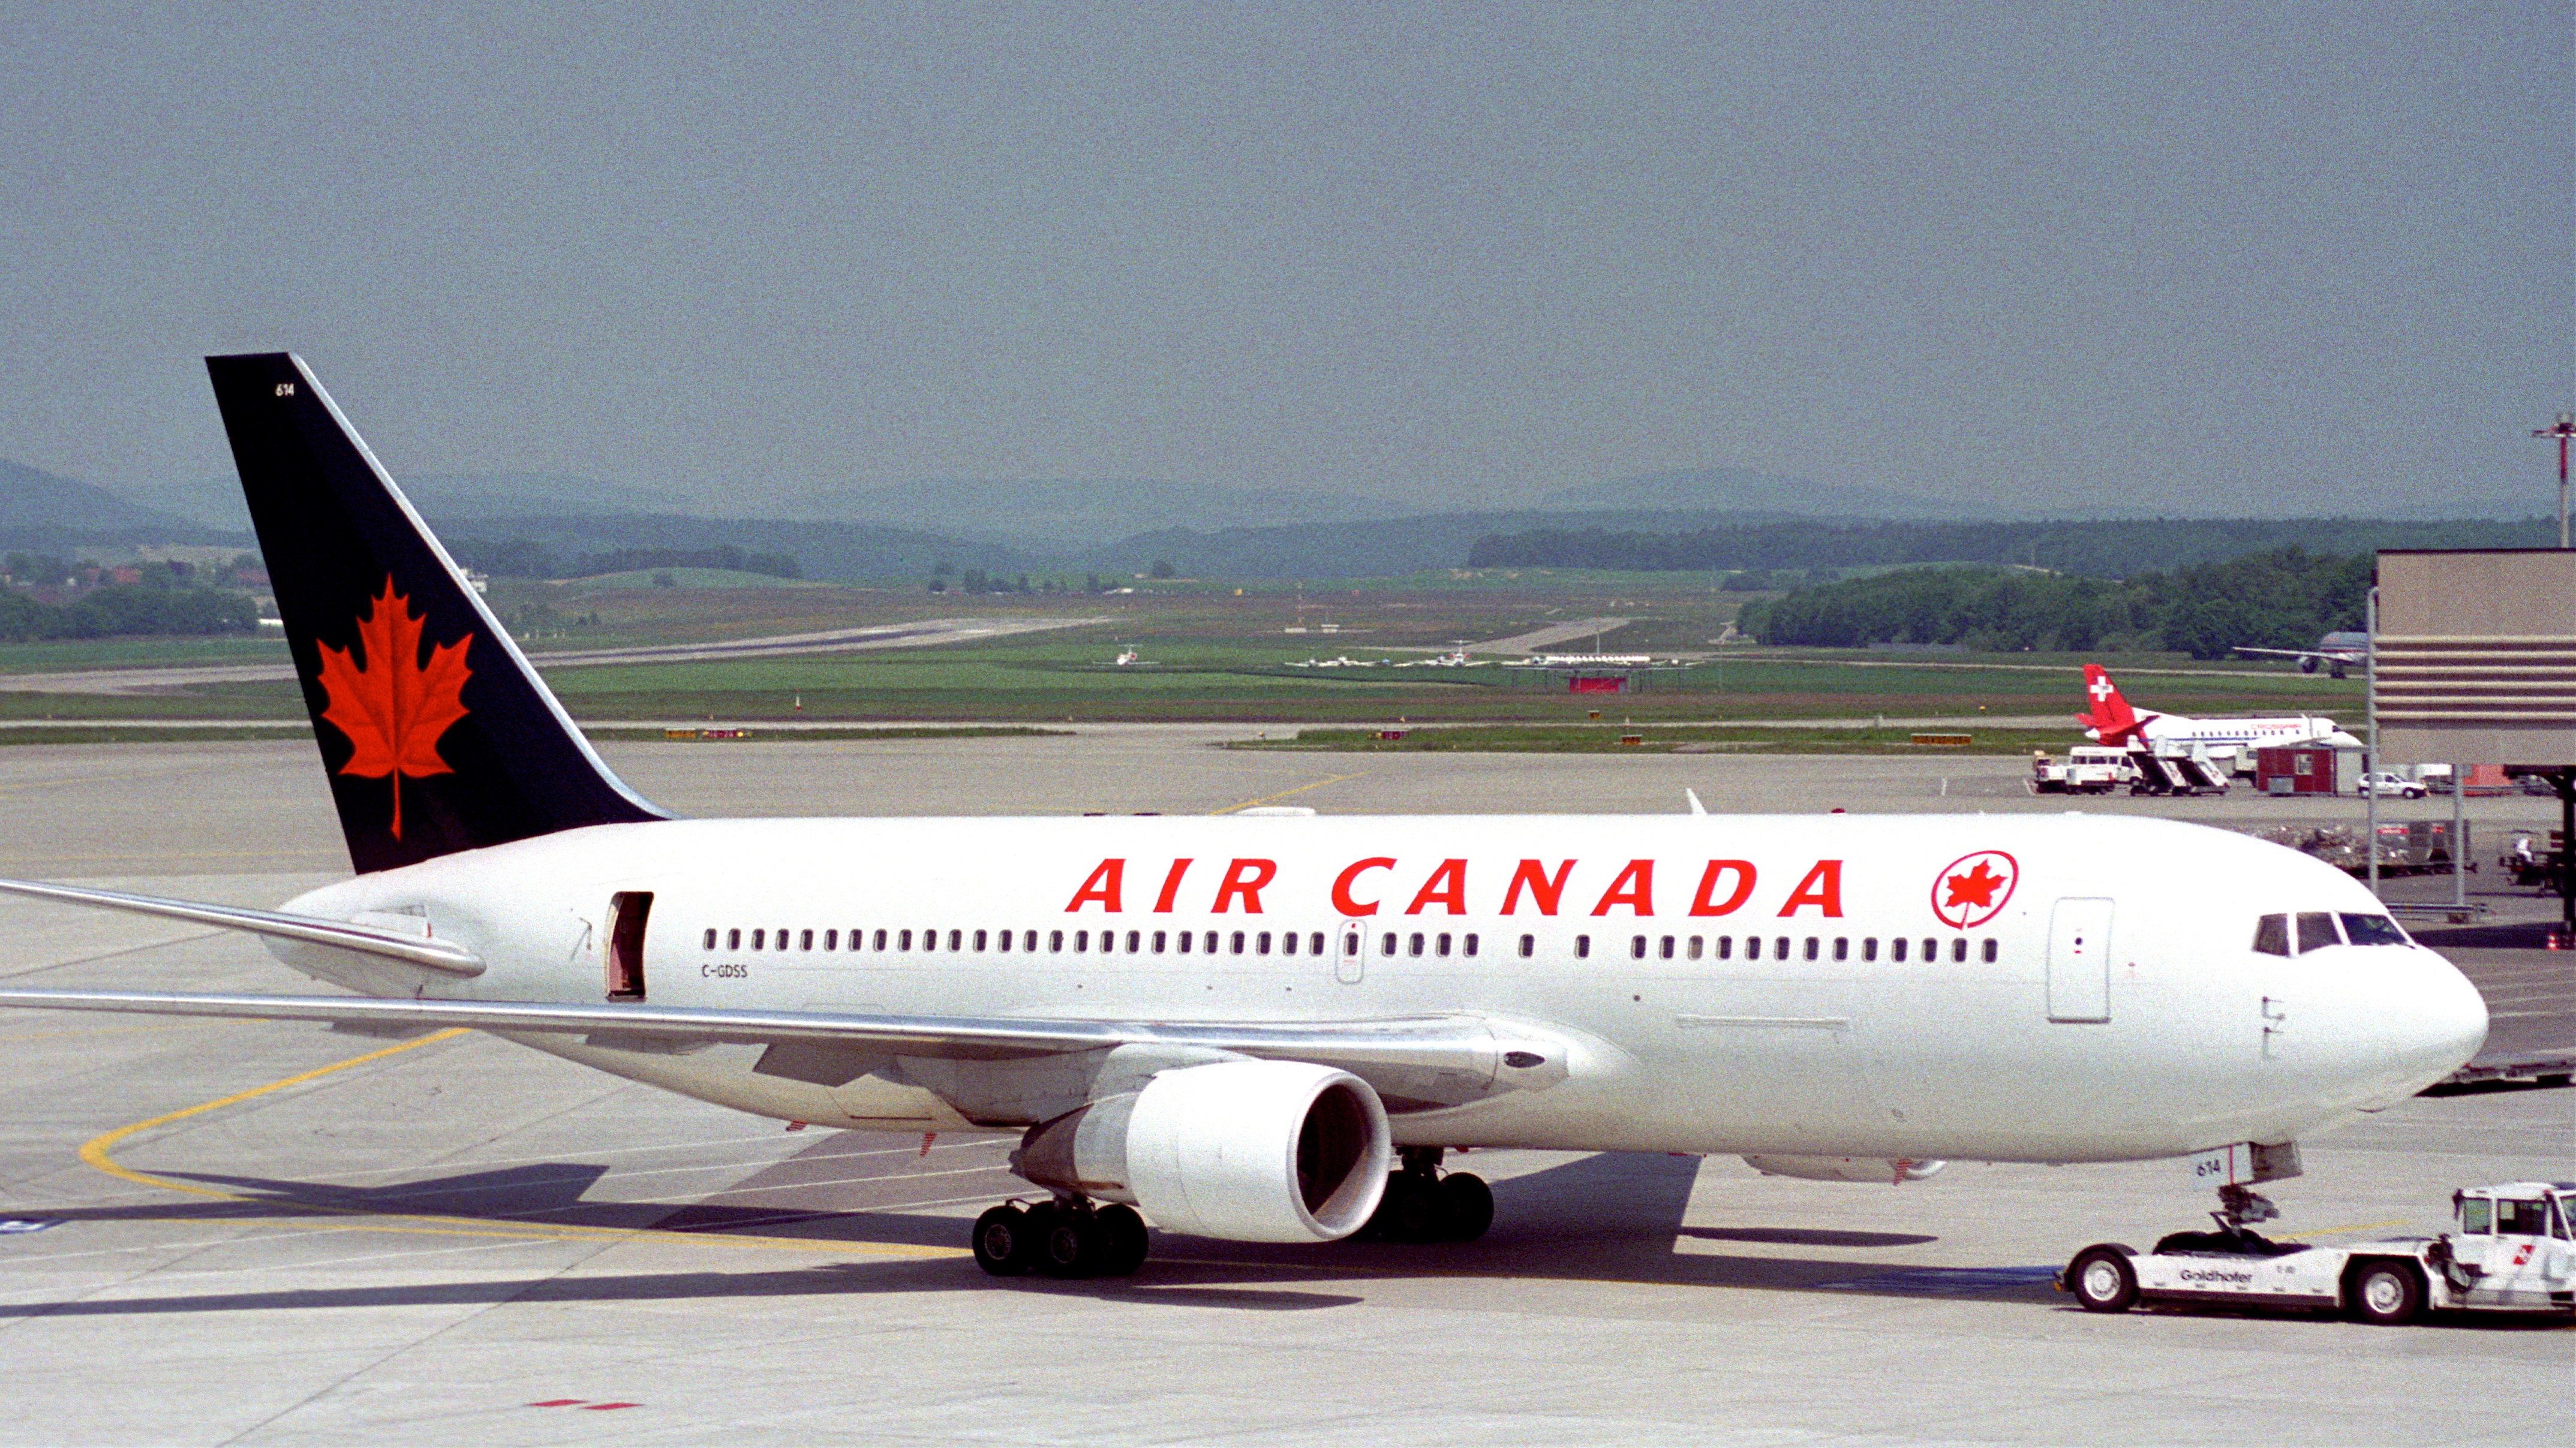
The idea that a company which has taken off and climbed more than 150% over the past 12 months and 65% year to date has just started its ascent may seem normal when talking about a technology or pharmaceutical company; however, when thinking about a company such as Air Canada (TSX: AC)(TSX:AC.B), most investors would consider such a growth rate nearly impossible.
As it so happens, the airline industry in North America has seen an explosion in recent years, spurred by renewed interest from investors who vowed never again to step into the highly cyclical industry. Investors such as Warren Buffett, who have long considered the industry to be a deathtrap, have invested billions into North American airlines, buying into the thesis that this industry is now able to churn out profitable growth.
That said, a doubling of the company’s current stock price approaching $23 per share might seem a tad overzealous, even for the most aggressive, bullish investor in a company like Air Canada. Here’s why I think Air Canada has a shot to become an excellent long-term growth play and achieve such a target.
A long-term play
First of all, I should clarify that when I suggest Air Canada could double from current levels, I am speaking with a long-term perspective. Of course, any company can double (and should double) in the long term, lest an investor miss out on a better opportunity available elsewhere. That said, I believe the timeline for such an appreciation in Air Canada’s share price may not take decades, but rather years, and investors who may believe that the current meteoric rise in Air Canada’s share price makes the company overvalued are missing the longer-term story.
Industry-wide growth and profitability likely to continue
Air travel is widely considered to be one of the least-elastic forms of consumption. In general, if a person wants to get from point A to point B, and point B happens to be several hundred or thousands of kilometres away, air travel really is the only way to go.
Air Canada remains the largest airline in Canada with a dominant market position which has generally been protected by the Canadian government. Recent moves by management to improve the company’s loyalty program, invest heavily in capacity purchase agreements with smaller regional carriers, and new computer systems and technology, and the vision of the management team to boost profitability by moving towards having a narrow-body fleet of airplanes are all factors likely to continue to contribute to the airline’s improving profitability.
Bottom line
The impression I get with a company like Air Canada is that many investors simply do not like the fact that Air Canada’s management team has simply flubbed up the party in the past. As such, Air Canada continues to trade at a discount to its peers.
I would continue to chip away at Air Canada on any dips that may occur in the coming quarters and years. After all, investing is a long-term game.
Stay Foolish, my friends.