From the start of 2017, Katanga Mining Ltd. (TSX:KAT) stock has appreciated as much as 15 times when it hit a peak of ~$2.50 per share! The company has the potential to become Africa’s largest copper producer and the world’s largest cobalt producer.
Cobalt is what investors are interested in, as it is an essential element for batteries in electric cars. And there’s a long runway for the conversion to electric cars. Nevertheless, it’s helpful to the company that copper prices have rebounded 50% from the 2016 low.
However, due to the news that came out in late April that Gécamines has started legal proceedings to dissolve its joint venture with Katanga because of a previously disclosed capital deficiency, Katanga’s share price has fallen ~46%. Should you buy Katanga now? Before discussing further, it’s appropriate to first give an overview of the business.
An overview of Katanga
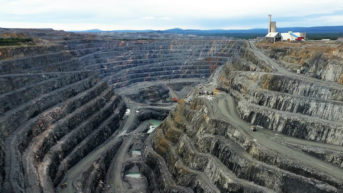
As described on the company website, Katanga “operates a large-scale copper-cobalt project with substantial high-grade mineral reserves and integrated metallurgical operations in the Democratic Republic of Congo (DRC).” The single-site operation consists of brownfield assets and new facilities that are under construction.
Katanga has a 75% interest in Kamoto Copper Company, a joint venture with Gécamines a state-owned mining company in the DRC that has the remaining interest in the joint venture.
Notably, Katanga’s largest shareholder, the Swiss-based mining giant Glencore PLC, owns ~86% of Katanga.
Should Katanga investors feel secure because of Glencore?
Not only does Glencore have a controlling interest in Katanga, but it is also Katanga’s principal creditor. Additionally, three of Katanga’s directors (out of the seven members on the board) are employed by Glencore. So, Glencore essentially controls the company.
Some investors may think that Katanga is a safe company to invest in because it’s backed by Glencore. However, in another perspective, if worse comes to worst, Glencore can survive by booking a loss on Katanga, but Katanga probably won’t survive if Glencore cuts its ties with it.
Investor takeaway
Conservative investors should avoid Katanga. There’s a lot of risk in investing in a company that has a single-site operation. Moreover, Katanga has more debt than it does assets. And the latest drama doesn’t help in adding reassurance.
If you are bullish on electric cars, and you’ve been eyeing Katanga for an entry point, the recent quotation of under $1 per share is a good entry point to begin scaling in. However, don’t bet the farm on the stock.