


Global installed capacity of renewable sources of electricity is expanding at a solid clip. International Renewable Energy Agency (IRENA) data shows that in 2019 global installed renewable electricity capacity expanded by 7.6% year over year. Notably, it made up 75% of all new electricity capacity installed across the world last year.
The ongoing push to reduce carbon emissions and prevent climate change is gaining significant momentum and is key driver for the rapid adoption of renewable energy.
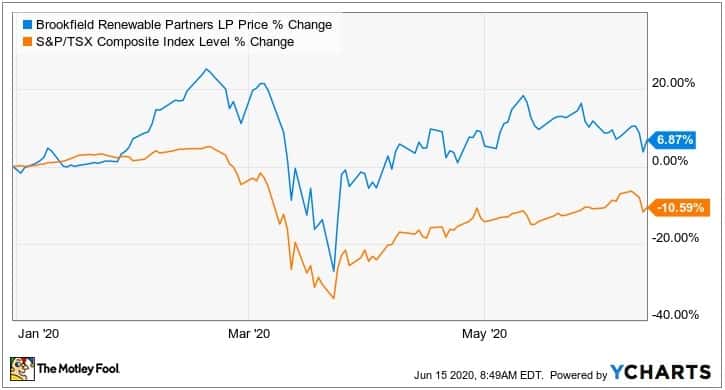
One Canadian stock poised to benefit from this secular trend and deliver considerable value for investors is Brookfield Renewable Partners (TSX: BEP.UN)(NYSE: BEP). After struggling for years to unlock value from its globally diversified portfolio of clean energy assets Brookfield Renewable is finally delivering solid results. This saw the renewable energy utility defy the coronavirus pandemic and March 2020 stock market crash; it’s up by 7% for the year to date compared to the S&P/TSX Composite losing almost 11%.
There are signs of further solid results ahead, making now the time to buy Brookfield Renewable.
Diversified renewable electricity assets
Brookfield Renewable owns a globally diversified portfolio located across the Americas, Asia, and Western Europe with 19,300 megawatts of installed capacity. Notably, 74% of that capacity is derived from hydroelectricity with the remainder coming from wind and solar facilities.
It was Brookfield Renewable’s considerable reliance upon hydro that was responsible for its inability to unlock significant value from its portfolio. Poor hydrology in the Americas, notably in South America, was weighing on electricity production.
For the first quarter 2020, Brookfield Renewable’s portfolio generated 14,264 gigawatt hours (GWH) of electricity, which was 1% greater than a year earlier. Disappointingly, Brookfield Renewable’s proportionate adjusted EBITDA softened 1% year over year, and funds from operations (FFO) declined by 4%.
As a result, the renewable energy stock’s quarterly net income plunged 58% to US$18 million.
Solid defensive characteristics
Those numbers shouldn’t prevent you from adding Brookfield Renewable to your portfolio. The partnership’s earnings are secure and certain.
It possesses the defensive characteristics of traditional electricity utilities, such as steep barriers to entry and a wide economic moat, which protect it from competition. Those are strengthened by the unchanging demand for electricity, which is an important source of energy, which powers our modern lives and economy.
Brookfield Renewable has contracted 95% of its cash flows through inflation-linked power-purchase agreements. That further enhances their certainty.
Positioned for growth
The partnership’s earnings are poised to grow at a solid clip. Brookfield Renewable has a portfolio of eight facilities under construction, which will add 831 MW to its installed capacity on completion. Those facilities will be completed between now and the first half of 2020. The partnership expects them to boost FFO by around US$21 million.
Brookfield Renewable finished the first quarter with a robust balance sheet. This included US$294 million in cash and total available liquidity of around US$3 billion. While the partnership does have a massive pile of debt totalling US$9.6 billion, there are no material debt repayments for the next four years. That pile of debt is still only 6.7 times EBITDA, which is a relatively low ratio for an electric utility.
Brookfield Renewable also has access to the considerable capital of Brookfield Asset Management, further reducing the risks associated with that debt.
The partnership’s considerable liquidity means it is well positioned to continue making opportunistic acquisitions of quality renewable energy assets, which will boost electricity production and earnings.
Brookfield Renewable is also undertaking a recontracting initiative where it is seeking to establish new contracts for the electricity it produces at more favourable prices. That will continue to lift margins and boost profitability over the long term.
Foolish takeaway
There are considerable tailwinds ahead for renewable energy stocks, including the secular trend to cleaner energy. These will propel their earnings higher, as the world transitions away from fossil fuel-powered electricity production. Brookfield Renewable is among the best positioned to benefit because of its large, high-quality, globally diversified portfolio of renewable assets.
While waiting for its earnings to grow, unitholders will be rewarded by its sustainable distribution, which, after being hiked for 10 years straight, is yielding 4.6%.







