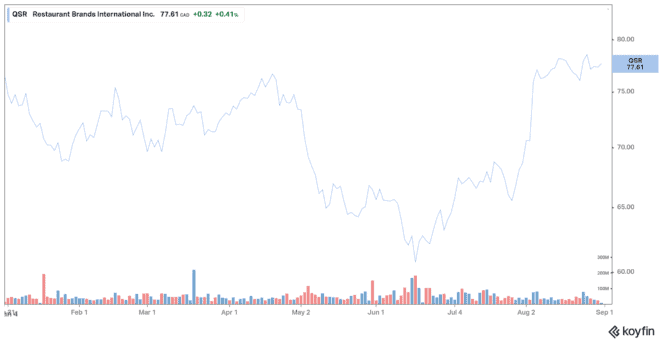
Restaurant Brands International’s (TSX: QSR)(NYSE: QSR) business is outperforming. The fast food operator produced a quadruple whopper across its restaurant chains. The dramatic uptrend in sales – driven by Tim Hortons’ continued momentum, Burger King International’s return to solid pre-pandemic growth, Burger King U.S.’s rebound to same-store sales growth, and Popeyes’ domestic and global sales – is encouraging.
Management believes the company’s FY2022 restaurant footprint growth will exceed FY2021’s.
An Enticing Long-Term Growth Opportunity
Long term, Restaurant Brands is a growth opportunity because all four of its brands have international growth potential. Tim Hortons, Popeyes, and Fire House Subs have barely penetrated foreign markets, and Burger King’s footprint appears insignificant compared to that of its closest competitor, McDonald’s.
Meanwhile, management says all four brands, especially Popeyes, still have room to grow in home markets. Greater convenience, menu innovation, and loyalty programmes could lift same-store sales beyond geographic expansion. Topline growth through higher retail sales will boost restaurant and corporate margins. The company is also looking to bottomline growth through economies of scale in commodity procurement, reductions in corporate overhead, improvements in technology and the digital platform, and advertising to boost margins.
Restaurant Brands Q2 Takeaways
Tim Hortons, Burger King, and Popeyes all saw comparable sales increases in F2Q2022. Company-wise, retail sales rose 14.2% to $10.1 billion and revenues were up 14% to $1.64 billion over the year-ago quarter. The higher sales boosted both gross profits and operating income.
Although net income slid 11.6% to $236 million from Q1 2022, earnings per share were above consensus estimates at $0.77 (negative 8.4% compared with Q2 2021), beating analyst projections of $0.73.
Tim Hortons’ turnaround depends on menu innovation. Timmies’ same-store sales are up 14% year over year and 2% from Q2 2019. Breakfast items, coffee, baked goods, specialized and cold beverages, and lunch and dinner offers drove outperformance. Over three years, the food segment grew 30%, specialty coffee and cold beverages 12%, and lunch 8%. Dinner was the second-fastest-growing segment year over year.
A turnaround at Burger King U.S. is key. Burger King’s initiatives to improve its financial performance in its home market have gained momentum, with the brand decreasing its same-store sales shortfall relative to the competition and boosting system sales in Q2 2022.
Despite local losses, the brand’s overseas business is outperforming. Sales are being bolstered by pandemic-era growth in off-premise sales, supported by drive-thrus, delivery, and carry-out; as well as the upturn in dine-in sales, as people are out and about, resulting in sales outperformance in Western Europe, especially Germany, France, and the U.K.; and in Latin America, specifically Spain and Brazil. According to corporate data, sales growth is driven by a shift in customer behaviour favouring out-of-home meals, not just mobility.
Popeyes’ chain development engine is delivering. During Q2 2022, system sales grew by 10%, with a good rebound in U.S. sales, which rose by 6%. This growth was driven by restaurant launches in Turkey, Spain, India, and the U.K. Management says FY 2022 worldwide new unit development will exceed FY2021 levels.
Tim Hortons, Burger King, and Popeyes grew restaurants by 5.7%, 2.8%, and 8.1% in the second quarter, respectively. Tim Hortons’ and Popeyes’ global restaurant base grew 20%.
Restaurant Brands Has Strong Financials
As sales growth accelerates, profitability and free cash flows will likely soar in 2022. In Q2 2022, Restaurant Brands had $838 million in cash and cash equivalents and $12.9 billion in long-term debt. The company’s debt-to-EBITDA ratio was 5.4x, below the preceding quarter and in accordance with covenants. QSR’s steadily growing dividend was upped to $0.54 per share in 2022. Cash flows from operating activities spiked 87% to $1.7 billion in Q2 2022, while capital deployed to reward investors with share buybacks and dividend growth led to an overall negative cash position.
Bottom Line
The strong expansion in home markets and international regions through geographic diversity is the brand’s key development driver. Restaurant Brands is thriving as foreign business booms. Tim Hortons’ company is humming, and Phase 2 of the recovery programme will add additional fuel. Although Burger King U.S. is investing heavily to regain market share, the company is slowly but steadily deleveraging (net leverage is 5.4x, down from 6.1x in 2020) and has an untapped $998 million revolving credit facility. Strong franchisee enthusiasm (QSR is 100% franchisee-driven) has led to record new unit development, with pipelines across all four brands planned years in advance. A more diversified Restaurant Brands appears well-positioned given the more positive business conditions. Investors who buy at current prices could be richly rewarded when the stock breaks out in the next couple of years.