


Market volatility is often dismissible as noise, but for income-focused investors who augment portfolio dividend income with periodic stock sales, it can feel like a structural threat, especially when some dividend stocks cut payouts or substantially stumble. That’s why I want to own companies whose cash flows are decoupled from trade disruptions, rate shocks, and flash recessions. After a year, and a quarter that has tested every business’s resilience, Intact Financial (TSX: IFC) stock is one Canadian dividend stock that stands even taller and earns my trust.
Source: Getty Images
Intact Financial stock: A business that doesn’t know recessions
The core reason I’d trust Intact Financial stock when markets get choppy is the nature of its revenue. As Canada’s largest property and casualty insurer, it covers homes, autos, and businesses – coverage that’s often a legal or contractual requirement. In a downturn, consumers may skip a vacation or delay a phone upgrade, but they can’t legally drive without auto insurance or maintain a mortgage without home insurance. That demand floor remains intact, regardless of economic weather.
Revenue and cash flow resilience helped IFC stock sustain dividend hikes during past recessions.
The interest rate shock absorber
If higher oil prices trigger a new wave of inflation, I wouldn’t be too worried. Intact Financial stock does something rare when interest rates rise. While highly leveraged REITs, utilities, and pipelines see borrowing costs soar, insurers hold a massive pool of premiums (the “float”) invested mostly in fixed income.
When interest rates rise, the yield Intact earns on its new bond purchases increases. While most companies scramble to cover higher interest expenses, Intact actually sees its internally managed investment income grow. This creates a natural hedge: the interest risk that “chops” the rest of the stock market often acts as a tailwind for Intact Financial stock’s bottom line.
That said, rising rates do create short-term mark-to-market losses on the bond book, but Intact Financial’s hold-to-maturity approach turns that noise into a footnote.
Operational excellence backed by recent earnings results
Trust in a dividend stock is earned through consistent execution. Intact Financial stock consistently delivers an industry-leading combined ratio – a measure of underwriting profitability. In 2025, it achieved 88.2%, a full four points better than the prior year. Anything under 100% represents underwriting profit before investment income, and Intact Financial’s data-driven pricing power allows it to adjust premiums quickly when claims costs rise. That discipline ensures earnings fund the dividend, not financial engineering.
Intact Financial had an unusual moment in early 2025: a modest revenue miss triggered a short-term dip. But that noise obscured the bigger picture. Full-year net operating income per share surged 33%, book value per share grew 16% to $107.35, its combined ratio improved, and return on equity (ROE) was strong at 18.4%.
IFC stock: A trustworthy dividend growth engine
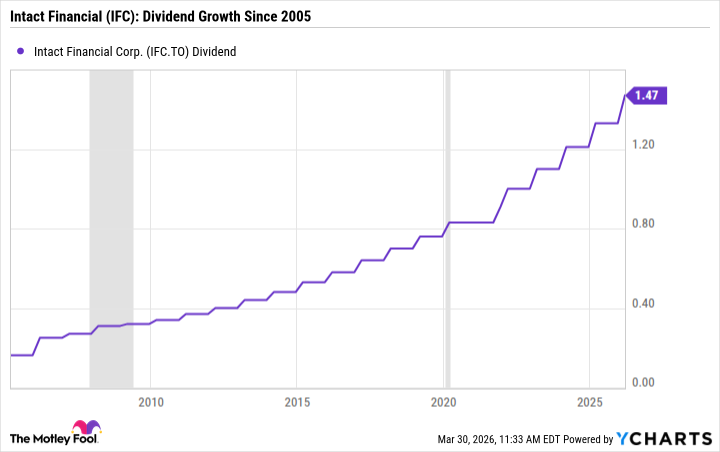
In February 2026, Intact Financial raised its quarterly dividend by 11% , marking the 21st consecutive year of increases since its going public IPO in 2004. The current yield sits near 2.4%, but the most impactful story is the dividend’s 10% compound annual growth rate over the past decade. IFC stock’s earnings payout rate holds around 30%. Profits secure the dividend, leaving room for more growth.
IFC Dividend data by YCharts
More importantly, Intact has never cut its dividend – not during the 2008 Global Financial Crisis, the 2014 oil crash, or the 2020 COVID-19 pandemic. The dividend growth “ladder” keeps rising through choppy markets, pushing yields higher for early investors.
A balance sheet built for choppy markets
With a debt-to-total-capital ratio of just 16.5% at year-end 2025, well below the insurer’s 20% target, Intact Financial has ample dry powder. Management has gained $4–5 billion in acquisitions capacity without needing to raise equity. When stock markets turn sour, this financial fortress can become an opportunistic consolidator, turning volatility into a long-term growth catalyst.
The Foolish bottom line
Intact Financial stock proved in 2025 that even a modest revenue miss couldn’t derail its dividend growth or balance sheet strength. With a 21-year dividend-raising streak, a sub-20% debt ratio, and $4–5 billion in firepower, this Canadian dividend stock will do better than just survive choppy markets – it may use them to get stronger. Intact Financial stock is an intact financial fortress worth holding onto for growing dividends.







