Let’s not forget about mid-cap stocks, which might be a great place to score an even better discount at a time like this, when geopolitical uncertainties seem to be hitting a high-water mark. Of course, the ride could prove choppier with the small- and mid-cap stocks. But if you’re seeking growth at a wider discount, I do think your chances are better with some of the hidden gems buried in the TSX Index.
In this piece, we’ll check out a proven performer that’s been gaining significant traction. Though the past year of gains says nothing about what to expect in the future, I do think that long-term investors seeking great fundamentals that stand to get even better with time might wish to check in with the name.
Whether one chooses to nibble a bit here or wait for a (further) pullback after a heated run, though, depends on how strong one’s stomach is.
Personally, I’d not be afraid to step in as a buyer here, even though a “market upset” could happen at any moment and drag down a stock into a bit of a rut through no fault of the firm itself. Sometimes markets reset, and as an investor, it’s important to be prepared for increased turbulence. If you’re a long-term investor and not a trader, I think the following mid-cap looks very compelling at today’s valuations.
Source: Getty Images
Badger is a great mid-cap infrastructure play with an aggressive growth plan
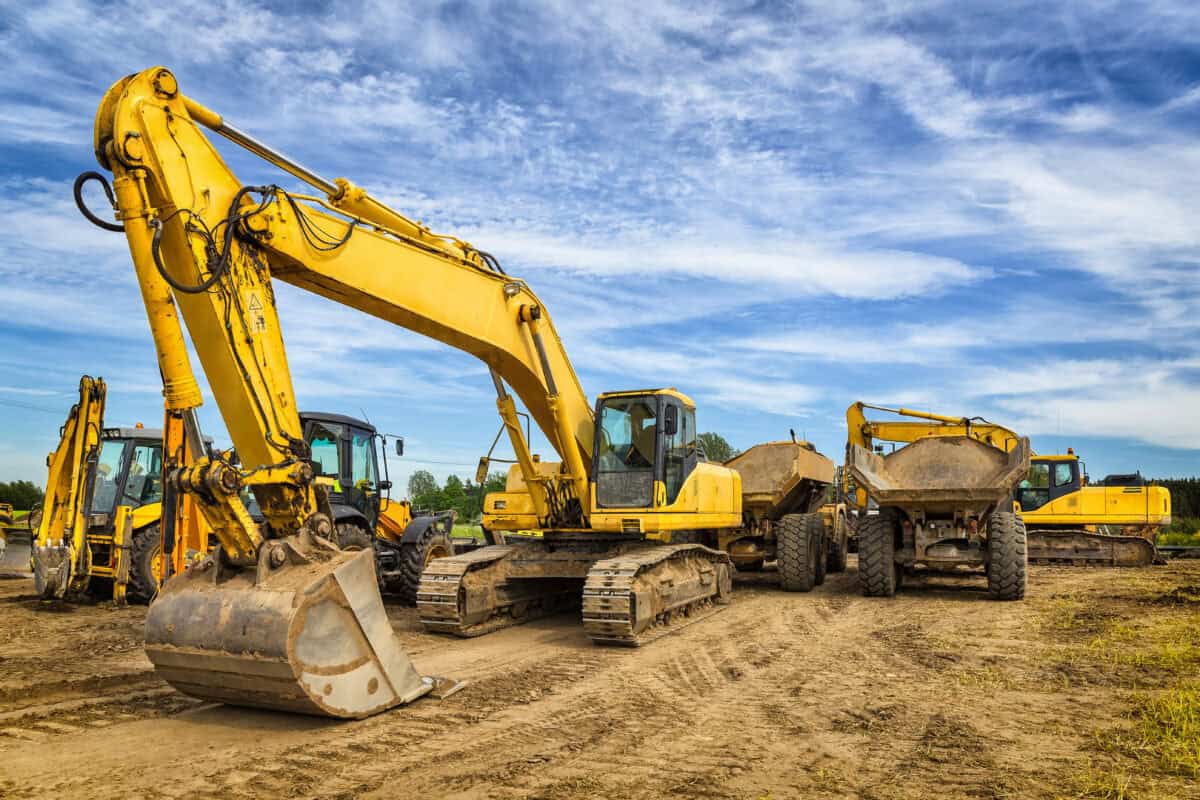
Enter shares of Badger Infrastructure Solutions (TSX: BDGI), which has had an awful start to the year, now down around 23% from its all-time highs just shy of $83 per share. Despite the bear market drop, shares are still up around 78% in the past year (and up around 103% for 2025). Indeed, the provider of non-destructive excavating solutions had a 2025 to remember. But just because shares are coming in doesn’t mean it’s time to throw in the towel on the mobile soil excavation service provider. As infrastructure spending rises, especially in the oil patch, so too will demand for “daylighting” solutions.
Of course, the company is in expansion mode, and while the growth promise is more encouraging, investors seem to be cautious about the capital expenditures required for such an ambitious move. Of course, higher fuel prices, labour, and other inflationary headwinds could take away from the bottom line amid the Iran crisis. If oil prices normalize sooner rather than later, though, I do view Badger as a name that could enjoy quite a bit of relief.
Either way, investors do hate higher spending (just look at what happened to the hyperscalers), even if it means greater growth down the line. For now, there are big question marks surrounding what the expansion plan could do to the returns on investment.
Don’t discount the infrastructure tailwinds!
Personally, I think the fleet buildout, though risky, is coming at the right time. Infrastructure spending seems destined to keep marching higher and, with that, Badger will need more trucks on the road. Is the expansion without its fair share of risks?
Of course not, but with the dip already in the books, let’s just say I like the risk/reward at 20.3 times forward price-to-earnings (P/E), which is incredibly cheap given the industry tailwinds.
In the next five years, I’d look for Badger to keep rising up the ranks in the market-cap ladder. Can a $5 billion valuation be on the table in five years? Time will tell. But Badger’s going for growth, and I think investors are wise to stick with it on the way down. It’s a great business with excellent managers who, I think, deserve the benefit of the doubt as they scale up for what could be a multi-year opportunity to take sales growth to the next level.