Political headlines can move faster than the businesses underneath them. Quebec’s election has brought sovereignty back into investors’ conversations, along with the familiar temptation to make a sweeping portfolio decision before anything has actually changed for customers.
The Parti Québécois won 59 seats in the October 5, 2026 election. That result doesn’t itself separate the province or rewrite the rules under which Canadian companies operate. The political process and the legal process still have several steps between an election and any constitutional change.
Investors can take the uncertainty seriously without treating every Quebec address as a sell signal. A company’s customers, assets, financing, and geographic reach provide a more useful starting point than the location printed on its letterhead.
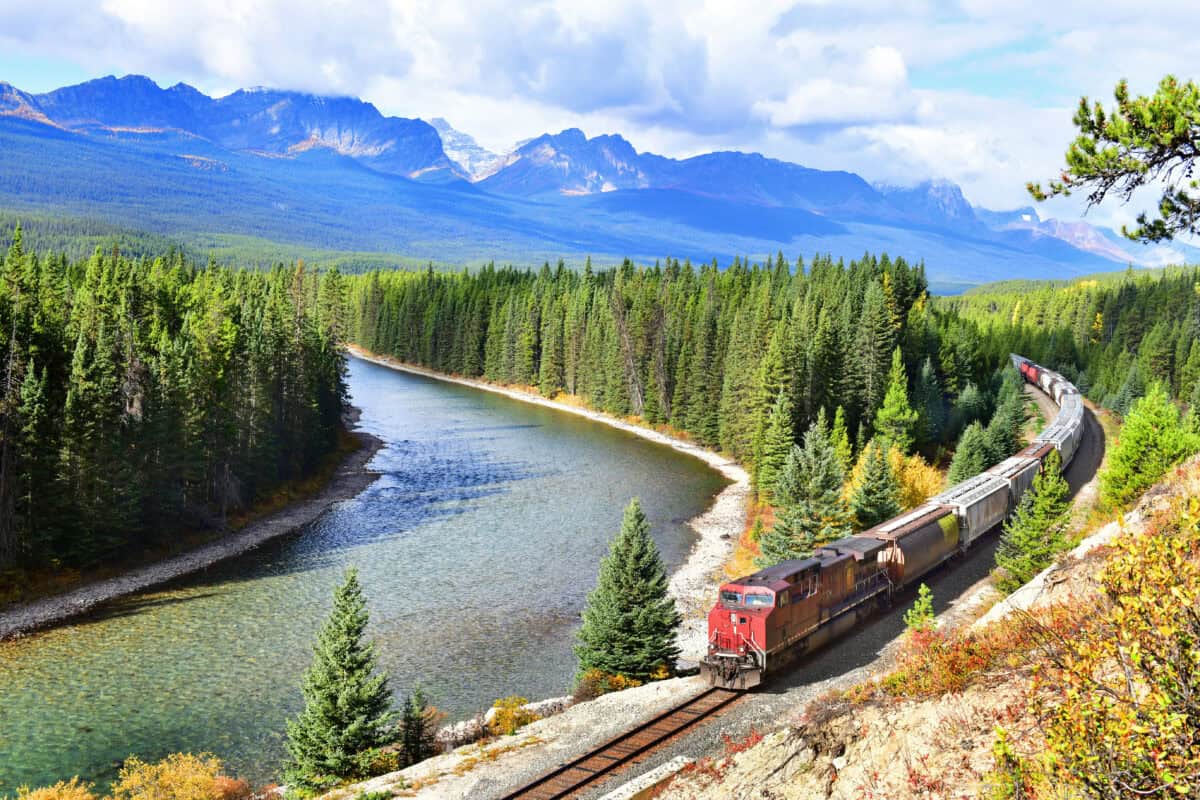
Source: Getty Images
Honest comparison
A steady stock price after an election doesn’t prove that politics has no financial consequences. Other news can push in the opposite direction, and the broader market may be rising or falling. The price shows the net result of everything investors are considering, not a clean public-opinion poll.
That’s worth remembering with Canadian National Railway (TSX: CNR). Its shares closed October 2, the last trading day before the election, at $170.66, and at writing have hardly moved.
The railway’s Montreal headquarters make it an obvious name in the discussion. Its network and customer relationships extend far beyond Quebec, however. Freight still needs to move between farms, factories, ports, and buyers across North America. So let’s dig deeper.
Into earnings
CN reported second-quarter adjusted diluted earnings per share (EPS) of $2.08, up 11% from a year earlier. That improvement provides a concrete operating reference while investors debate the political backdrop. It doesn’t guarantee the next quarter, but it’s more relevant to dividend capacity than speculation alone.
The business benefits from an established rail network that would be exceptionally difficult to reproduce. That helps protect its position. Freight customers can still ship less when economic activity slows, and disruptions can make a valuable network expensive to operate.
At writing, CN costs roughly 20.4 times earnings. That suggests a buyer should expect continuing execution and earnings growth, instead of assuming the political headlines have created an obvious clearance sale.
Considerations
Trade weakness could reduce volumes. Fuel costs, labour issues, severe weather, and service disruptions can hurt margins. Those risks remain relevant regardless of the party governing Quebec. A railway can disappoint shareholders for perfectly ordinary commercial reasons while everyone is busy watching a referendum debate.
For a long-term Canadian stock portfolio, I like the durability of CN’s infrastructure more than a short-term bet on political sentiment. At roughly 20 times the latest earnings pace, I see a reasonable long-term holding, not a political panic bargain. Keeping the position diversified leaves room for an ordinary freight downturn.
Its place in a dividend strategy also depends on growth in cash available after network investment. Regular distributions are helpful, but the railway has to maintain the tracks and equipment that generate the cash in the first place.
Bottom line
The election-to-price comparison also spans several trading sessions with changes in rates, commodities, and broader market sentiment. It doesn’t show the return an investor would have earned from a perfectly timed political trade. For someone adding gradually to a retirement portfolio, the more relevant choice is whether a profitable continental railway fits at today’s valuation and at a position size they can comfortably keep.
I’d keep watching freight volumes and the cost of running the network as the political discussion develops. If customers keep shipping and CN keeps turning those shipments into better earnings, the investment case can advance without requiring anyone to predict Quebec’s next constitutional chapter.