My wife and I recently spent a weekend in downtown Boston. Having forgotten my allergy pills at home in Toronto, we made a beeline for the closest drugstore, which just happened to be a two-floor CVS Health Corp. (NYSE: CVS) right in the heart of Back Bay.
Upon walking in, we were immediately greeted with a warm welcome from a store employee who was out on the floor standing adjacent to the entrance. He was one of the several employees wandering both floors making sure customers got what they came for.
After greeting us, he asked if we were looking for anything in particular. I mentioned I’d forgotten my allergy pills. Without hesitating or having to look it up, he said, “Second floor, aisle 11.” If he wasn’t assigned the front door, I’m sure he would have taken us there personally.
As we rode the escalator to the second floor, we both remarked how cool it was to get that kind of service from a drug store — especially from one that’s part of a massive, faceless retail chain.
Non-existent service
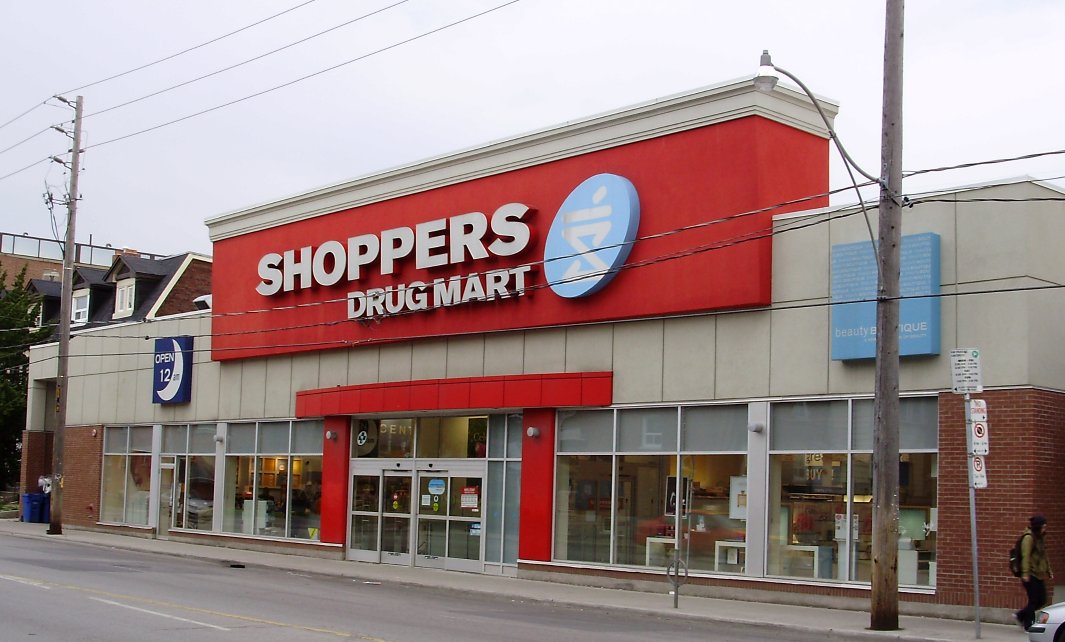
You see, where we live in Leaside, a Toronto neighbourhood, our local Shoppers Drug Mart provides customer service that literally moves at a snail’s pace.
It doesn’t matter what time a day you go in to the store; there’s inevitably a lineup to pay at the cash. And God help you if you need to get someone to help find something. It’s virtually impossible.
Yet the business media has some of the most complimentary things to say about Shoppers’ parent, Loblaw Companies Ltd. (TSX: L) — myself included.
Praise for Loblaw
As someone who writes about stocks on both sides of the border, I couldn’t help but praise Loblaw in my April 14 article about its fantastic free cash flow generation.
“Since Galen Weston closed the deal to buy Shoppers Drug Mart in March 2014, Loblaw’s free cash flow has grown four-fold to $2.3 billion,” I wrote. “Before Shoppers, a $1.3 billion expenditure [how much the company is spending in fiscal 2017 on new stores and renovations of existing ones] would have eliminated its free cash flow almost entirely. Now, it represents just 37% of its annual operating cash flow.”
I too am hopelessly enamoured by Loblaw’s ability to generate excess cash: the cornerstone of any successful business.
Other Fool.ca contributors are equally enthusiastic.
Recently, Fool.ca’s Demetris Afxentiou called it a defensive play for any portfolio. His arguments for owning Loblaw stock ring true. However, it was his comments about Shoppers Drug Mart that caught my attention:
“One advantage that Loblaw has over the competition is the network of Shoppers Drug Mart stores. These pharmacy stores are much smaller than the typical Loblaw store, but they provide nearly the same level of national coverage,” Afxentiou wrote. “Loblaw has placed selected grocery products in Shoppers locations, thereby creating another option for consumers that need a few items on the way home who would rather not go to a larger grocery store.”
There’s no question that the 2014 acquisition transformed Loblaw’s business.
Thankfully, investors care little about customer service
After my CVS experience, which I realize might have been an aberration, I’m more likely to consider CVS stock.
As for Loblaw, this apparent gap in service has led me to reconsider whether I should buy its stock. Free cash flow or not, I believe good customer service is a reliable indicator of future financial performance.
The average investor might not care about service levels at Loblaw or its drugstore subsidiary, but I do.
Until I see a marked improvement at Shoppers Drug Mart stores (it’s not just the one on Bayview that’s poorly run), I’m hesitant to recommend Loblaw stock.
Bottom line on Loblaw stock
If you own Loblaw, I wouldn’t sell.
However, if you don’t, you might want to visit some Shoppers Drug Marts before investing your hard-earned dollars in its stock. If you feel the service isn’t an issue (it’s possible I’m too picky), buy away.
But if you don’t feel it’s up to snuff, find yourself another target, because there are a lot of worse things in life than sitting in cash.