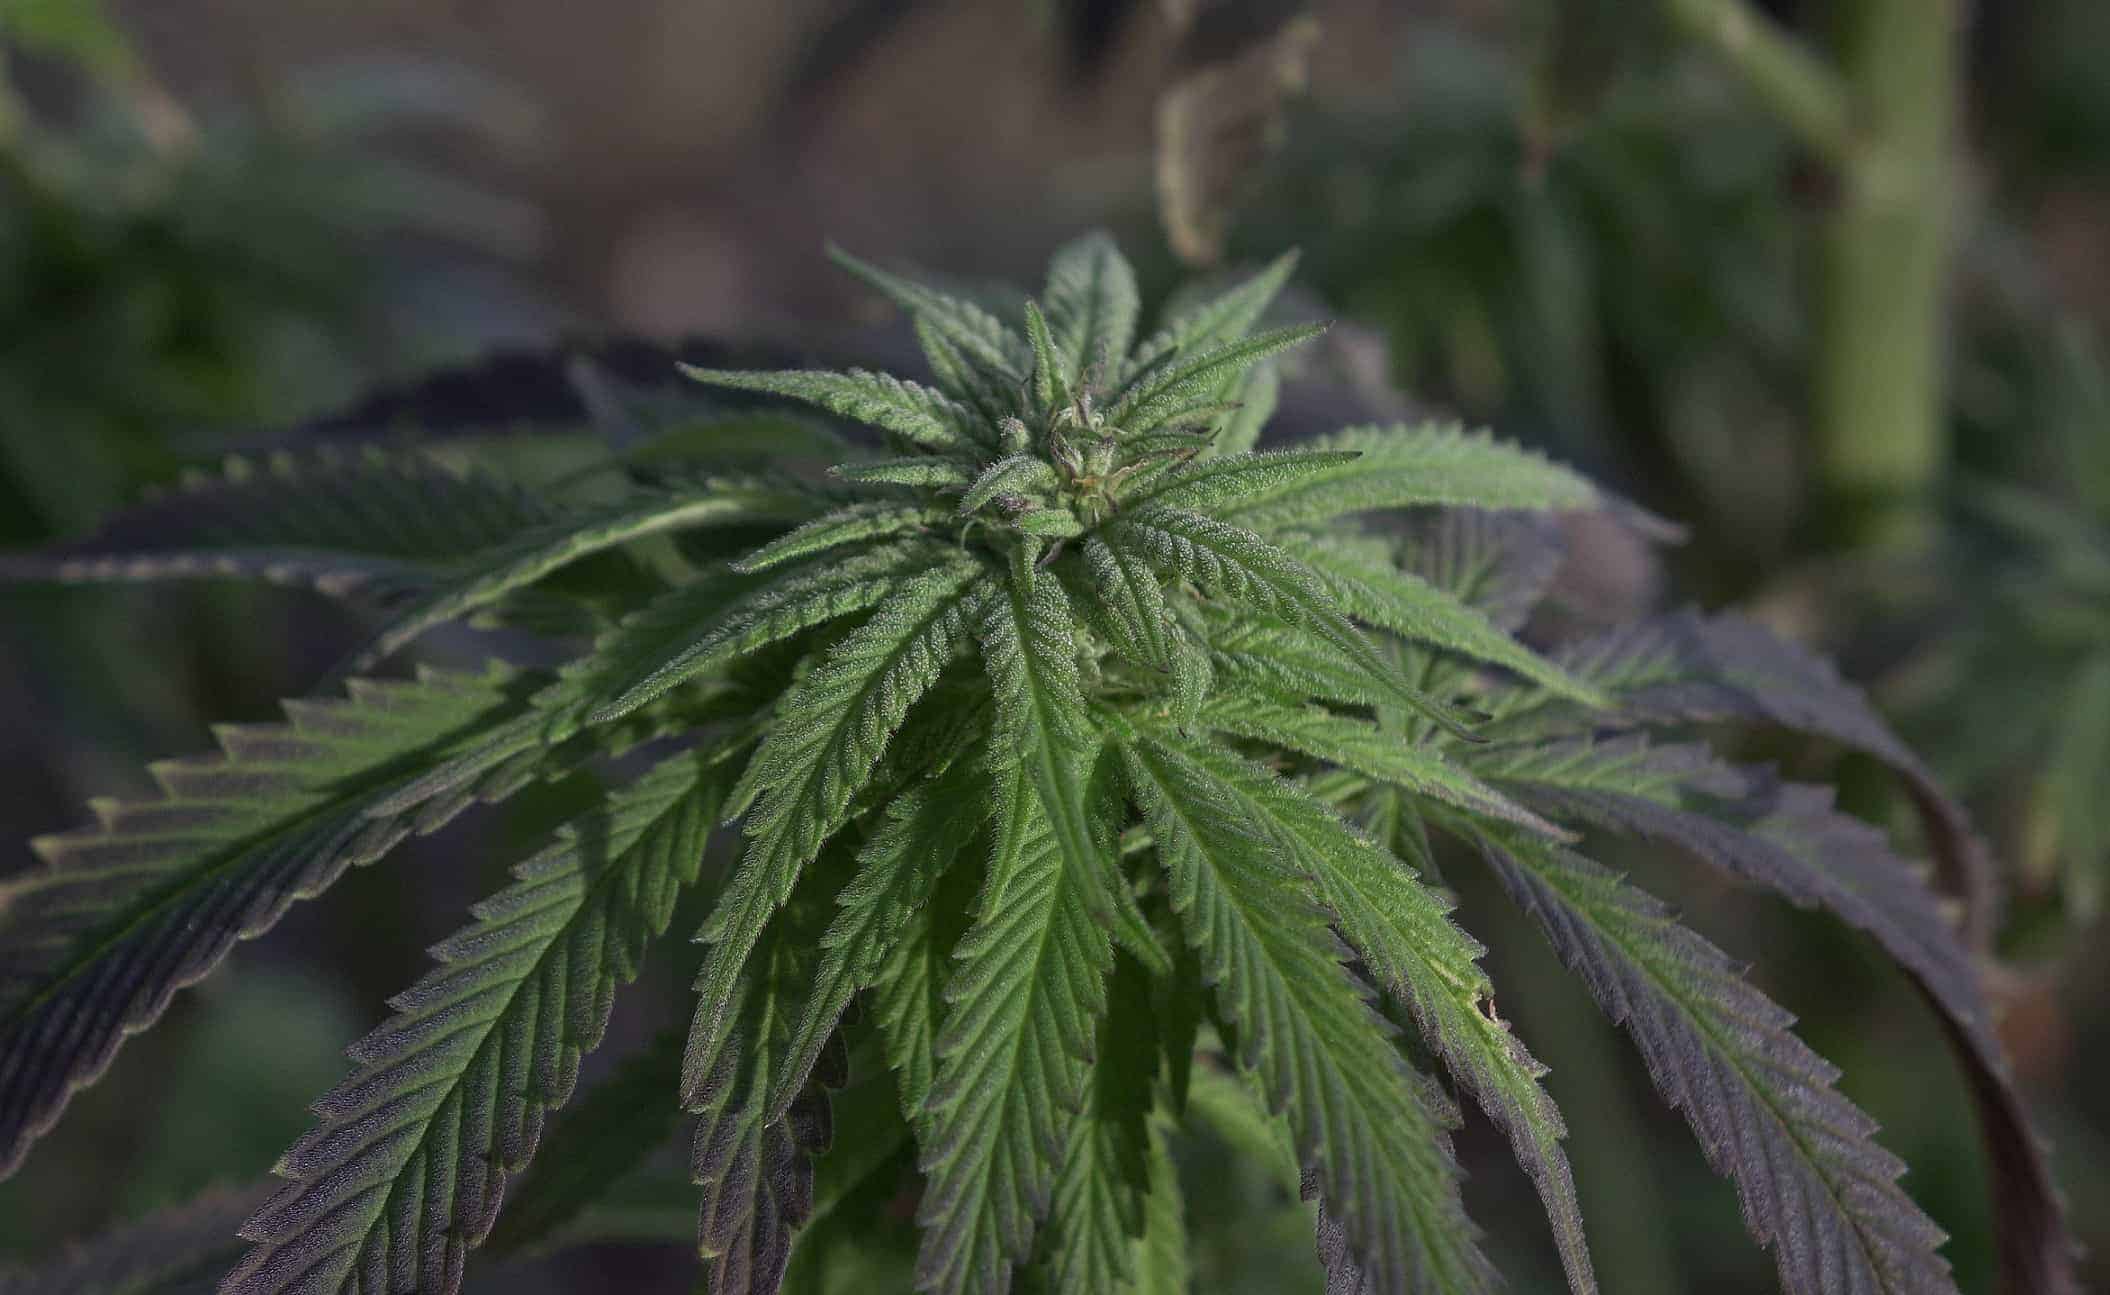
One of Canada’s most prominent cannabis producers (and one of the largest in terms of sales), Canopy Growth Corp. (TSX: WEED), has experienced quite the stock price drop since early 2018. After Canopy hit an all-time high of $44 per share, investors are currently able to scoop up shares of the pot producer for a measly $26.50 as of Monday open, a nearly 40% discount to its all-time high.
Investors appear to be spooked by a number of headwinds playing out in the marijuana sector, among which are fears that a bubble may be brewing, and that acquisition multiples may not pan out in the long term for the acquirers, given the massive premiums that have been paid of late for bolt-on productive capacity deals.
However, perhaps one of the most visible headwinds for Canopy, and all other Canadian marijuana producers, has been indications that legalization may take longer than expected. The Canadian Senate has scheduled a final vote on the matter for June 7, and given the fact that provincial and territorial governments will need eight to 12 weeks to prepare for retail sales, estimates are that recreational marijuana may not be available for sale for the average Joe until late August or early September.
On a fundamental basis, I am still scratching my head as to why the legalization date for cannabis really matters all that much. Whether we’re talking about July 1 or August or September, in my mind, the reality that the green commodity will be legalized should be enough to support stock prices at historical levels. The drop in relative valuations of most cannabis producers since the beginning of the year has largely been linked to the legalization date; however, I believe that investors may simply be taking profits off the table and re-valuing such firms toward their true intrinsic values, which I have held are far below current levels.
Bottom line
If investors expect the market to continue to re-assess the valuations placed on Canadian cannabis producers and begin valuing these firms on actual operating margins and long-term profitability (not short-term IFRS profitability increases related to the value of the plants currently being grown), then significant downside remains. I would encourage caution for any investor considering any Canadian cannabis producer before legalization and would encourage any such investments to be made on a operating margin/fundamental security-analysis basis following (preferably) five years of earnings results or more to ensure such an investment is just that — an investment, and not a speculation.
Stay Foolish, my friends.