


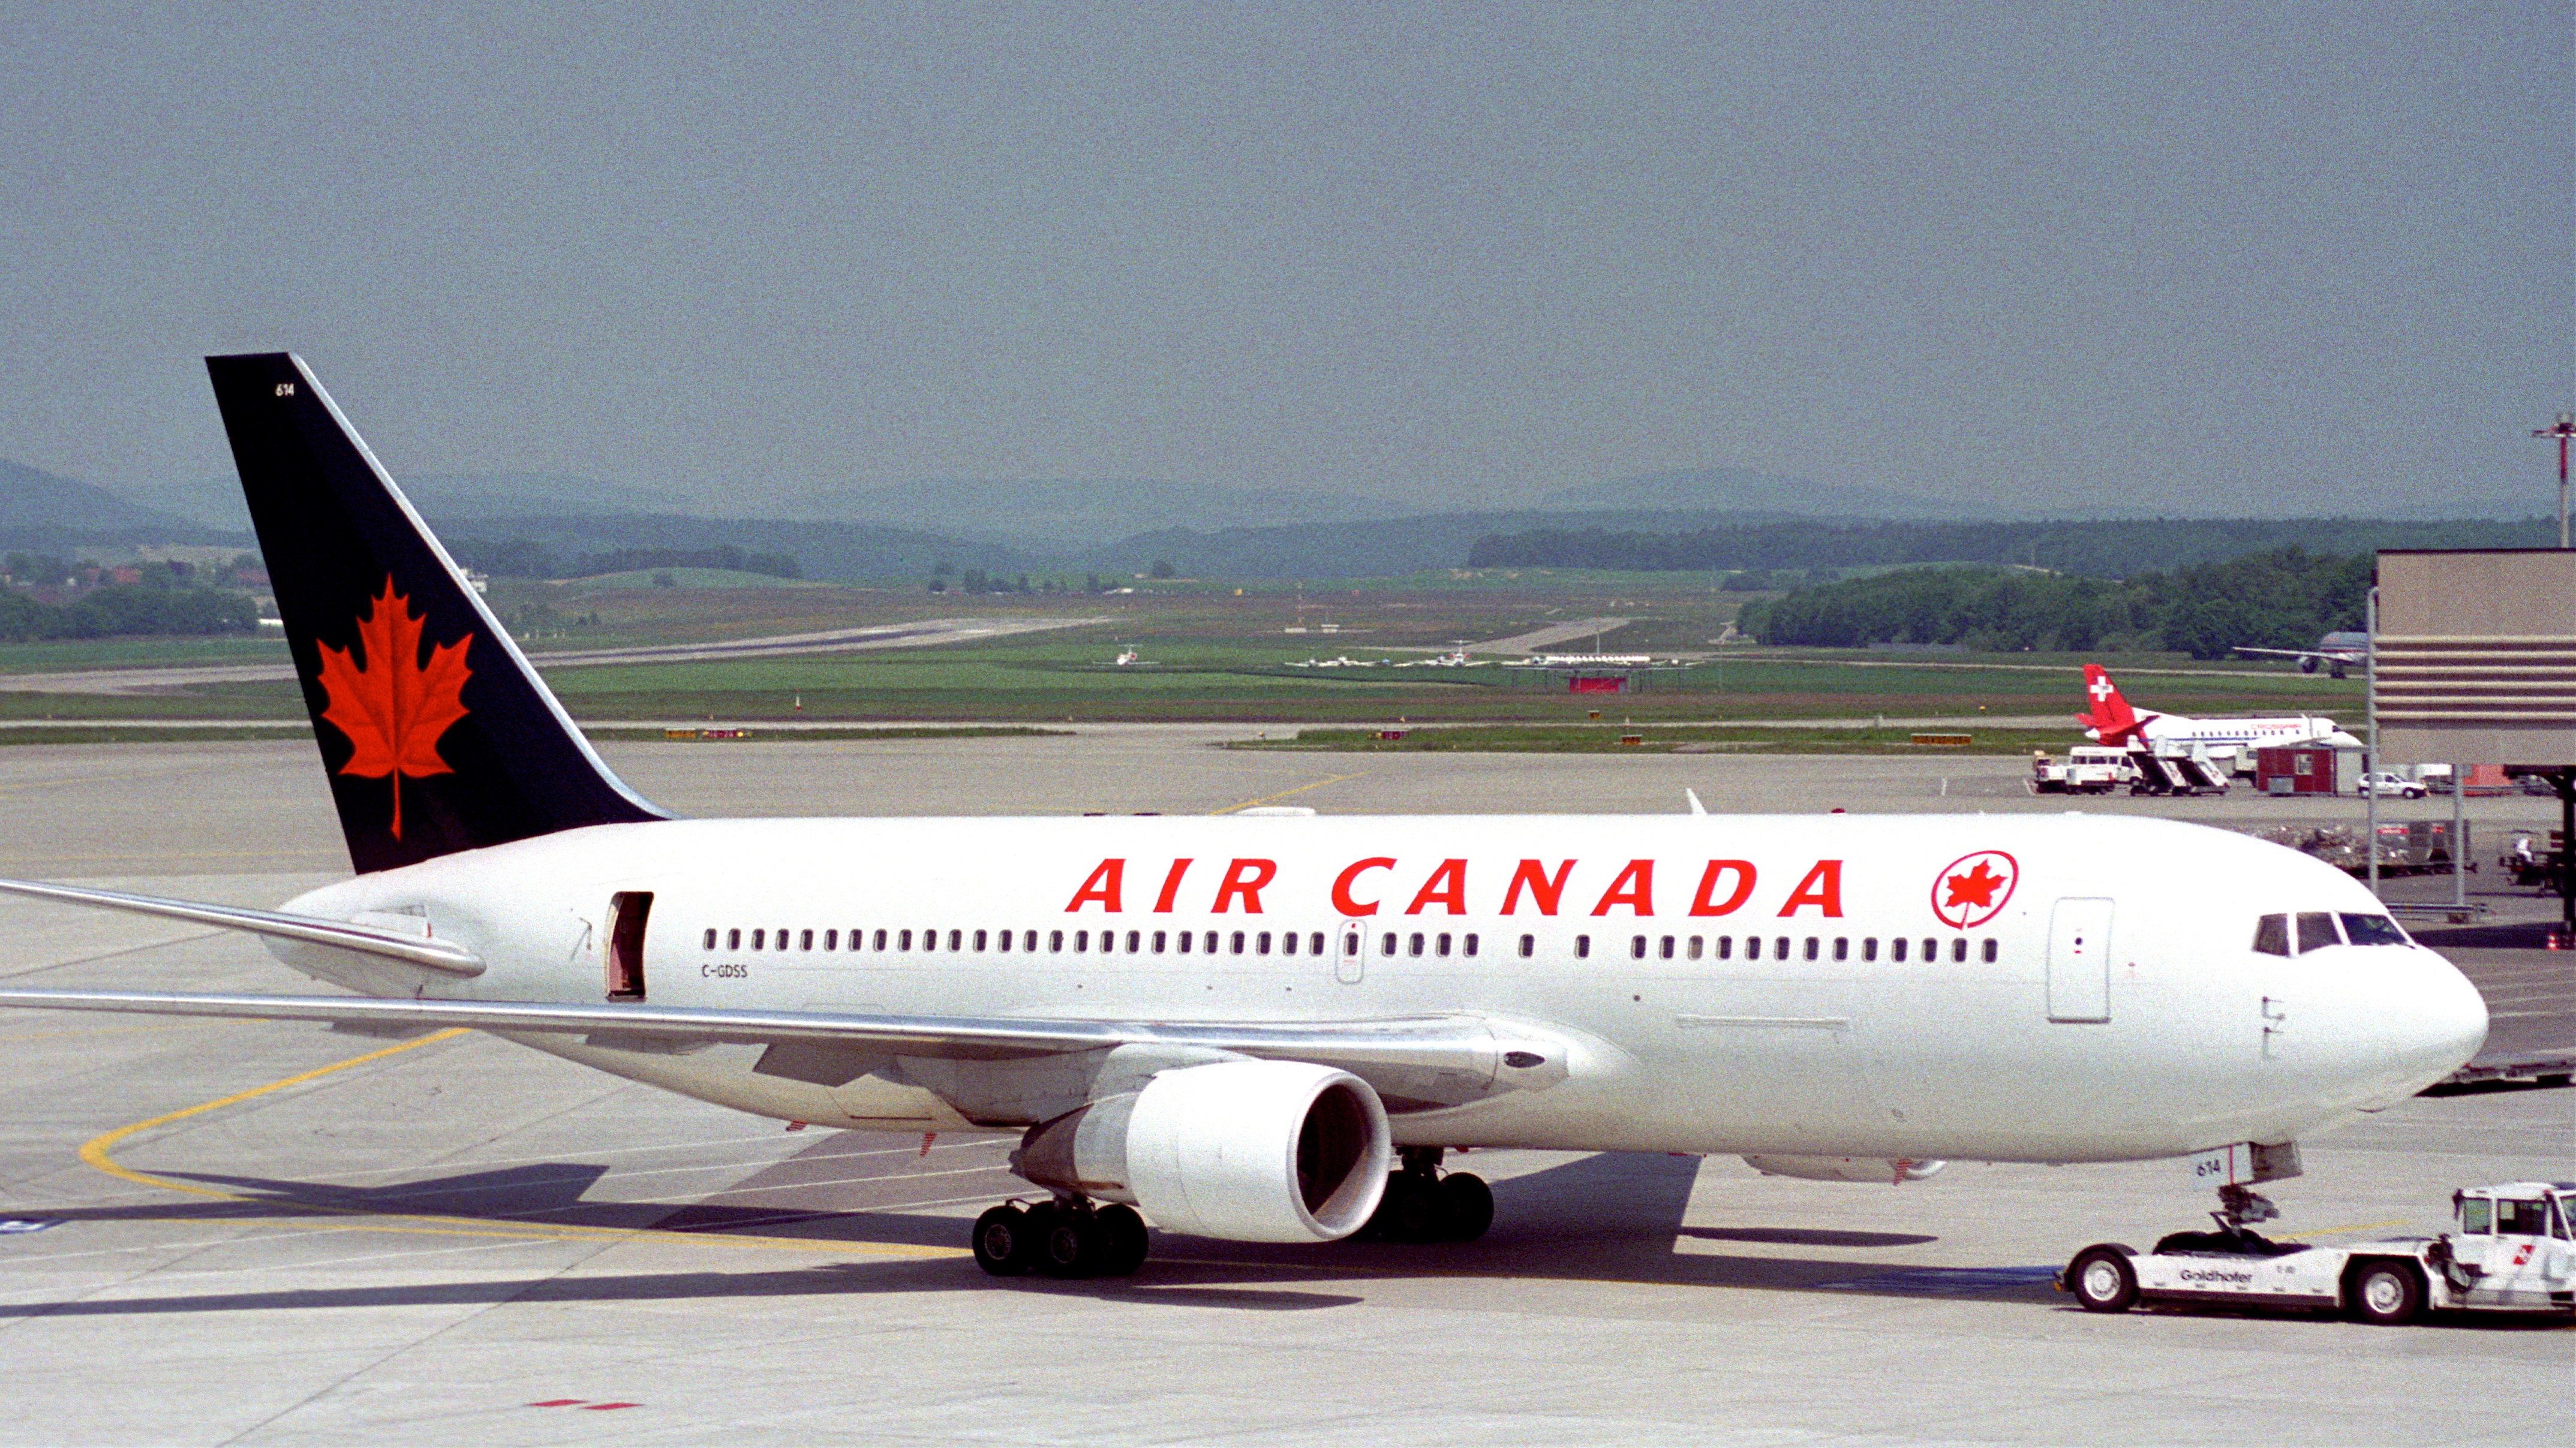
After rising almost 100% since the beginning of 2017 and from just $2 five years ago, Air Canada (TSX: AC)(TSX:AC.B) shares are rising again to the tune of 4.5% to highs of over $27.
This is after the company reported another stellar quarter and year last week.
EPS came in at $0.22, blowing past expectations that were calling for EPS of $0.14, as profits more than doubled in the year amid increasing traffic and better profitability. The company has been performing well above expectations for at least the last couple of years, which has led to increasing estimates and this outperformance of its shares.
Earnings before interest, taxes, depreciation, amortization, impairment, and aircraft rent, or EBITDAR, once again came in higher than expectations, and at $521 million, it was 14.5% higher than the same period last year.
This is despite the fact that the company’s biggest expense, oil, is up big compared to last year. Operating expenses rose a reasonable 8% (fuel cost per litre increased 13.8%) compared to last year amid capacity additions and rising fuel prices.
Traffic growth of 9.9% was accompanied by capacity growth of 9.5%, as the airliner maintained discipline and continued to effectively manage its supply/demand dynamic.
The good news keeps pouring in. Free cash flow in 2017 was a record $1.056 billion, which is higher than management’s guidance of $600-900 million.
Looking ahead to 2018, we can expect higher costs, most of which can be attributed to one-time items, a slowing capacity growth rate (7% growth), and an EBITDAR margin of 17-19%.
Furthermore, a new cost-transformation program is being undertaken to further improve the company’s cost profile. This program is targeted to deliver $250 million in savings by the end of 2019 by streamlining operations and business processes, such as procurement and maintenance operations, aircraft leases, and supply chain.
And with the airliner sitting on almost $6 billion of debt for a debt-to-capitalization ratio of a whopping 64%, increased cash flow will result in reduced leverage and, ultimately, a lower-risk profile for the company.
Air Canada is not the airliner of the past. This renewed focus on returns on invested capital, cash flow, free cash flow, and growing profitably has injected real change at the company, as we can see in the results that have been achieved in the last few years.
While investors should remain cognizant of the fact that this business is a very cyclical one with big capital requirements, Air Canada continues to do the right things.
The key risks remain the economy, a weakening of the consumer, and rising fuel prices.







