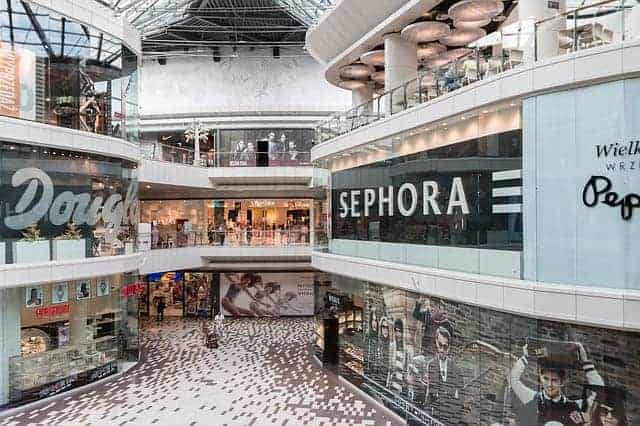
SmartCentres REIT (TSX: SRU.UN) is a security that’s been hovering around in limbo for over three years now. The 5.75%-yielding REIT looks to be slapped with a hefty discount because it’s a retail REIT, which is arguably one of the unsexiest sub-industries, not just in the REIT sector, but of all asset classes.
The public is just plain wrong about SmartCentres
What’s the consensus on malls?
E-commerce is the future, and the malls of tomorrow are dead. The rise of the stay-at-home economy will result in the malls of tomorrow ending up as deserted wastelands. Retailers from across the board are going to be closing up shop, and retail REITs are going to need to reduce their distributions in conjunction with the rising vacancies due to the seemingly insurmountable secular headwinds that brick-and-mortar retail is facing.
That’s the thesis that many folks on the Street have thanks to the shock waves caused by Amazon.com and other direct-to-consumer (DTC) digital retailers that have embraced the new age of retail. While e-commerce is going to continue to accelerate at the expense of physical retailers, I believe the fears over the “death of the shopping mall” are severely overblown to a point where many of today’s quality retail REITs are trading at a massive discount to their intrinsic values.
What is intrinsic value?
Intrinsic value is an investor’s estimation of the true value of discounted future cash flows. It considers cash flow growth prospects and any potential headwinds that may serve to drag on the future cash flow stream. The intrinsic value of an underlying company isn’t merely the value of assets on its books; rather, it weighs the benefit of both tangibles and intangibles.
At current levels, the bears believe that retail REIT’s future cash flow streams will eventually deteriorate, as e-commerce continues to take off. This may be the case for poorly managed retail REITs, but I think this cash flow deterioration will not shake up well-run REITs like SmartCentres, especially when you consider the company’s ambitious long-term plan to diversify into other “hot” sub-industries in the REIT space.
First, SmartCentres continues to exhibit very low vacancy rates in spite of the rise of e-commerce. Moreover, the trust’s tenant base is full of robust brick-and-mortar players that are likely going to continue to draw in huge crowds for decades to come. Many of these healthy physical retailers have already adapted to become more experiential, and it’s these tenants that will draw in crowds to other retailers on the same premises.
Second, nobody is talking about SmartCentre’s extremely long-term plan. You mention long term, and many investors will throw in the towel to look for a timelier opportunity. SmartCentre’s long-term game plan is worth the wait though, especially for retirees who will be well compensated with a bountiful 5.75% annual distribution yield that’s paid out on a monthly basis.
So, what’s the long-term plan?
SmartCentres plans to gradually diversify away from pure retail with its ambitious “master planned community” projects that’ll combine residential, and commercial real estate together to form a better experiential environment for inhabitants and locals in the area.
Foolish takeaway
I’m a raging bull on where SmartCentres is going with its new plan. And when combined with the robustness of its current retail operations, I’d urge retirees to back up the truck on shares today while they still trade at a discount to intrinsic value.
Many investors shun the name because it’s a retail REIT. I think that’s completely unwarranted. The distribution is not only large but is well positioned to grow subtly over the course of many years — a rare characteristic of high-yielding REITs!
Stay hungry. Stay Foolish.