


Canadian natural gas stocks are being pummelled by the market. A perfect storm of a growing supply, declining demand, and a prolonged price slump are applying considerable pressure to their operations. This is expected to trigger a spate of bankruptcies among natural gas producers, with most bleeding red ink for a prolonged period.
One Canadian natural gas stock that will thrive despite the harsh operating environment is Canacol Energy (TSX: CNE). The upstream natural gas producer has lost 16% since the start of 2020, which is less than the 35% decline of the North American natural gas price.
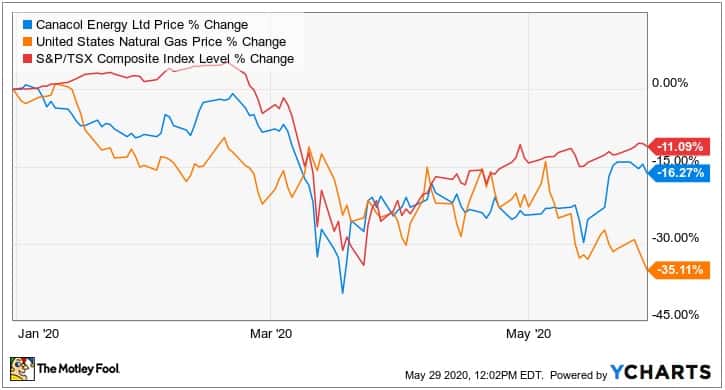
The reason for this is simple; Canacol has been able to capitalize and profit from the extraordinary conditions that exist in Colombia’s domestic energy markets.
Uniquely positioned natural gas stock
In 2016, Canacol pivoted away from being an oil producer and focused on building its natural gas operations to become Colombia’s leading privately owned onshore natural gas producer. Canacol has amassed 624 billion of cubic feet of natural gas reserves. It has been growing natural gas production and sales at a solid clip.
For the first quarter 2020, Canacol’s natural gas production reached 201 million cubic feet daily, which was a whopping 63% higher than a year earlier. As a result, Canacol’s petroleum total output was 35,648 barrels of oil equivalent daily — a 62% year-over-year increase.
More importantly, Canacol’s natural gas sales are growing at a rapid clip. The driller reported a 65% year-over-year increase in natural gas sales for the first quarter.
That notable growth gave earnings a solid boost. EBITDAX, which is earnings before income tax, depreciation, amortization and exploration expenses, shot up 48% year over year to US$59 million.
Crucially, Canacol has been able to establish take or pay contracts for 80% of the natural gas that it produces with a price of US$4.80 per thousand cubic feet sold. That is almost triple the North American Henry Hub benchmark price of US$1.85 per million British thermal units (MMBtu).
This gives Canacol a considerable financial edge over its competitors operating solely in North America. The spot natural gas price in Colombia is higher than the North American benchmark.
The contracted nature of most of Canacol’s revenue enhances the certainty of its earnings while removing the considerable uncertainty associated with natural gas prices.
There is every indication that this favourable situation will continue.
Favourable market conditions
Colombia is experiencing an energy crisis. Dwindling natural gas supplies and rapidly rising demand is supporting higher prices. This situation won’t change anytime soon.
Colombia’s aging offshore natural gas fields have rising decline rates causing production to decline. There haven’t been any major oil or natural gas discoveries in the Andean nation for over a decade. Consequently, Colombia’s proven natural gas reserves are falling. Sharply weaker oil prices have caused investment in Colombia’s energy patch to collapse, causing drilling activity to decline boding poorly for any new discoveries.
The loss of natural gas imports from Venezuela is exacerbating the crisis.
For these reasons, the natural gas shortage in Colombia will continue.
Even lower consumption because of the impact of the coronavirus pandemic on Colombia’s economy won’t lead to lower prices for a sustained period.
Once Colombia’s economy returns to growth, demand for the fossil fuel will soar, particularly with the government seeking to expand gas-fired power generation. This will ensure that Canacol can continue locking in sales prices for its natural gas that are significantly higher than the market rate.
Growing natural gas market
This, along with the expansion of Colombia’s pipeline infrastructure, will allow Canacol to access additional domestic markets, including the country’s second-largest city Medellin.
Once the pipeline is operational, Canacol expects natural gas sales to grow by 131% to over 330 million cubic feet of natural gas daily between now and the end of 2023. Canacol’s copious natural gas reserves and expanding production will support planned higher sales.
Such strong sales growth will give Canacol’s earnings a considerable boost.
Foolish takeaway
Canacol will soar regardless of the gloomy outlook for natural gas stocks in North America. Growing sales, higher than market prices, and increased production will boost Canacol’s earnings, giving its share price a significant lift. While waiting for that to occur, you will be rewarded for you patience by Canacol’s sustainable dividend yielding 5%.






