
Aecon Stock Is Skyrocketing, and It’s Not Too Late to Buy

An infrastructure stock with record backlog and soaring revenues – and strong upside potential.

Key Points
  • • Record performance driven by infrastructure boom: Aecon reported Q3 revenue of $1.5 billion (up 20% year-over-year) with record backlog of $10.8 billion, benefiting from nuclear sector growth, utility infrastructure renewal, and demand from AI/data centres.
  • • Strong growth runway with reasonable valuation: The company faces a $100 billion project pipeline over five years and is expanding its U.S. nuclear presence to 15 states, while trading at just 18x next year's earnings and offering a 2.6% dividend yield.
  • 5 stocks our experts like better than Aecon

Investing in stocks that are benefiting from strong secular growth trends will allow you to generate strong, consistent returns over time. However, it’s important to identify those trends that have staying power, which will support long-term growth and value creation.

Last week, Aecon Group Inc. (TSX: ARE) stock soared as the company reported another record quarter. The stock is 94% higher than its 2025 lows and more than 200% higher than three years ago. This, as demand continues to soar and backlog hit $10.8 billion, us the highest level ever.

In this article, I’ll highlight why it’s not too late to buy Aecon stock despite its strong performance in the last few years.
Safety helmets and gloves hang from a rack on a mining site.

Source: Getty Images

Record results

Aecon’s recent third-quarter results were filled with positive buy signals and bullish trends. Simply put, infrastructure spending is booming. For example, the nuclear sector is ramping up, driven by renewed interest in the clean properties of nuclear energy. This is driving increased spending on new plants and refurbishments.

Other sectors that are seeing strong volumes include the utility and gas distribution sectors. This growth is being driven by the fact that more than 40% of utility infrastructure is at the end of life. It’s also being driven by the demand from electrification, artificial intelligence (AI) factories, and data centres. Adjusting and expanding infrastructure to meet this demand is essential.

As a result, Aecon’s third-quarter revenue came in at $1.5 billion, 20% higher than the same period last year. And of course, backlog stands at record levels of $10.8 billion.

Aecon’s outlook

The company has a diversified mix of projects by geography, sector, contract size, and type. Please see the graph below for the breakdown of Aecon’s revenue in its latest quarter.
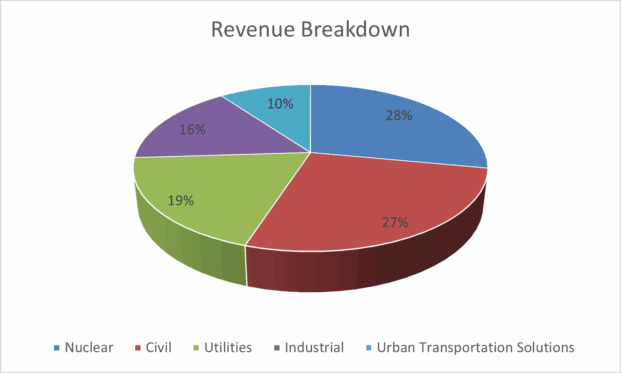
Aecon stock infrastructure

In Aecon, we have a stock that’s benefiting from strong secular growth trends across a diversified set of industries. According to management, the company’s pipeline is strong in Canada, with a little more than $100 billion in projects expected in the next five years. Aecon won’t get all of this work, of course, but it is a contractor of choice, with a leading and growing position in the industry.

Looking ahead, we can also expect Aecon to continue to capitalize on growing nuclear projects in the US. In fact, Aecon is growing its capacity in the US nuclear sector and is now in 15 states, with more than 1,300 people.   

Attractive valuation

Checking in on Aecon’s valuation, we can see that the stock is still trading at very reasonable levels – 18 times next year’s earnings and 14 times 2027 consensus earnings. Given the long-term growth outlook of the company’s business, I would say that this valuation is more than reasonable, with plenty of upside to be had.

The bottom line

Infrastructure spending is expected to continue to be strong over the medium to long term. The growth drivers are there, from aging infrastructure to new industries and changing energy sources. In short, Aecon stock still has plenty of upside potential as it continues to capitalize on these trends. And as a bonus, Aecon stock is currently yielding 2.6%


Fool contributor Karen Thomas has a position in Aecon. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.

More on Investing

Data Center Engineer Using Laptop Computer crypto mining
Tech Stocks

Hammond Power Solutions Is Positioned for the Big Data Centre Buildout: Here’s How I’d Buy It

Analyze the current issues impacting data centres, from AI investment strategies to concerns reminiscent of past financial crises.

Read more »

A meter measures energy use.
Dividend Stocks

Canadian Utility Stocks Report Soon: Should You Buy Before or After Earnings?

Canadian utility stocks report soon. See what Fortis, Emera and Canadian Utilities investors should consider before buying ahead of earnings.

Read more »

Person uses a tablet in a blurred warehouse as background
Dividend Stocks

An Ideal TFSA Stock for October, Paying 0.34% Each Month

Explore the advantages of a TFSA and discover how selecting the ideal TFSA stock can maximize your investment returns.

Read more »

Canada day banner background design of flag
Energy Stocks

76% of Albertans Chose Canada: This Alberta Gas Stock Just Hit a 3-Year High

Tourmaline's costs, market access, and planned dividend increase provide a more durable investment case than referendum relief.

Read more »

shoppers in an indoor mall
Dividend Stocks

A Top-Notch 5.5% Dividend Stock Paying Cash Every Month in Retirement

Crombie REIT offers a dependable yield and a low payout ratio. Discover why it’s a top choice for monthly retirement…

Read more »

A glass jar resting on its side with Canadian banknotes and change inside.
Dividend Stocks

Dividend Income on a Small Budget: Where Canadians Can Start

Stocks like Fortis Inc (TSX:FTS) can produce substantial dividend income.

Read more »

a person watches stock market trades
Energy Stocks

Enbridge Stock: 3 Things to Look for in Its Q3 Results

While geopolitical uncertainties and commodity price volatility remain potential risks, Enbridge’s Q3 outlook remains strong.

Read more »

Group of people in a line at an ATM waiting to make a cash withdrawal
Stocks for Beginners

Canadian Bank Stocks in Late 2026: Which Ones I’d Buy and Which I’d Skip

Canadian bank stocks offer different buying cases in late 2026. Compare Scotiabank, TD and Royal Bank on income, earnings and…

Read more »




