Enbridge (TSX: ENB) has been on a roll for the past 30 months. Investors who missed the rebound are wondering if ENB stock is still undervalued and good to buy for a self-directed Tax-Free Savings Account (TFSA) or Registered Retirement Savings Plan (RRSP) portfolio focused on dividends and total returns.
Source: Getty Images
Enbridge share price
Enbridge trades near $72.50 per share at the time of writing. The stock was as low as $43 in late 2023 and isn’t far off the recent record high above $77.
In order to get a sense of where the stock might be headed in the next few years, it is important to look at the reason the stock pulled back through the second half of 2022 and most of 2023 before reversing course.
Investors will recall that the Bank of Canada and the U.S. Federal Reserve started to raise interest rates in 2022 and continued the rate increases through 2023 in an effort to get inflation under control. Enbridge and its energy infrastructure peers use debt to fund growth investments, including acquisitions and capital projects. The steep rise in borrowing costs that occurred over such a short period of time caused concern among investors who worried that a spike in debt expenses would hurt profits and cut into cash flow that could be used to reduce debt and pay dividends. Some pundits even speculated that Enbridge’s generous dividend would be at risk of being cut to preserve cash.
The recovery in the share price began around the time the central banks indicated they were done raising interest rates. Bargain hunters moved into the stock, anticipating rate cuts in 2024 and 2025. These reductions materialized, helping push ENB even higher.
Earlier this year, the market broadly expected additional rate cuts for 2026. That might not happen as soaring oil prices are putting upward pressure on inflation. Analysts are now starting to warn that rate increases might be needed in Canada and the United States if inflation jumps in the coming months. In that scenario, Enbridge’s stock price would face new headwinds.
Growth
Enbridge is offsetting the impact of higher interest rates by growing revenue and earnings. The company spent US$14 billion in 2024 to buy three American natural gas utilities. Natural gas demand is expected to rise in the United States as new gas-fired power generation facilities are built to provide electricity for data centres.
Enbridge entered 2026 with a $39 billion capital program. As the new assets are completed and go into service, the boost to adjusted earnings and distributable cash flow is expected to be about 5% per year over the medium term. This should support ongoing dividend growth. Enbridge has increased the dividend for 31 consecutive years.
Canada’s new focus on becoming an energy powerhouse bodes well for Enbridge at a time when global demand for North American oil and natural gas is rising.
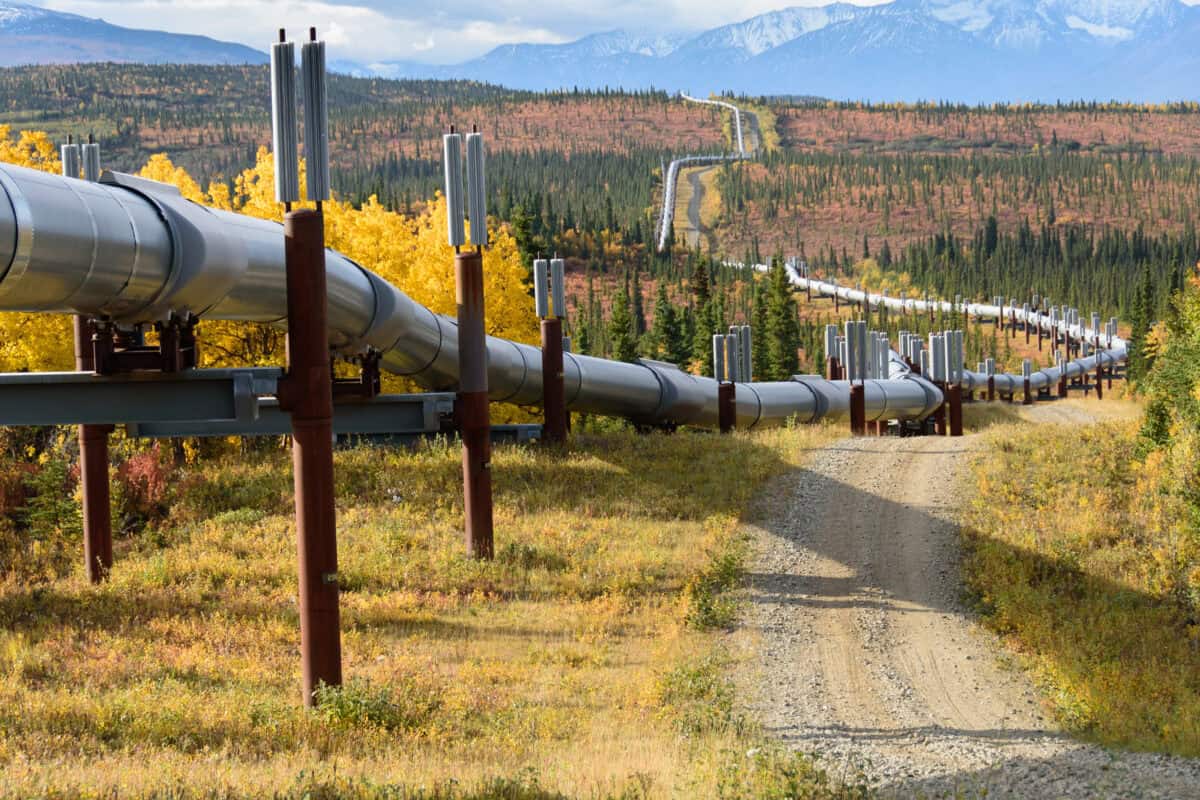
The federal government just approved Enbridge’s $4 billion natural gas pipeline project in British Columbia. Enbridge is also a partner on the Woodfibre liquified natural gas (LNG) export facility being built in the province and scheduled to go into operation in 2027. Additional new oil and natural gas pipeline capacity is being discussed in Canada to connect oil and gas producers to the coast. Enbridge’s expertise in building and operating large energy transmission assets makes it a good candidate to participate in any new major projects.
South of the border, Enbridge owns an oil export terminal in Texas and is investing in natural gas infrastructure to connect new LNG facilities on the Gulf Coast with its natural gas transmission network.
The bottom line
Investors should brace for volatility if oil prices stay near current levels and inflation spikes. A pullback like the one that occurred in 2022 and 2023 is possible in the next couple of years.
That being said, the growth outlook for Enbridge is strong over the medium term, and investors get paid well to ride out turbulence. Earnings and cash flow expansion coming from new assets should support both the dividend and the stock price over the long run.