In the last two months, Canadian National Railway Company (TSX: CNR) stock fell 10% to $165. This has transpired in an environment where investors are worried and cautious. And high energy prices and geopolitical risks threaten to keep it that way. But thankfully, CN Rail’s recent stock price performance in no way reflects Canadian National’s operational performance or outlook.
Rather, it’s the result of elevated fuel prices, which CN has no control over, and the fact that CNR’s stock price had moved higher quite rapidly since the summer of 2025. Simply put, the market has been giving back some of those gains as investors are likely nervous about high energy prices. CN Rail stock appears to be gearing up to continue its ride higher.
So is this 10% drop in CNR’s stock price an ideal time to step in and buy? Or should investors wait it out a little bit more in the hopes of it heading lower to an even more attractive price. Let’s take a look.
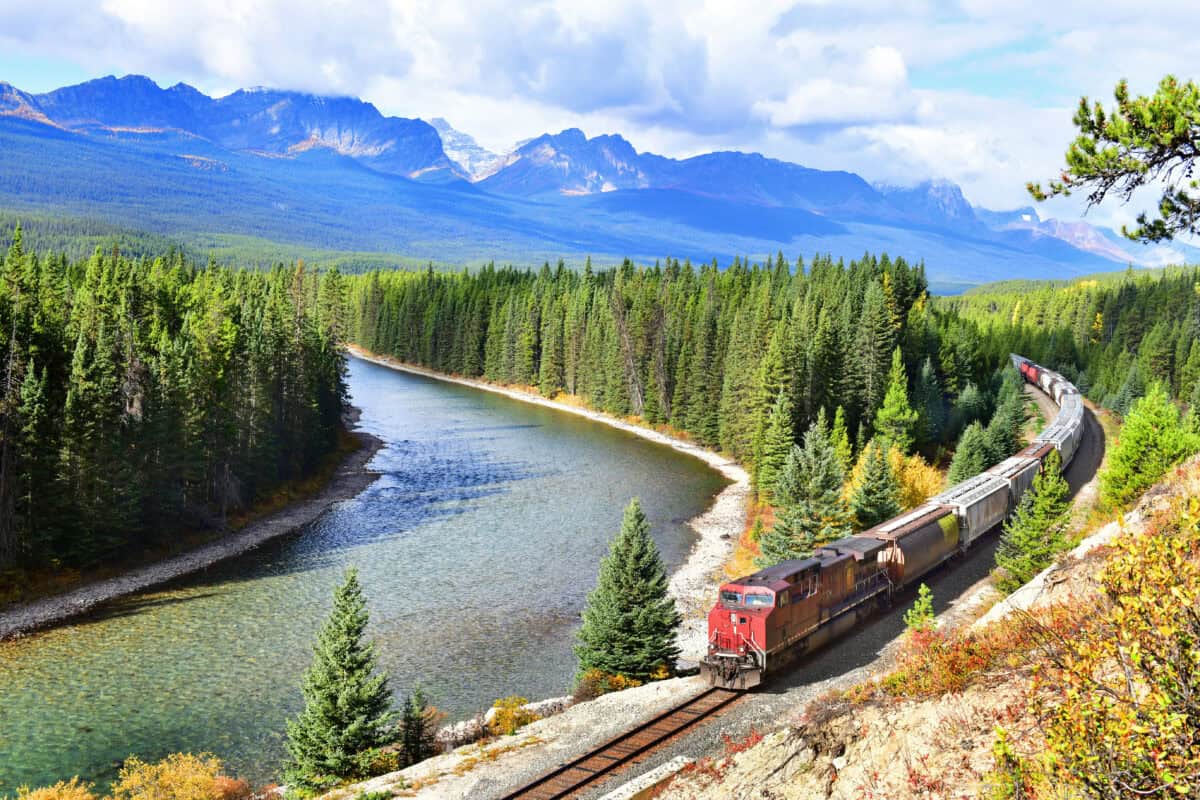
Source: Getty Images
Canadian National and the Canadian economy
Railway stocks like CN Rail stock are the heart and soul of the Canadian economy. As a result, they are uniquely exposed to and plugged into it. You see, the Canadian railways such as CN transport more than $250 billion of goods annually. These goods make up the economy. And they come from a diversified list of sectors. This includes the resource sector (grain crops), crude oil, manufactured products, and consumer goods.
This is already a compelling reason for investors to be interested in CNR stock. Even more reasons to like Canadian National are found in the fact that it enjoys limited competition, high barriers to entry, and the benefits of being a pretty much essential piece of the economic puzzle. These dynamics make Canadian National Railway a stock to own – at the right price.
Latest results
Looking at CN Rail’s most recent results, we can see more of the same – operational excellence and strong growth. Revenue increased 11% to $4.8 billion and earnings per share (EPS ) increased 12% to $2.09. Growth in all of Canadian National’s businesses drove this result, with especially strong growth seen in the grains and energy businesses. Revenues in these businesses grew 18% and 17%, respectively.
While fuel expense did adversely affect CN Rail’s second quarter results, the railway once again made good progress on those factors that it can control. For example, CN achieved record fuel efficiency in the quarter. Also, CN improved utilization and achieved meaningful crew productivity gains. Structural cost discipline and lower capital expenditure intensity supported margins and cash generation.
The bottom line
CNR stock remains well-positioned for continued long-term growth. The company has met or exceeded its earnings targets for quite some time now. Looking ahead, the outlook remains strong. In fact, management recently increased its 2026 EPS guidance and is targeting mid-to-high single-digit adjusted EPS growth.
CNR’s stock price is currently valued at 20 times 2026’s expected earnings, which is a very attractive valuation for a stock like CN Rail. I think that the recent 10% price drop is a good opportunity to start establishing a new position or to add to existing positions. CNR’s track record of operational excellence and earnings and dividend growth speaks for itself.