


The Bank of Canada recently held its policy rate at 2.25%, but that doesn’t mean you need to sit on the sidelines waiting for another rate cut before buying any stock. Canada’s economy has shown improving strength, even as oil sits close to US$95 a barrel amid Middle East conflict, and the ongoing Canada-U.S. trade war has renewed inflation risks.
That scenario could make it difficult for the central bank to lower rates as quickly as some investors might like. Despite a longer stretch with interest rates at 2.25%, I still see many attractive opportunities on the TSX today. However, I think investors need to be more selective about where they put their money.
Let’s look at two top Canadian stocks that could benefit from relatively stable borrowing costs and make attractive additions to your portfolio today.
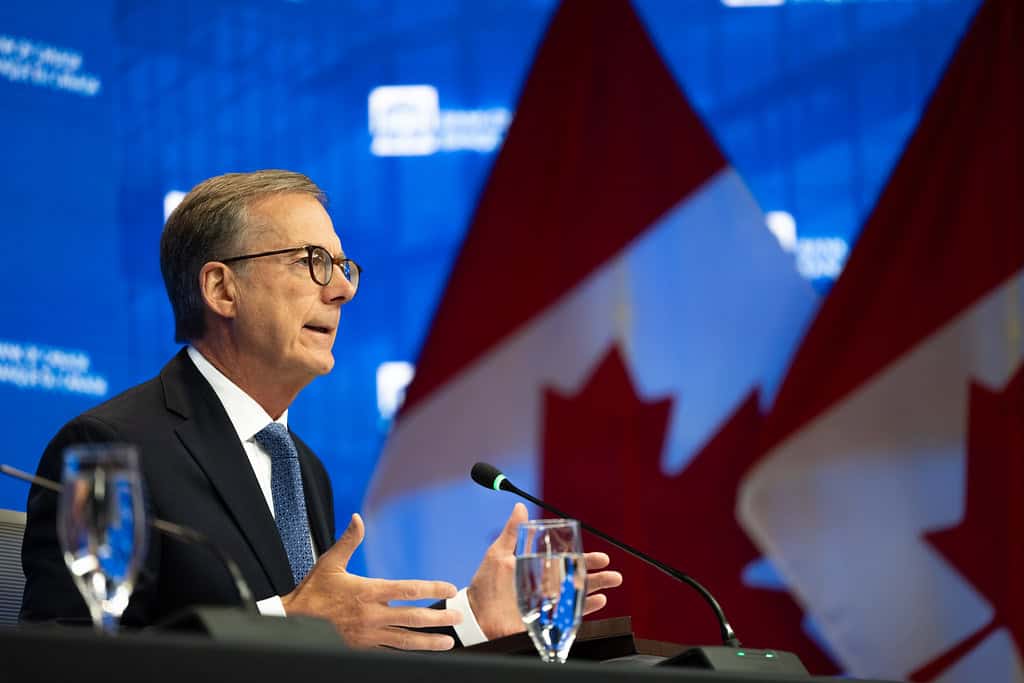
Governor Tiff Macklem; Source: Bank of Canada
BMO stock
Rather than waiting for the Bank of Canada’s next move, I’d look at Bank of Montreal (TSX: BMO) as a way to stay invested while borrowing costs remain relatively stable.
As one of North America’s largest banks, BMO serves about 13 million customers through personal and commercial banking, wealth management, and capital markets businesses. Its shares currently trade at $245.25 per share with a market cap of roughly $171 billion. Income investors also get a 2.8% annualized dividend yield.
BMO stock has delivered impressive gains despite cooling recently. Its shares are up 37% over the last year even as it has pulled back slightly over the last month.
In the third quarter of its fiscal year 2026 (ended in July), the bank’s adjusted net profit climbed 19% year-over-year (YoY) to $2.9 billion. The strength was spread across key businesses. BMO’s Canadian personal and commercial banking adjusted net income rose 15% YoY to $983 million. Meanwhile, its capital markets segment’s adjusted earnings surged 45% to $649 million. Similarly, the bank’s credit trends improved, with provisions for credit losses declining to $722 million from $797 million a year ago.
More importantly, BMO continues to invest in technology and artificial intelligence (AI) capabilities while pursuing profitable loan growth, dividends, and share repurchases. Given all these positive factors, BMO still offers long-term investors an attractive combination of earnings growth and shareholder returns.
RioCan stock
For investors who want more income and exposure to rate-sensitive real estate, RioCan Real Estate Investment Trust (TSX: REI.UN) could be another compelling choice after the Bank of Canada’s latest rate decision.
RioCan owns and manages necessity-based retail properties across Canada. The real estate investment trust (REIT)’s units currently trade at $20.73 per share, giving it a market cap of about $6 billion. In addition, it offers a juicy 5.6% annualized distribution yield.
Its units have gained 11% so far this year. Even after those gains, RioCan remains about 10% below its 52-week high.
The REIT’s recent operating results also give patient investors more reasons to remain optimistic. In the second quarter, RioCan’s core funds from operations rose 5.3% YoY to $0.40 per unit, while net income climbed 6.1% to $0.52 per unit. Its commercial same-property net operating income also grew 4.3% last quarter, backed mainly by strong leasing activity.
Its occupancy remains solid, as RioCan’s retail committed occupancy reached a record 98.8% in the latest quarter, while its blended leasing spread stood at 23.1%.
At the same time, RioCan continues to recycle capital. Pro forma capital repatriation from RioCan Living has reached $1.3 billion, representing 96% of its 2025 to 2026 target.
While holding the policy rate steady does not eliminate financing pressure, RioCan’s strong occupancy, leasing momentum, growth initiatives, and 5.6% yield still make it an appealing income stock for investors who want to protect their portfolio from monetary policy uncertainty.







