


The latest ranking of the 30 top-performing growth stocks on the Toronto Stock Exchange arrived with some emphatic changes. While the average top growth stock in the 2026 TSX30 averaged a record 785% capital gain over three years, beating last year’s 431%, Canadian technology leader Celestica (TSX: CLS) generated more than triple that investment return. Celestica stock’s staggering 2,590% gain between June 30, 2023 and June 30, 2026 could have turned a $1,000 investment into almost $27,000 in just 36 months!
Source: Getty Images
What propelled Celestica stock to a 2,600% gain?
Stock price returns stem from two core sources: growth in fundamental metrics (revenue, earnings, and cash flow per share) and valuation multiple expansions driven by investor sentiment. Celestica stock fired on both cylinders, powered by the artificial intelligence (AI) boom.
Historically a cyclical electronics supply chain partner, Celestica pivotally captured massive demand for AI data centre infrastructure. Its Connectivity & Cloud Solutions (CCS) segment, particularly high-speed data centre switchgear, saw orders surge, pricing firm up, and margins expand.
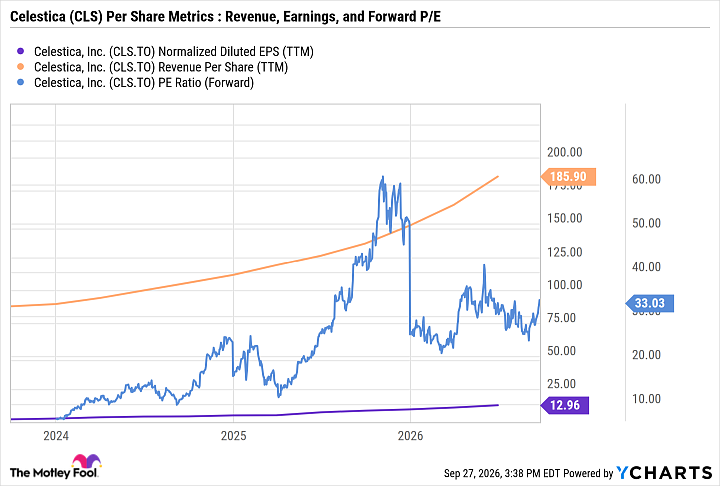
Quarterly revenue leaped nearly 2.5 times from $1.9 billion during the second quarter of 2023 (Q2 2023) to nearly $4.7 billion by Q2 2026. As revenue per share and diluted earnings per share (EPS) surged, the market’s willingness to pay for those earnings tripled, expanding its forward price-to-earnings (P/E) multiple to about 33 times.
CLS Normalized Diluted EPS (TTM) data by YCharts
Can CLS stock keep rising?
The better question from a growth investor could be: could Celestica grow its revenue and earnings some more into the foreseeable future, and will the market continue to pay top dollar per each dollar of earnings? Both scenarios could still play out into 2027.
Celestica stock’s future price performance hinges on whether AI infrastructure spending remains resilient. Fortunately for bullish investors, AI adoption is still transitioning from initial model training to massive, ongoing inference workloads. As agentic AI and complex reasoning tasks scale across the world economy, corporate networking demands are skyrocketing well beyond traditional hyperscalers.
Celestica is uniquely positioned to capitalize on this sustained demand growth wave as its latest DS6000-series switches shift revenue towards higher-margin lines, unlocking further operating leverage and boosting free cash flow margins.
Further, Celestica’s strategic partnerships, including custom design wins and integrations into Advanced Micro Devices’s (AMD) Helios rack-scale AI architecture and OpenAI’s custom Jalapeño inference platform solidify Celestica’s role in cutting-edge AI deployments.
While critics reasonably question if AI investments could stall, citing calls by players like Anthropic to slow down frontier model development, the economic reality resembles a classic prisoner’s dilemma. Tech giants cannot afford to stop investing in AI infrastructure lest they fall behind in the race toward Artificial General Intelligence (AGI). Furthermore, inference demand scales directly with active usage, creating persistent pull-through demand for Celestica’s high-density switchgear.
Valuation and key risk considerations on CLS stock
At a forward P/E of roughly 33 times, Celestica stock no longer trades like a sleepy manufacturing partner. However, with earnings growing at a rapid clip, its forward price-to-earnings-to-growth (PEG) ratio sits around 0.6, a level that traditionally signals growth at a reasonable price.
Investors must remain clear-eyed about the risks on Celestica stock, though. Outside of its booming cloud and enterprise division, Celestica’s legacy segments, including Advanced Technology Solutions (ATS), remain cyclical. Should hyperscalers trim capital expenditures or community activism slow data centre construction, valuation multiples could contract rapidly.
Foolish takeaway
Celestica has morphed from a contract manufacturer into an indispensable AI networking architect. While investors shouldn’t expect another 2,600% surge over the next three years, CLS stock remains an attractive growth holding for long-term investors looking to play the secular expansion of global AI computing infrastructure.







