


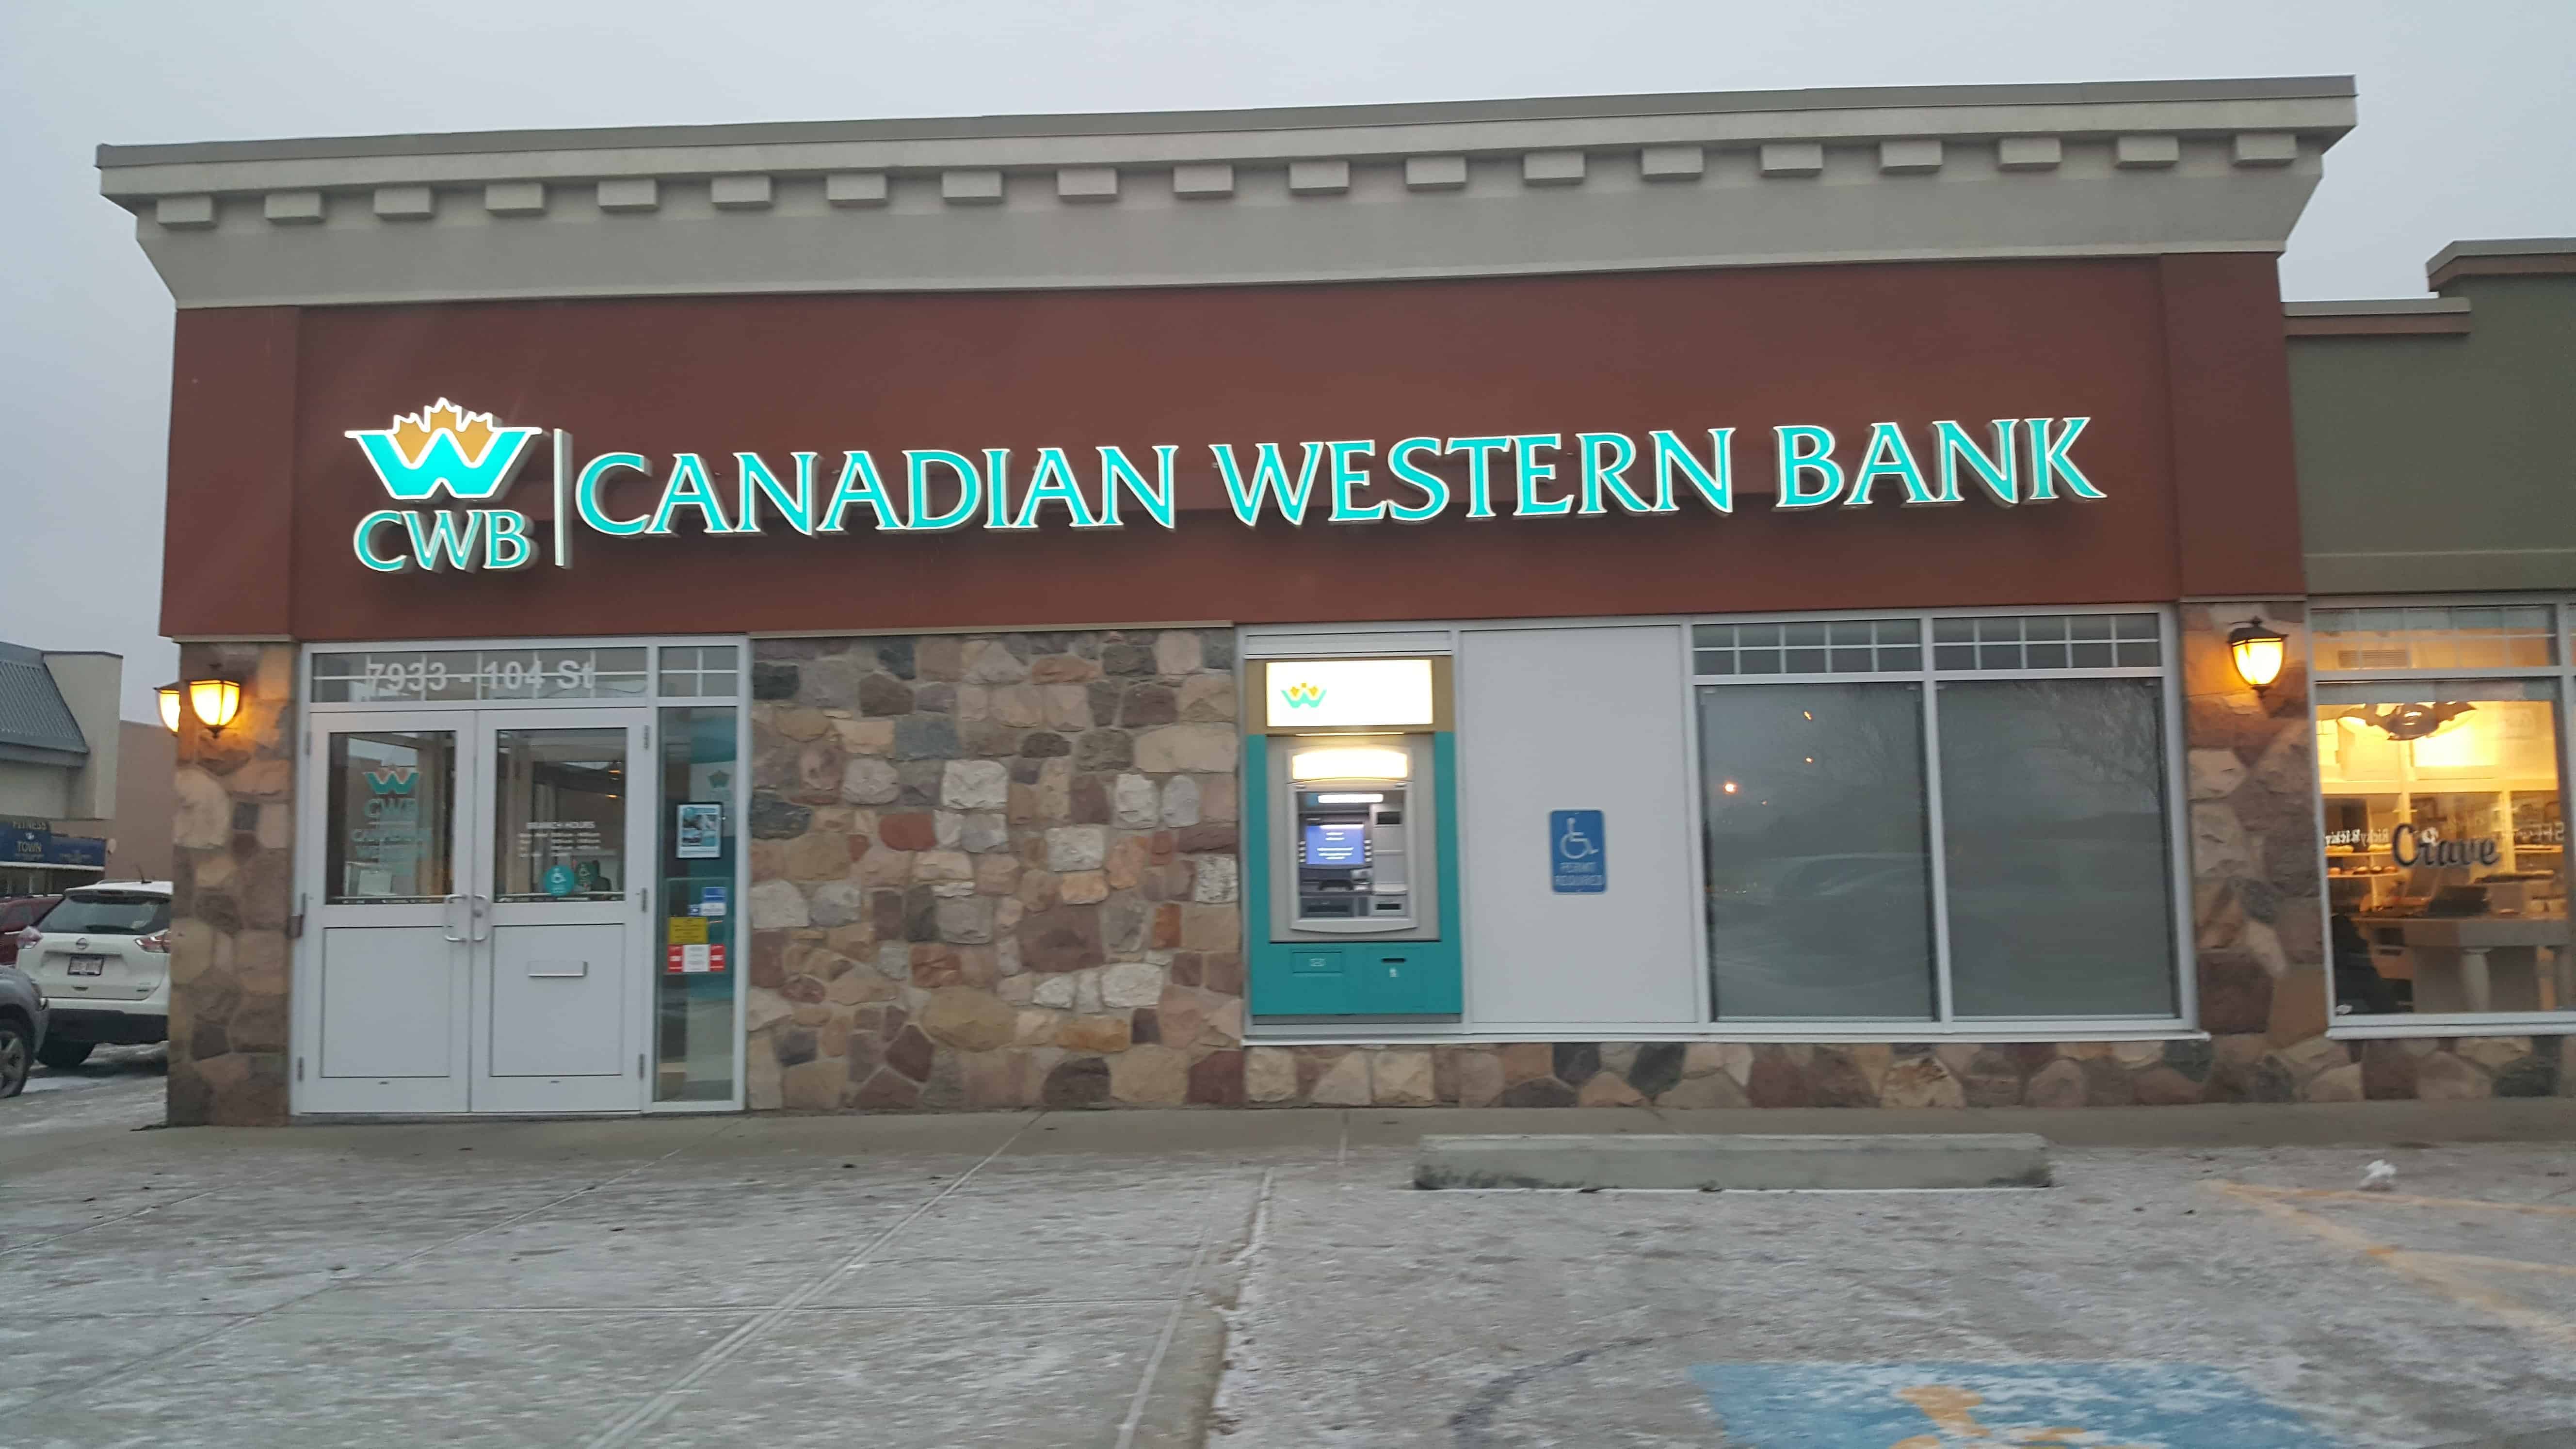
For investors looking to add Canadian financials to their portfolios, the most lucrative investments have traditionally been the big banks. Well known and well covered are Canada’s five major institutions which operate from coast to coast. While these investments have been lucrative in the past, many investors are beginning to ponder what other options are available in the banking sector with less exposure to the country’s most overheated housing markets: Toronto and Vancouver.
Enter Canadian Western Bank (TSX: CWB).
With a focus on western Canada, the bank’s success and share price have hinged largely on the fate of the oil patch with a special contribution from the events at Fort McMurray over the past year. Things have not been very good for the company. During fiscal 2015 and 2016, shares moved from over $38 per share to under $20. With an almost 50% retreat, investors may have felt they were back in the 2008 recession, which saw Canada’s major banks collectively reset to a much lower level.
Although a decline in earnings occurred in fiscal 2016, investors are still on solid footing. In 2015, earnings per share were $3.97 with an average of approximately 80 million shares outstanding, while EPS declined to $2.13 in 2016. Close to eight million additional shares were issued. The piece of the pie held by every investor got proportionally smaller throughout the year — that’s never a good sign.
The good news for investors is investments are made based on looking forward and not on looking backwards. The great news for investors is the opportunity moving forward is huge!
Why?
To begin, investors need to consider the tangible book value per share of the company. Over the past four years, shares of Canadian Western Bank have traded between approximately 0.9 and 1.8 times tangible book value. As of the end of the first quarter of fiscal 2017, the tangible book value per share was approximately $24 per share. With earnings over the next three quarters, investors can reasonably expect to see the number increase to somewhere between $25 and $25.50 per share (after the dividends are paid).
Let’s run through the numbers.
Over the past four fiscal years, the company has reported in the annual report the average return on shareholders’ equity (ROE) to be 9.3% (2016), 19.1% (2015), 14.8% (2014), and 14.2% (2013).
Taking fiscal 2016’s ending shareholders’ equity of $2,342 million and multiplying the amount by an ROE of 9%, the EPS for 2017 can be estimated at $2.34 per share, assuming 90 million shares are outstanding throughout the year. To start the year, there were approximately 88 million shares outstanding.
Out of the expected earnings of $2.34 per share, close to $1 will be paid out as dividends, allowing the company to keep approximately $1.34 in the coffers. This amount will be added to tangible book value. Investors are being offered a significantly better opportunity than they realize. Shares are currently trading near $26.50 per share.
Conclusion
Canadian Western Bank is currently focused on Alberta, which is two years into an economic downturn. The economics impacting Canadian Western Bank may only be starting to turn the corner in a positive way. For Canada’s national banks, however, things could already be going in the opposite direction.







