


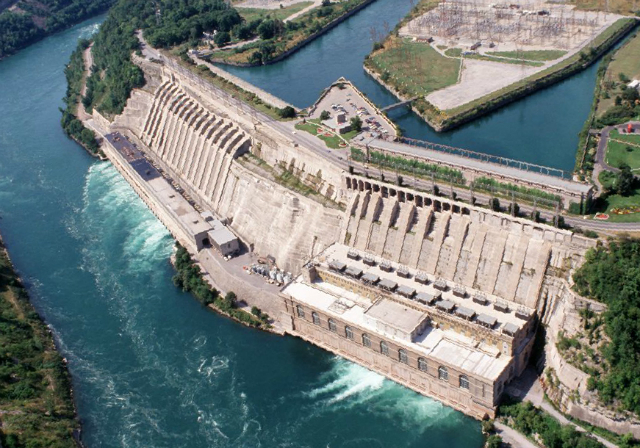
Photo: Ontario Power Generation - Adam Beck Complex. Rotated. Resized. Cropped. Licence: https://creativecommons.org/licenses/by-sa/2.0 Source: https://commons.wikimedia.org/w/index.php?curid=2564777
When things are done right, smaller companies grow faster than bigger ones, because it’s easier to, for example, double a company from $500 million to $1 billion than from $5 billion to $10 billion.
It was no small feat for Algonquin Power & Utilities Corp. (TSX: AQN)(NYSE: AQN) to grow its total assets from ~$5 billion in 2015 to ~$10 billion today. Since Algonquin is much bigger now, don’t expect it to double its assets again in a few years. That said, there are a number of growth drivers for the stable utility.
Algonquin’s growth drivers
Algonquin continues to expand its renewable energy portfolio. It’s constructing two renewable power facilities, which will add 150 MW of generating capacity to its fleet, which currently has a net capacity of ~1,500 MW.
Like most of its power portfolio, the new facilities have long-term power purchase agreements. Further, Algonquin has 211 MW across three additionally renewable energy facilities under development. Half of the new capacity is expected to be in service this year.
As well, Algonquin’s U.S. regulated utilities (natural gas, electrical, and water) will grow organically.
In early March, Algonquin officially entered the global market by investing in Atlantica Yield plc (NASDAQ: AY) and forming a joint venture with a Spain-based company, which will focus on developing and constructing global clean energy and water infrastructure assets.
Algonquin’s global endeavours won’t contribute much initially. Algonquin estimates that by 2022, it’ll earn ~8% of its cash flow internationally.
Is its global expansion good or bad?
Atlantica pays a yield on cost of +5%, a good income for Algonquin. It’s hard to say whether Algonquin overpaid for Atlantica or not, however, because Atlantica is a high-growth utility with a lot of debt; its S&P credit rating is BB and its debt-to-asset ratio was ~82% at the end of 2017 compared to Algonquin’s BBB S&P credit rating and debt-to-asset ratio of ~70%.
The joint venture is probably a good thing, as it reduces Algonquin’s risk of entering the global market on its own.
Investor takeaway
Algonquin is in the sweet spot for growth. Its mid-cap size enables growth at an above-average pace while posing less risk than small-cap companies.
Algonquin continues to develop power projects and is always on the lookout for accretive acquisitions for its power and utility portfolios. In order to grow the company, Algonquin has a capital program of $7.7 billion over the next five years. The company is also expanding internationally.
In aggregate, these should help support management’s target of growing the dividend by ~10% per year through 2022 while improving its payout ratio. Currently, Algonquin offers a nice yield of ~4.7%.







