Watching SoFi Technologies (NASDAQ: SOFI) stock skyrocket over 320% from its late-2022 lows triggers the fear of missing out (FOMO). SoFi stock recently completed a remarkable U-shaped recovery while posting record revenue and earnings. However, successful investing isn’t about chasing past performance; it’s about identifying future value. For Canadian investors, buying SoFi today means paying a premium price for its already-achieved success. Instead of chasing this U.S. fintech giant at peak valuation, a smarter strategy may involve pivoting to undervalued Canadian alternatives poised for their own breakouts.
Source: Getty Images
Why SoFi stock’s valuation could be a red flag
SoFi’s operational performance is outstanding. Its second-quarter results were a blowout, with adjusted net revenue surging 44% year over year to a record US$858 million. Adjusted EBITDA (earnings before interest, taxes, depreciation, and amortization) exploded by 81%, showcasing significant growth and operating leverage that prompted management to raise its full-year 2025 guidance.
However, stellar results are only one half of the investment equation; the price you pay is the other. The fintech stock now trades at a forward price-to-earnings (P/E) multiple of approximately 50. To put that in perspective, the industry average P/E is around 29.6. This means new investors are paying a 70% premium for every dollar of SoFi’s future earnings compared to the average industry peer.
Furthermore, the current share price has surpassed the average analyst price target, implying a potential 25% downside over the next 12 months. The risk/reward profile is simply unfavourable for new money in September.
The top Canadian contender: Propel Holdings stock
If your investment theme is high-growth fintech but the goal is prudent valuation, Propel Holdings (TSX: PRL) stands out as a top Canadian stock pick at a reasonable valuation despite its 350% total return during the past three years.
Propel is a financial technology company that uses its artificial intelligence-powered platform to provide credit access to underserved consumers. While smaller than SoFi, its growth is just as explosive, and its profitability is rapidly accelerating.
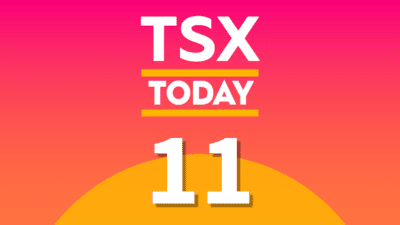
The core advantage for Propel investors today is valuation. Propel trades at a much more reasonable forward price-to-earnings multiple of 11, significantly cheaper than SoFi’s 50.
But the real differentiator between SoFi and Propel Holdings is the latter’s shareholder-friendly capital-budgeting policy. While SoFi pays no dividend, Propel has committed to returning capital to shareholders through dividends and is growing that dividend at high double-digit annual rates. Yielding 2.4% currently, Propel Holdings’s dividend provides a tangible income stream while you wait for the company’s growth narrative to play out.
With Propel’s roaring dividend, you don’t have to sell any stock to realize a return on the investment. PRL stock is a powerful combination of deep value, strong growth, and shareholder-friendly returns that SoFi may not currently match.
Another beaten-down opportunity: Lightspeed Commerce
A contrarian investor who missed buying the dip in SoFi stock could find another underpriced opportunity on Lightspeed Commerce (TSX: LSPD) today. After a brutal short-seller report during the pandemic, the company has quietly executed an impressive turnaround.
Its recent first quarter 2026 revenue grew 15% year over year, exceeding expectations. More importantly, its path to profitability is solidifying, with adjusted EBITDA soaring 55% as cost-optimization measures pay off. Yet, the market remains skeptical, and this disbelief has created a profound value gap.
Lightspeed stock trades at just 1.7 times its revenue per share. The average stock in its industry trades at a lofty 6.7 times sales. This glaring discrepancy hasn’t been lost on management, which authorized an aggressive US$400 million stock-buyback program this year — a strong signal that the company believes its stock is deeply undervalued.
To be fair, Lightspeed is on a path to prove sustainable operational profitability over the coming quarters. Sustained double-digit revenue growth rates and an achievement of convincing profitability over the next 12 months may trigger a bullish run on LSPD stock. Investors seeking a potential multi-bagger may wish to evaluate Lightspeed stock’s compelling risk/reward setup further.
Investor takeaway
SoFi’s operational success is impressive, but its stock price appears to have already baked in that excellence. Chasing SoFi stock now carries significant downside risk. Propel Holdings stock offers a more attractive valuation, a growing dividend, and robust growth, while Lightspeed Commerce stock offers a classic contrarian opportunity, trading at a deep discount despite a clear turnaround underway. Both Canadian stocks present a potentially stronger chance for outperformance than SoFi over the next 12 months.