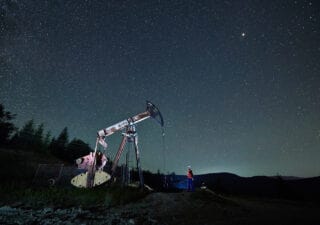
After recently dipping to a month low, oil continues to rally, closing in on the US$55-per-barrel mark required by many energy companies to fund their capital programs and stay free cash flow positive for 2017. This has sparked considerable enthusiasm among energy investors as they search for stocks that are well positioned to benefit from higher oil prices.
One intermediate upstream oil producer that stands out for all the right reasons is Whitecap Resources Inc. (TSX: WCP). Since the deep decline in crude started in late 2014, its share price has fallen by 31%, leaving it attractively valued for investors seeking a stock to play the inevitable rebound in oil.
Now what?
One of the most attractive aspects of Whitecap is the quality of its oil assets.
These are predominantly comprised of light oil acreage that sits across the Viking, Cardium, Deep Basin, and Boundary formations in British Colombia, Alberta, and Saskatchewan.
The quality is emphasized by Whitecap’s ability to grow its oil reserves at a rapid rate. At the end of December 2016, its oil reserves had grown by 28% compared to a year earlier to be 356 million barrels, which is almost 10 times higher than they were at the end of 2011.
This has underpinned Whitecap’s ability to expand its oil production.
For 2016, the company produced almost 46,000 barrels of crude daily, which represents growth of 12% year over year. More importantly, especially with oil moving higher, Whitecap is forecasting a production increase of up to a 24% for 2017, allowing it to take full advantage of the recent oil rally. This is supported by a very healthy 71% increase in development capital, which is being used to fund the drilling of 164 development wells.
Importantly, Whitecap’s capital expenditures are internally funded, and the company expects to be free cash flow positive to the tune of $133 million if West Texas Intermediate (WTI) averages US$55 per barrel during 2017. Even if WTI falls to US$45 per barrel, Whitecap has forecast free cash flow of $59 million.
Nonetheless, despite the optimism surrounding crude, particularly in the wake of the OPEC agreement to cut production, Whitecap moved to protect itself from the risk of lower oil prices. It has done this by hedging just over 40% of its 2017 production at over $63 per barrel.
This not only reduces the downside risk posed by lower oil prices, but it also minimizes the impact on its capital program and ultimately its bottom line.
Whitecap’s oil reserves have low decline rates and strong capital efficiencies, which means that Whitecap’s operations have a respectable netback which came to $26.46 per barrel for 2016. The 27% decline compared to 2015 can be attributed to a lower average sale price rather than increased costs.
In fact, operational expenses fell 3%, and transport costs dropped an impressive 43% compared to a year earlier. While there are signs that further significant cost reductions are unlikely, those already achieved are sustainable, meaning that netbacks will rise sharply because of the rally in crude, which now sees it trading at above US$50 per barrel.
So what?
For all of these reasons, Whitecap will perform strongly over the course of 2017, especially if oil remains at over US$50 per barrel for the remainder of the year. This will not only give its bottom line a healthy bump, but it should cause its share price to rise appreciably. While investors wait for this to occur, they will continue to be rewarded by Whitecap’s sustainable dividend yielding a handy 3%.