


Canadian dividend investing practically played on easy mode for over a decade. During the ultra-low interest rate era following the 2008 financial crisis, TSX passive income darlings got treated like high-yielding bond substitutes. You bought them, reinvested the dividends, and went about your life.
That cozy playbook is officially broken.
With 10-year treasury yields becoming more elevated in 2026 and generous financial houses offering 1-year guaranteed investment certificates (GICs) at rates up to 3.8% and 3-year terms at 4.3%, income seekers face a stark reality: Why take on significant equity risk for a 2% or 3% dividend yield when risk-free GICs pay noticeably more while guaranteeing your principal?
The counterargument, of course, is anchored on long-term dividend raises and capital growth prospects. Equities offer residual claims on growing cash flows and compounding earnings that static GICs simply can’t match. But market conditions shift, debt burdens balloon, and growth drivers stall. Yesterday’s ultimate dividend champions can quickly transform into today’s capital sinkholes.
Here is a fresh look at three legendary TSX dividend stocks to see if they still deserve a spot in your portfolio.
Source: Getty Images
BCE stock: A high-yield dilemma
Canadian telecommunications giant BCE (TSX: BCE) has been a portfolio staple for decades, offering a respectable 5.7% yield. However, that yield comes in the wake of a historic 56% dividend slash in May 2025. The telecom sector has been a brutal place for total returns, with BCE stock delivering negative total returns over the last five years.
The company halted its ambitious home fibre program after regulatory rulings diluted future returns on capital, pivoted toward acquiring U.S.-based Ziply Fiber, and is reallocating resources into artificial intelligence (AI) data centres. While the dividend trim brought the free cash flow payout ratio back into a safer target range, lingering leverage and strategic uncertainty continue to drag on performance.
BCE looks like a deeply discounted turnaround play, but until leverage comes down, the risk of it remaining a growth-stagnant yield trap isn’t zero.
Enbridge stock: Is a 5.7% yield enough as capital gains stall?
Enbridge (TSX: ENB) stock stands as one of Canada’s most dependable income compounders with 30 consecutive years of dividend increases. After trading at eye-popping yields near 8% in 2023, share price appreciation has compressed its yield to a tighter 5.7%. That was good for early investors who got both a juicy yield and capital gains. But the dividend stock may no longer be as wonderful for new money buying the stock in September 2026.
Enbridge is on an aggressive, debt-heavy acquisitions-heavy growth trajectory. It recently announced US$3.2 billion in acquisitions in U.S. crude gathering assets while executing on a $41 billion organic growth pipeline. As acquired gas utility assets and new renewable energy assets increasingly dominate its revenue mix, Enbridge’s cash flow profile increasingly mirrors a regulated utility. Consequently, future dividend growth is settling into modest annual “adjustments” of around 3%.
Resultantly, Enbridge stock may morph into a slow-moving bond proxy. If predictable cash income is your sole objective, the 5.7% dividend yield should satisfy. But if you are counting on meaningful capital appreciation, prepare for a long, quiet wait.
Toronto-Dominion Bank (TD) stock
The Toronto-Dominion Bank (TSX: TD), or TD Bank stock, has staged a remarkable recovery from its lows following U.S. anti-money laundering (AML) regulatory penalties. The top Canadian bank stock’s formidable domestic franchise and robust capital buffer made that historic price weakness a classic entry point. However, following a massive 106% run-up from its troughs over the past three years, TD Bank stock’s yield has shrunk to just 2.7% for new buyers who buy the top Canadian bank stock at stretched valuations today.
Crucially, the U.S. asset cap remains in place, placing a structural ceiling on a growth driver within North America’s largest economy, while the domestic economy battles trade headwinds.
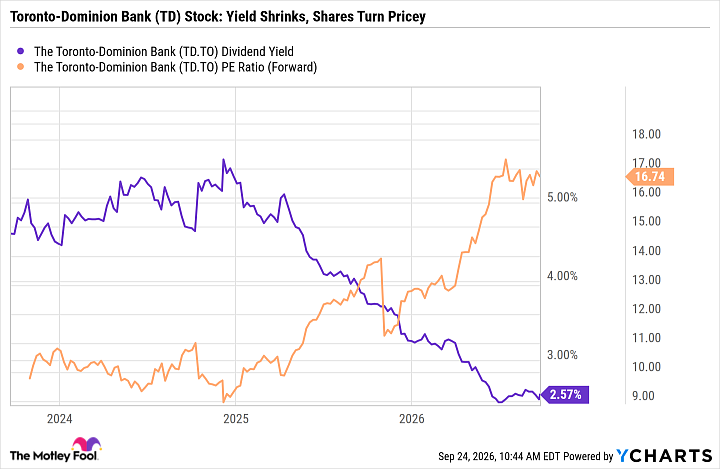
TD Dividend Yield data by YCharts
Meanwhile, TD stock’s forward price-to-earnings ratio has expanded from under 10 times in early 2025 to nearly 17 times today. New investors are paying a premium valuation for potentially capped earnings growth while receiving a lower yield than a standard bank GIC.
While TD stock remains a premier blue-chip financial sector stock to buy and hold, its stretched valuation suggests total returns could underperform rival income options over the next two to three years.







