Demand for retirement income solutions is growing. Increases in the number of self-employed and self-directed investors in Canada continue to support growth in annuity sales as individuals look to secure a guaranteed passive income stream in retirement. Canadians nearing retirement face a critical choice today: go for absolute income certainty with annuities or take a chance on capital growth and liquidity with dividend stocks. Your choices won’t be simple, and the ultimate decision will depend on a few factors we can discuss here.
On one side stands annuities, insurance contracts that may convert a lump sum into contractually guaranteed lifetime cash flow. On the other side stands dividend-paying Canadian stocks, assets that generally generate recurring regular income while potentially growing your underlying capital as stock prices rise. Evaluating this choice requires looking beyond initial yields to examine longevity risk, inflation defence, tax efficiency, and ability to control your capital.
Source: Getty Images
Annuity income guarantees versus inflation defence
Annuities excel at creating a guaranteed, regular income payment stream, and if you go with a lifetime payout option, they can completely eliminate the risk of outliving your capital (longevity risk) as well as the sequence-of-returns risk that equity portfolios may possess (if a severe market downturn coincides with the onset of your retirement).
Backed by Assuris protection for up to $5,000 per month or 90% of promised benefits (whichever is higher), a single life annuity ensures you can’t outlive your income regardless of market downturns. How is that possible? Annuitants who pass on earlier than their statistically expected lifespans “donate” their capital and payouts to those who live longer.
However, the peace of mind from annuities comes with a hidden cost: inflation risk. Most Canadian annuity payouts are fixed in nominal dollars. A constant income stream that feels generous at age 65 can suffer severe purchasing power erosion by age 82, threatening a retiree’s ability to maintain a desired lifestyle. Indexed annuities do offer inflation protection, but they often start with lower initial payouts.
Interestingly, dividend stocks offer the exact antidote to long-term inflation. High-quality businesses across Canadian banking, energy infrastructure, utilities, and senior housing industries often possess proven structural pricing power. As their operating cash flows expand, these large-cap stocks routinely raise their dividends to shareholders. Over a multi-decade retirement, dividend growth may preserve real purchasing power in a way fixed annuities can’t match.
Annuities vs. dividend stocks: Growth and the capital control dilemma
The trade-off between annuities and dividend stocks extends directly to your personal balance sheet flexibility and tax efficiency. Purchasing a traditional annuity is often an irreversible decision that irrevocably forfeits capital liquidity and estate transfer capabilities. In contrast, holding Canadian dividend stocks maintains complete control over your principal, leaving capital available for unexpected medical emergencies or wealth transfer to beneficiaries.
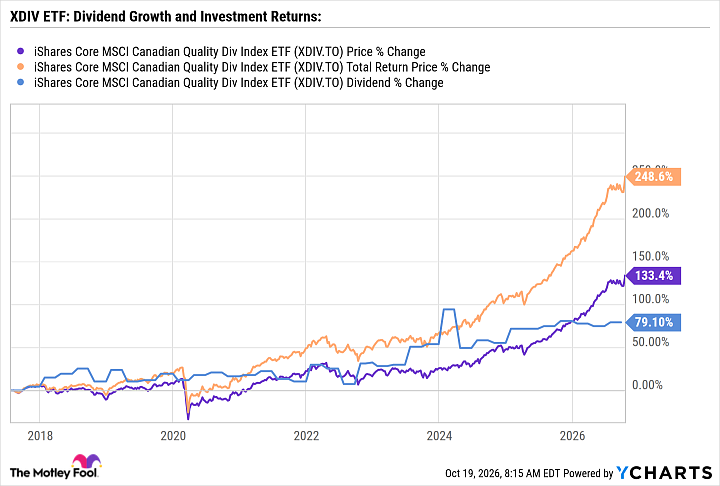
Most noteworthy is the growth divergence. Dividend stocks have often increased a retirement investor’s capital. For example, the iShares Core MSCI Canadian Quality Dividend Index ETF (TSX: XDIV) has generated a total return of nearly 250% over nearly a decade, with dividends fully reinvestment. The dividend exchange traded fund (ETF) has raised its monthly dividends by 79% over the period, beating inflation. Even if an investor withdrew all monthly dividends to fund living expenses, their capital could have grown about 133% higher since 2017. The ETF charges a low management expense ratio (MER) of 0.11% annually.
Further, in non-registered taxable accounts, Canadian dividend stocks also enjoy superior tax mechanics. Eligible dividends receive preferential treatment via the Canadian Dividend Tax Credit, often resulting in lower effective tax rates for low-income retirees compared to annuity fixed income.
While non-registered prescribed annuities provide level tax treatment by spreading capital and interest payments evenly, registered annuities may remain fully taxable as regular income upon withdrawal.
An optimal retirement investment strategy
A sound wealth management framework balances asset allocation between competing passive income sources in retirement.
As retirement nears, you may tally your essential, non-negotiable living expenses. Any gap between these fixed lifestyle costs and guaranteed government benefits like CPP and OAS payouts can be closed using a fixed annuity. Once your baseline living costs are fully insured against market volatility, the remaining capital may be deployed into a diversified portfolio of Canadian dividend growth stocks.
This hybrid investment model secures absolute peace of mind for daily survival while capturing the capital growth, inflation protection, and tax efficiency desirable for a flourishing retirement.