TC Energy (TSX: TRP) has been on a strong run, with its shares surging close to 34% over the past year and now hovering near their 52-week high of $72.26. The rally reflects growing investor confidence in the company’s fundamentals, supported by a mix of strategic initiatives, including the spinoff of its liquids pipelines business, stable cash flows, and strengthening demand for natural gas and power.
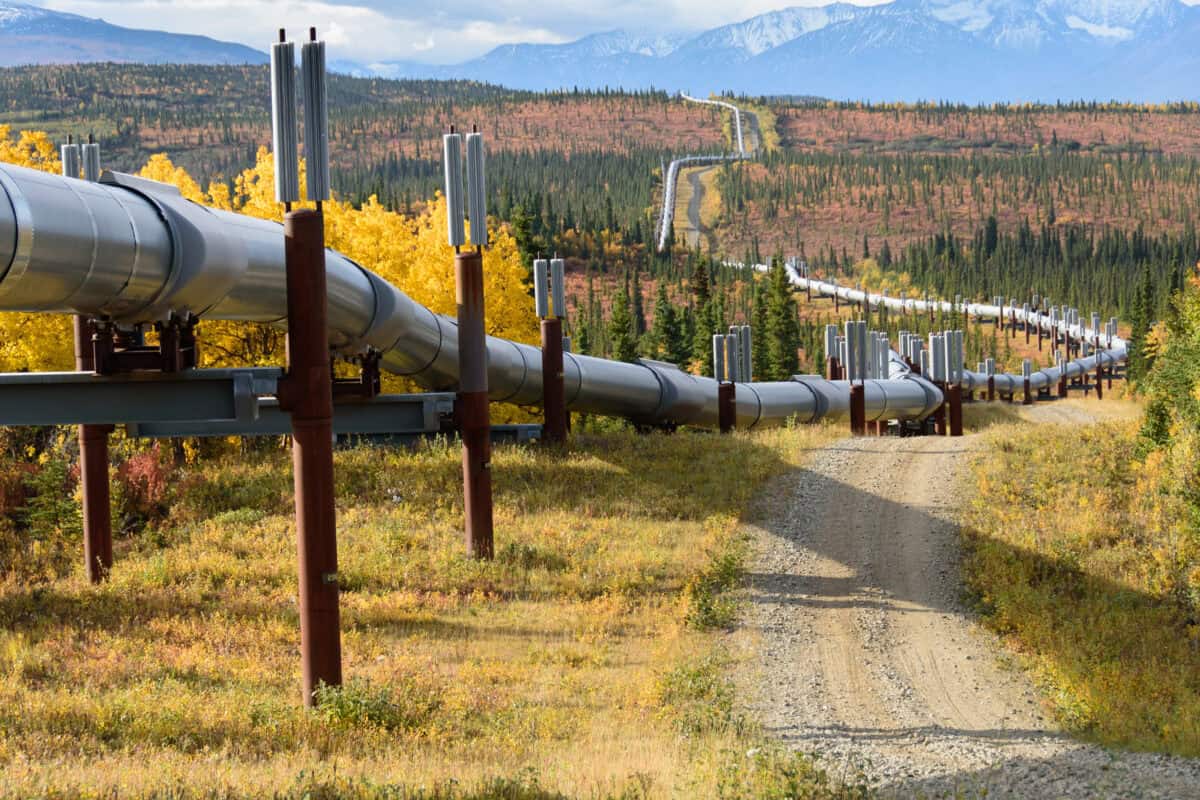
TC Energy is one of North America’s leading players in natural gas transportation and storage. Its extensive pipeline network connects low-cost natural gas basins with premium markets across Canada, the U.S., and Mexico. This infrastructure provides critical connectivity between supply and demand and positions TC Energy as a key enabler of liquefied natural gas (LNG) exports, a sector expected to see strong growth in the coming years.
TC Energy also maintains a significant presence in power generation, producing electricity from a balanced mix of nuclear, natural gas, wind, and solar assets. This diversification adds resilience to its business model, offering a steady stream of income while also giving the company exposure to the growing renewable energy space.
The spinoff of its liquids pipelines business has been a significant catalyst. The move helps TC Energy to sharpen its focus on natural gas infrastructure, a segment with long-term growth tailwinds tied to global energy demand and the transition toward cleaner fuels.
Against this backdrop, let’s take a closer look at TC Energy’s prospects.
Source: Getty Images
TC Energy to deliver steady growth
TC Energy is well-positioned to deliver solid growth as the demand for natural gas and power continues to accelerate in North America. The global push toward electrification, the boom in LNG exports, the shift away from coal toward more reliable, lower-emission fuels, and the increasing energy needs of data centres provide a multi-year platform for growth.
With an extensive pipeline network, TC Energy is uniquely positioned to capture this growth. Its vast portfolio of assets gives the company both scale and diversification to capitalize on the growing energy demand.
Equally important is TC Energy’s strong pipeline of new projects. Demand for additional capacity continues to rise, with customers across different sectors seeking to expand and scale their operations. This reflects the solid fundamentals driving the utilization of its assets.
Overall, TC Energy has significant growth opportunities for its natural gas infrastructure and power business.
TC Energy is a dependable income stock
TC Energy is a reliable choice for income-focused investors, and for good reason. The company’s highly regulated and contracted cash flow enables it to pay and increase its dividend year after year. TC Energy has raised its distribution for 25 consecutive years. At present, the company offers a quarterly dividend of $0.85 per share, translating to an attractive yield of over 4.8%.
TC Energy’s payouts are supported by its infrastructure assets, driven by long-term agreements with financially sound counterparties. Notably, approximately 97% of the company’s earnings before interest, taxes, depreciation, and amortization come from regulated or take-or-pay contracts. This structure acts as a buffer against price and volume swings, insulating TC Energy from volatility and supporting its earnings.
Looking ahead, the company continues to pursue growth in a disciplined, low-risk manner. It expects annual net capital expenditures in the range of $6 to $7 billion in both 2025 and 2026, focusing on projects backed by long-term contracts. This strategy will drive its earnings and cash flow, supporting 3% to 5% annual growth in its dividend and deleveraging its balance sheet.
Outlook for Investors
TC Energy’s fundamentally solid business, regulated and contracted cash flows, and significant demand tailwinds suggest that the long-term investment case remains compelling. While the valuation is less of a bargain right now, TC Energy offers both income and growth potential, making it a stock worth buying and holding for decades.